
Rambus (RMBS), Why Is The Story Getting More Complicated?
Index removal puts Rambus back under the microscope
Rambus (RMBS) has just been removed from the PHLX Semiconductor Sector Index, a change that can prompt mechanical selling by index trackers and raise fresh questions about how investors should now view the stock.
Rambus has recently paired a technology collaboration with M31 Technology Corporation with index removal, and that mix has come after a sharp 18.95% 1 month share price return but a softer 3.87% year to date share price gain. The 5 year total shareholder return of 365.13% contrasts with a flat 1 year total shareholder return that hints at fading momentum in the nearer term.
Scan how Rambus compares to peers reacting to index changes by checking out a curated set of 89 AI infrastructure stocks that are shaping high performance computing and data-heavy applications.
Rambus looks like a solid chip designer on the surface, yet an index exit after a strong 1 month run raises a sharper question. Is this quality story now a fair deal or an expensive one?
Most Popular Narrative: 31% Undervalued
Rambus last closed at $103.12 while the most followed narrative pegs fair value at $149, which frames a wide gap that investors now have to judge against index removal and recent price swings.
Ongoing rapid growth in AI and data center workloads is accelerating the industry's need for high-speed memory interfaces and connectivity, driving demand for Rambus's DDR5, HBM4, and PCIe 7.0 solutions. This is viewed by some observers as positioning the company for sustained top-line revenue growth as new design wins and customer qualifications convert into production orders.
See why 35 investors see Rambus as 31% undervalued.
Result: Fair Value of $149 (UNDERVALUED)
Still, the Rambus narrative can crack if heavy dependence on DDR5 products meets slower customer uptake or if rising competition squeezes the rich licensing and chipset economics.
Find out about the key risks to this Rambus narrative.
Another Lens On Rambus Valuation
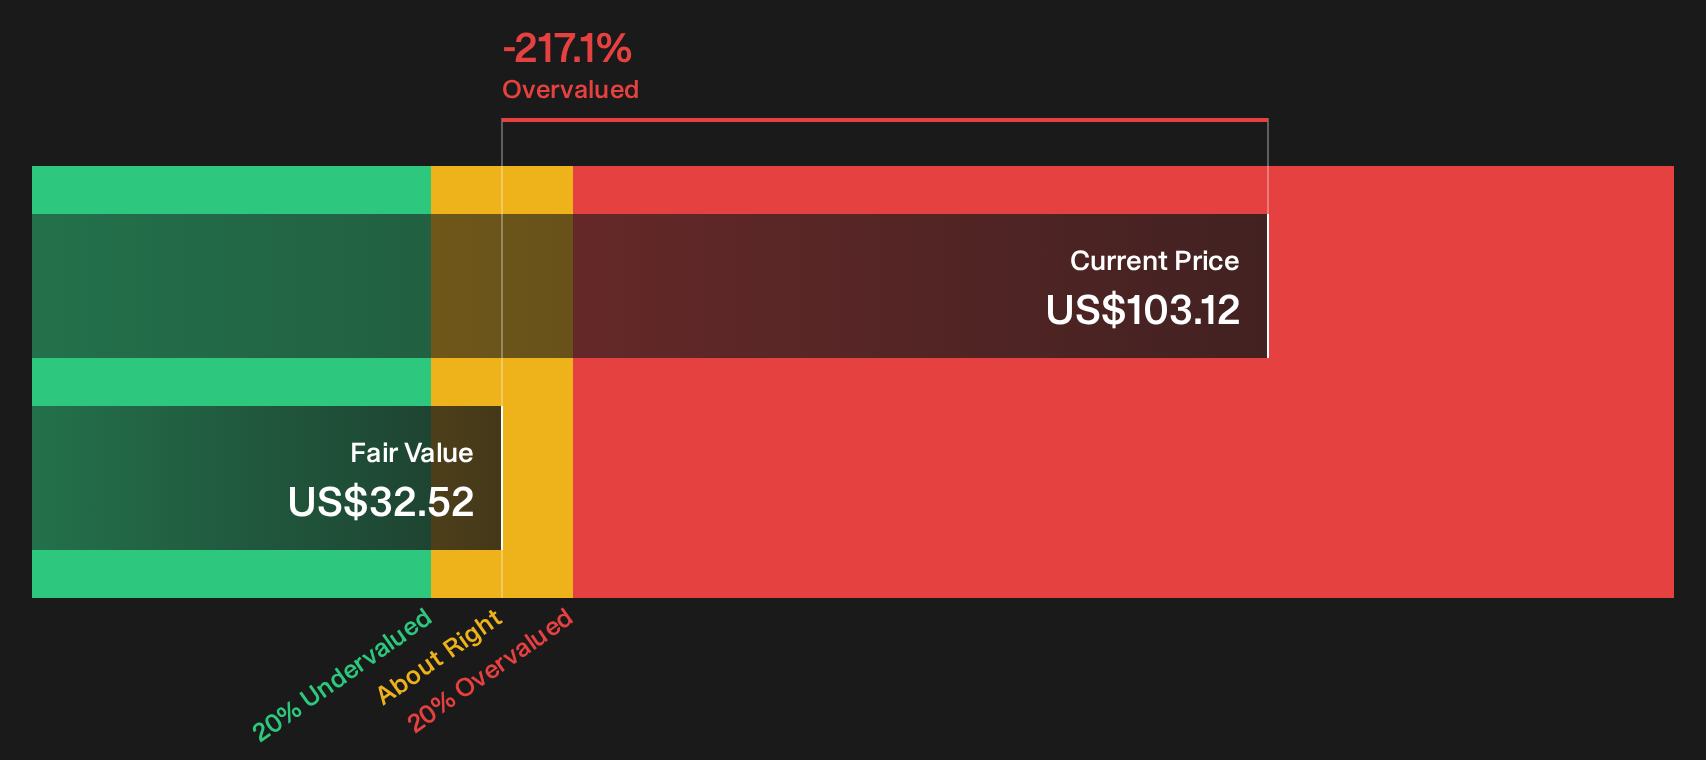
That popular fair value of $149 leans heavily on future earnings estimates and P/E math. Our DCF model paints a very different picture. On that framework, Rambus at $103.12 trades well above an estimated future cash flow value of $32.52, which indicates less potential upside and more mispricing risk if cash generation disappoints.
For anyone weighing which signal to trust, it helps to see how our SWS DCF model fits together in detail, then judge which set of assumptions feels more realistic for you as an investor. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rambus for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Does the Rambus story here feel too cautious, or not cautious enough? Act quickly and review the full reward profile for yourself with 3 key rewards
Looking for more Rambus-sized opportunities?
If Rambus has you thinking harder about where the next edge could come from, do not stop with a single ticker. Use targeted screens to surface fresh ideas that match your risk comfort and income goals.
- Target resilient upside by focusing on companies that screen as high quality and potentially overlooked through the 17 high quality undiscovered gems.
- Prioritise capital protection and steadier rides by filtering for businesses flagged as 32 resilient stocks with low risk scores.
- Build a stronger core portfolio by scanning for firms with durable finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com