
Learn Why The Bull Case For Adeia Stock Could Change Following New CEO Appointment
- Adeia Inc. appointed Dipti Vachani as chief executive officer and board member effective 12 October 2026, succeeding Paul E. Davis, who moved to an advisory role through year end to support the transition.
- Vachani’s nearly 30 year semiconductor career across Arm, Intel, Skyworks and Texas Instruments signals a push to deepen Adeia’s semiconductor and media IP focus, expand recurring licensing revenue and broaden exposure beyond Pay TV.
- We will now assess how Adeia’s investment narrative may shift with Dipti Vachani’s semiconductor heavy background shaping leadership direction.
Adeia Investment Narrative Recap
Adeia stock is for investors who buy into an IP licensing model tied to streaming, semiconductors and AI infrastructure. The immediate focus is execution on complex, multi year media and chip agreements while keeping litigation costs in check. The CEO change looks operationally aligned with this story and does not obviously alter the near term catalyst, which is closing and expanding licensing deals.
The biggest near term risk still sits in a concentrated customer base and a maturing patent portfolio, not the leadership transition itself. Higher debt levels and the prospect of modestly declining earnings forecasts add pressure on management to keep cash generation, renewals and new agreements on track.
The central announcement is the appointment of Dipti Vachani as CEO and board member. Her background across Arm, Intel, Skyworks and Texas Instruments sits squarely in semiconductor ecosystems, advanced computer architectures and AI infrastructure. For an IP platform that is leaning harder into RapidCool, hybrid bonding and broader chip licensing, that experience directly touches Adeia’s operational focus.
What matters for you is execution. Can Adeia turn that semiconductor and AI infrastructure expertise into more recurring, multi year agreements and a broader customer mix beyond Pay TV? The board says the mandate is to strengthen technology leadership, diversify recurring revenue streams and keep investing in new growth areas while still managing litigation, regulatory risk and debt.
Adeia's current earnings sit at $122.7 million, with analysts expecting earnings of $108.1 million by 2029. This implies a decline of about $14.6 million, alongside forecast 2029 revenue of $465.3 million and relatively flat revenue trends over the next few years.
Uncover why Adeia's fair value indicates a 74% potential upside to its current price. This gap could narrow quickly as sentiment shifts.
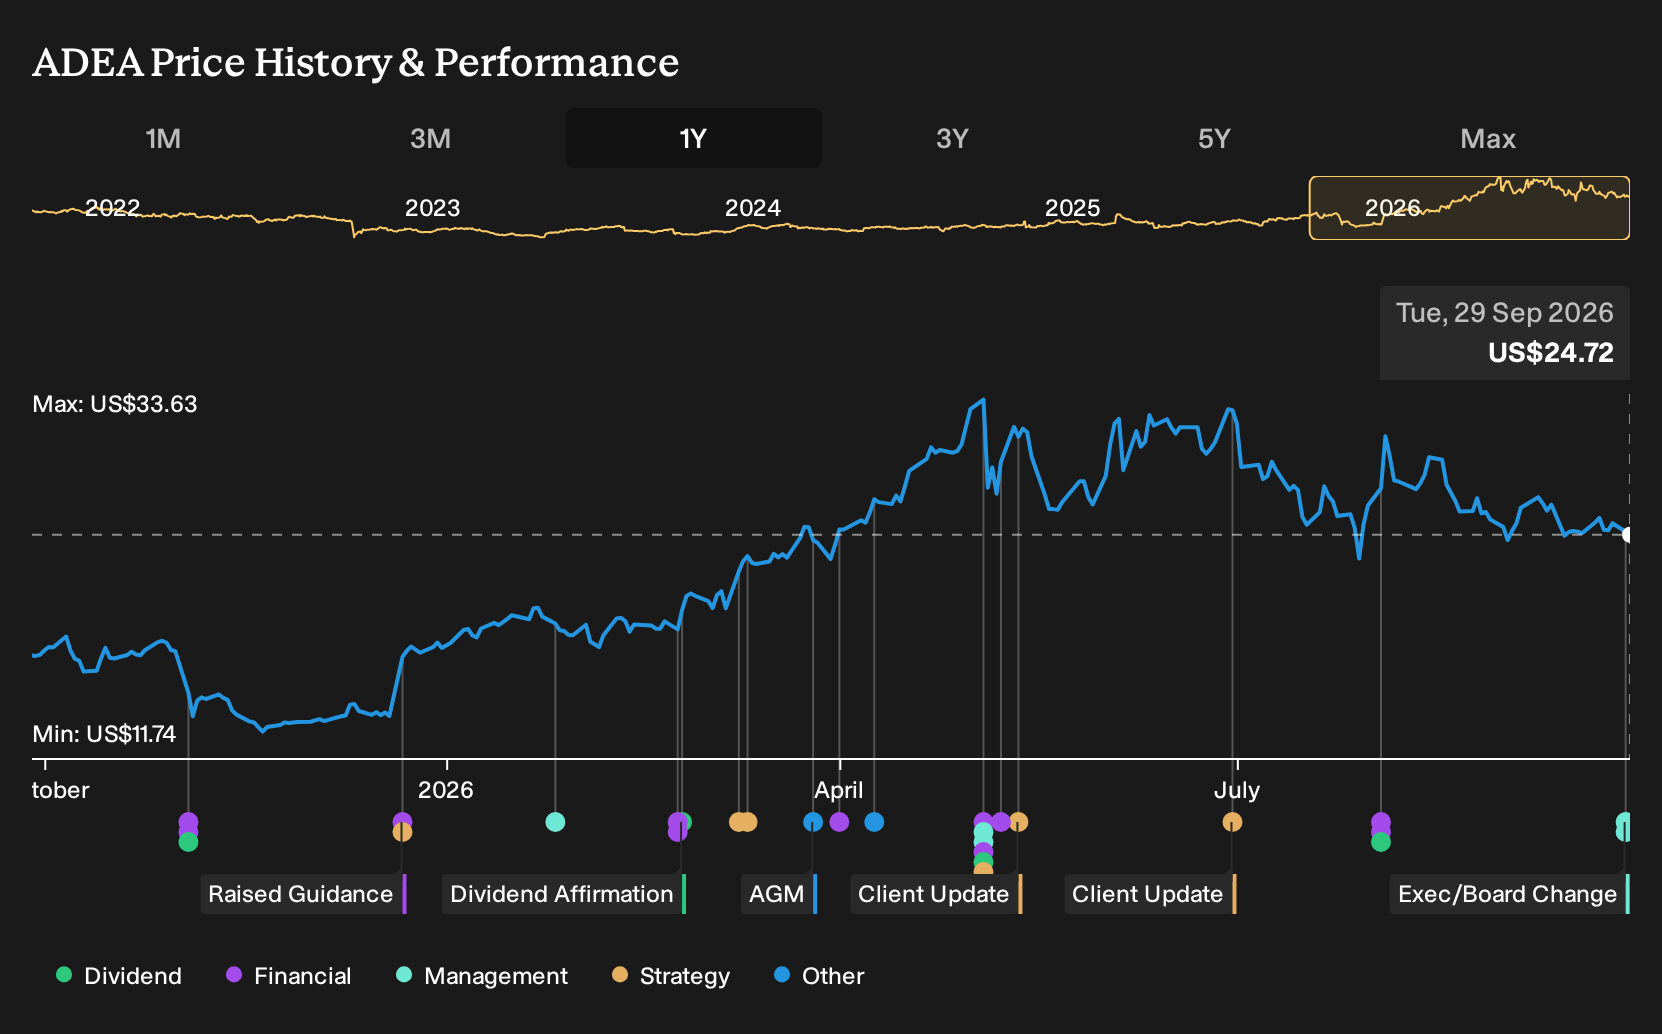
Exploring Other Perspectives
You might focus on execution risk, while the most optimistic analysts fixate on Adeia’s AI data center opportunity. That group was already penciling in 2029 revenue of about $476.8 million and earnings of $111.6 million, with a much higher assumed P/E. The CEO change could prompt those forecasts to shift, in either direction.
Explore 4 other Adeia fair value estimates, including one that suggests potential upside of up to 102% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Adeia research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Adeia. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake. This makes it easy to evaluate Adeia's overall financial health at a glance.
Looking for more Adeia style investment ideas?
If the Adeia story has you thinking about where else recurring cash flows, solid balance sheets and differentiated business models might show up, the Simply Wall St Screener is an efficient way to widen your watchlist without drowning in noise.
- For investors hunting for mispriced quality, start with companies that pass a strict value and fundamentals filter through our 32 high quality undervalued stocks.
- If resilience matters most to you, focus on businesses with stronger balance sheets and cleaner financial profiles highlighted in the list of solid balance sheet and fundamentals (25 results).
- Income focused readers can zero in on steadier yield opportunities by scanning our curated set of 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com