
How Investors May Respond To Unusual Machines Stock As Counter Drone Orders Build
- Unusual Machines reported a sharp Q2 acceleration in activity tied to U.S. enterprise clients and defense programs, while ramping manufacturing capacity and supply chain readiness for projected drone and counter-drone demand into 2027.
- The business is leaning into counter-drone systems and U.S. Department of War programs such as Drone Dominance Gauntlet, positioning its domestically sourced components for a potentially larger role in future drone and anti-drone contracts.
- The focus now turns to how this defense-driven demand for Unusual Machines' counter-drone capabilities could reshuffle the broader investment narrative.
Unusual Machines Investment Narrative Recap
To own Unusual Machines, you need to be comfortable with a story built around U.S. defense and enterprise drone demand, plus a big manufacturing ramp to support it. The latest Q2 acceleration and counter-drone traction reinforce that demand is real, but the near term hinges on execution. The key catalyst is timely conversion of defense programs into concrete orders. The main risk is that these expected programs slip in timing or size while fixed costs from expansion are already in place.
There is also heavy reliance on a small set of U.S. government driven projects, so contract wins and funding decisions matter more here than for a diversified industrial group. Tariff and regulatory shifts sit in the background as a margin wildcard. If you follow Unusual Machines, it is worth watching how management paces capacity additions, supplier qualification, and inventory against the order pipeline so the business does not end up overbuilt for demand that arrives later than expected.
The most relevant announcement for this moment is management’s update on the Drone Dominance Gauntlet and related counter-drone programs. The company reported a sharp Q2 activity pickup from U.S. defense customers and indicated that key phases of the Gauntlet process are nearing final selection, with sizeable drone orders expected to land in late 2026. That ties directly into the current news around ramping capacity and counter-UAS positioning.
For you as a shareholder or potential shareholder, the operational question is whether Unusual Machines can line up factories, suppliers, and quality controls so it can deliver when those contracts come through, without eroding profitability through rush costs or production snags. The main potential catalyst is program awards and volume clarity on Gauntlet and related FPV and counter-UAS efforts. Key risks center on execution and timing, especially given recent share price volatility, significant past dilution, and the fact that the business is still loss making on US$31.9m of revenue and a net loss of US$6.5m.
Unusual Machines' analyst narrative points to forecast revenue of US$227.4m and earnings of US$11.2m by 2029, based on an assumed yearly revenue growth rate of 92.6%. That outlook implies a change in earnings of US$17.7m, from a current net loss of US$6.5m to the projected profit of US$11.2m.
Uncover why Unusual Machines' fair value indicates a 56% potential upside to its current price, which could narrow quickly.
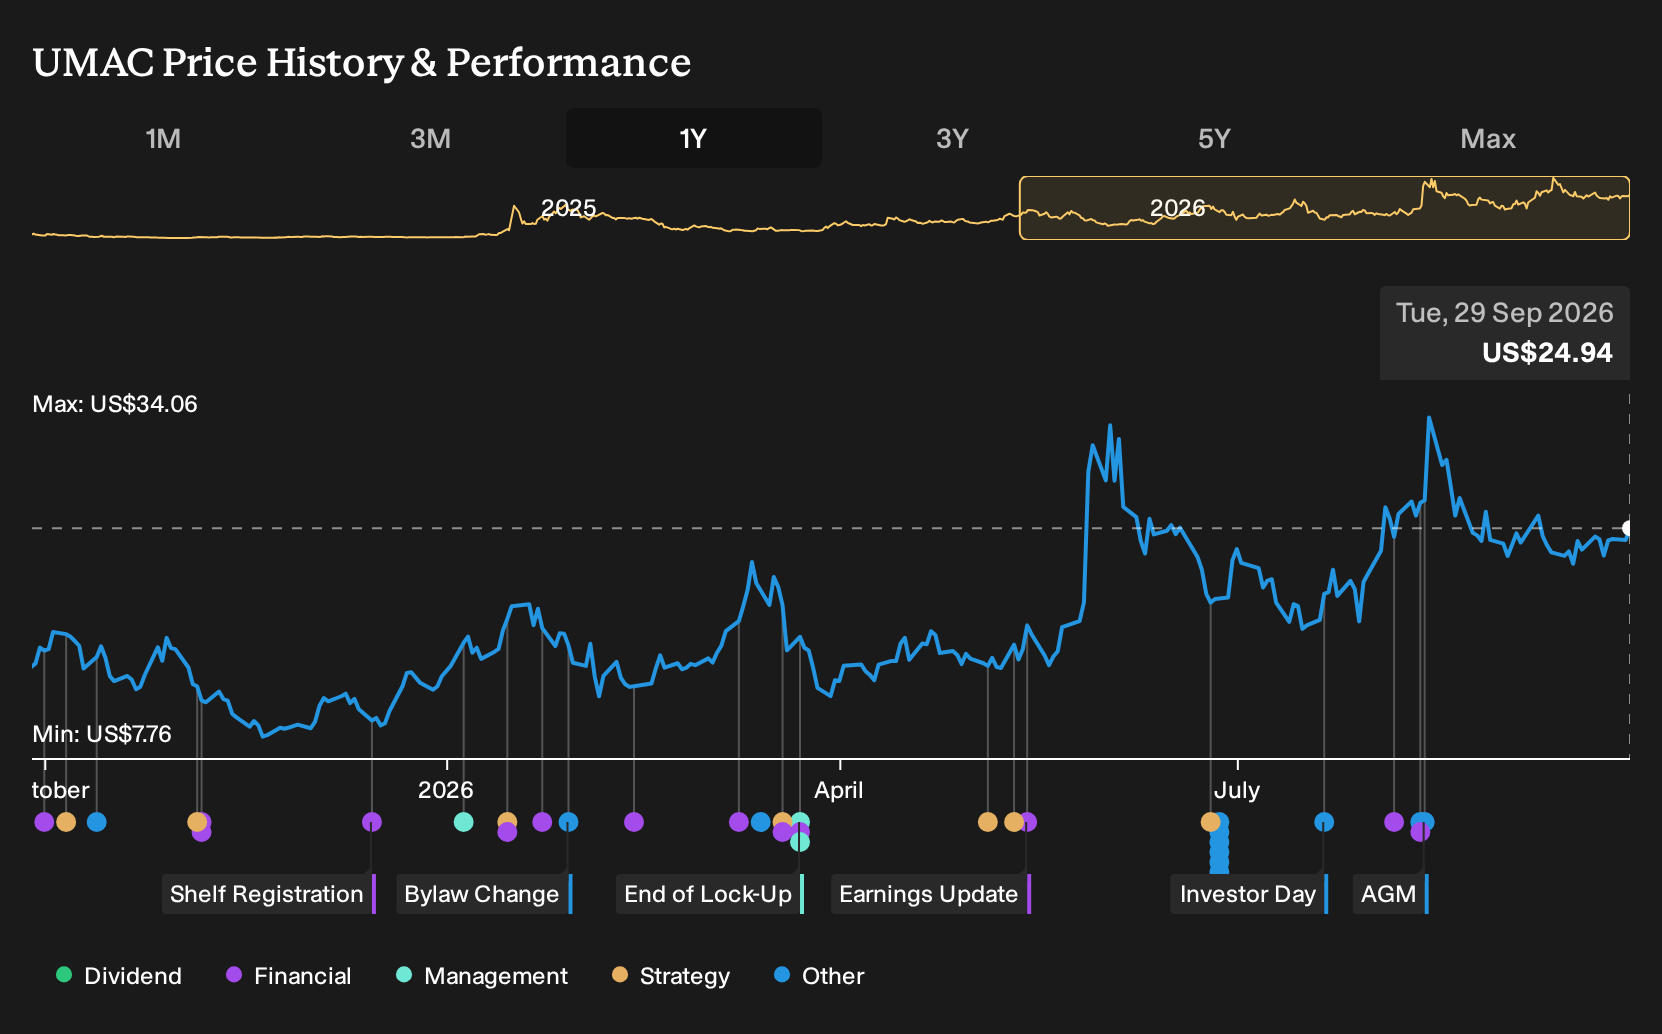
Exploring Other Perspectives
One alternate view on Unusual Machines leans hard into contract timing risk. The most cautious analysts were working off revenue of about US$130.4m and earnings of roughly US$8.7m for 2029 prior to this Q2 and counter drone update. This is far lower than consensus, so you can see how sharply opinions can differ and why fresh news like this may reset expectations.
Explore 6 other Unusual Machines fair value estimates, including one that suggests as much as 94% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own instincts.
- A great starting point for your Unusual Machines research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Unusual Machines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate Unusual Machines' overall financial health at a glance.
Looking For More Ideas Beyond Unusual Machines?
If the Unusual Machines story has you thinking about how to round out your watchlist, it can help to look across other themes using the Simply Wall St Screener. That way you can balance a higher risk defense drone exposure with different types of businesses that have their own strengths.
- For investors who want potential upside with strict financial filters, consider hunting through 17 high quality undiscovered gems that already show strong fundamentals.
- If capital preservation matters most to you right now, focus your search on 32 resilient stocks with low risk scores that aim to keep volatility and balance sheet stress in check.
- When steady income is a priority, filter for 6 dividend fortresses that combine higher yields with checks on payout sustainability and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com