
Coca Cola (KO) Could Be 8% Below Fair Value After North America Leadership Change
Coca-Cola reshapes North America leadership
Coca-Cola (KO) has tapped longtime beverage executive Rob Gehring to lead its North America operating unit starting December 1, 2026. He will succeed interim head John Murphy, who remains president and chief financial officer.
Coca-Cola shares trade at US$86.84 after slipping over the past month, even though the 90-day share price return of 6.8% and year-to-date share price gain of 25.6% sit alongside a 1-year total shareholder return of 34.4% and 5-year total shareholder return of 89.4%. This points to momentum that has been building rather than fading as investors weigh dividend reliability, recent leadership changes in North America and upcoming third quarter results.
Compare Coca-Cola’s momentum and income profile with a handpicked group of defensive consumer staples by scanning our 32 resilient stocks with low risk scores positioned for resilience when sentiment swings.
Coca-Cola’s sharp run over the past year and modest pullback this month put a simple tension in front of you. Is most of the easy upside already in the rear-view mirror, or does the current valuation still leave room ahead?
Most Popular Narrative: 8% Undervalued
Coca-Cola last traded at $86.84, while the most followed narrative pegs fair value closer to $94.70. This suggests the recent share pullback is bumping up against that intrinsic estimate rather than drifting freely.
The ramp-up of U.S. fairlife capacity in 2026 and strong performance in value-added dairy internationally positions Coca-Cola to capture more share of fast-growing, high-margin dairy and functional beverage segments, accelerating both top-line growth and margin expansion.
The global refranchising and asset-light model, coupled with marketing transformation and disciplined cost management, is expanding operating margins and improving earnings stability, with near-term productivity gains expected to be reinvested for future growth.
See why 521 investors see Coca-Cola as 8% undervalued.
Result: Fair Value of $94.70 (UNDERVALUED)
Still, Coca-Cola’s reliance on refranchised bottlers and ongoing health driven scrutiny of sugary drinks could pressure volumes and challenge the current fair value narrative.
Find out about the key risks to this Coca-Cola narrative.
Another View: Coca-Cola Through The P/E Lens
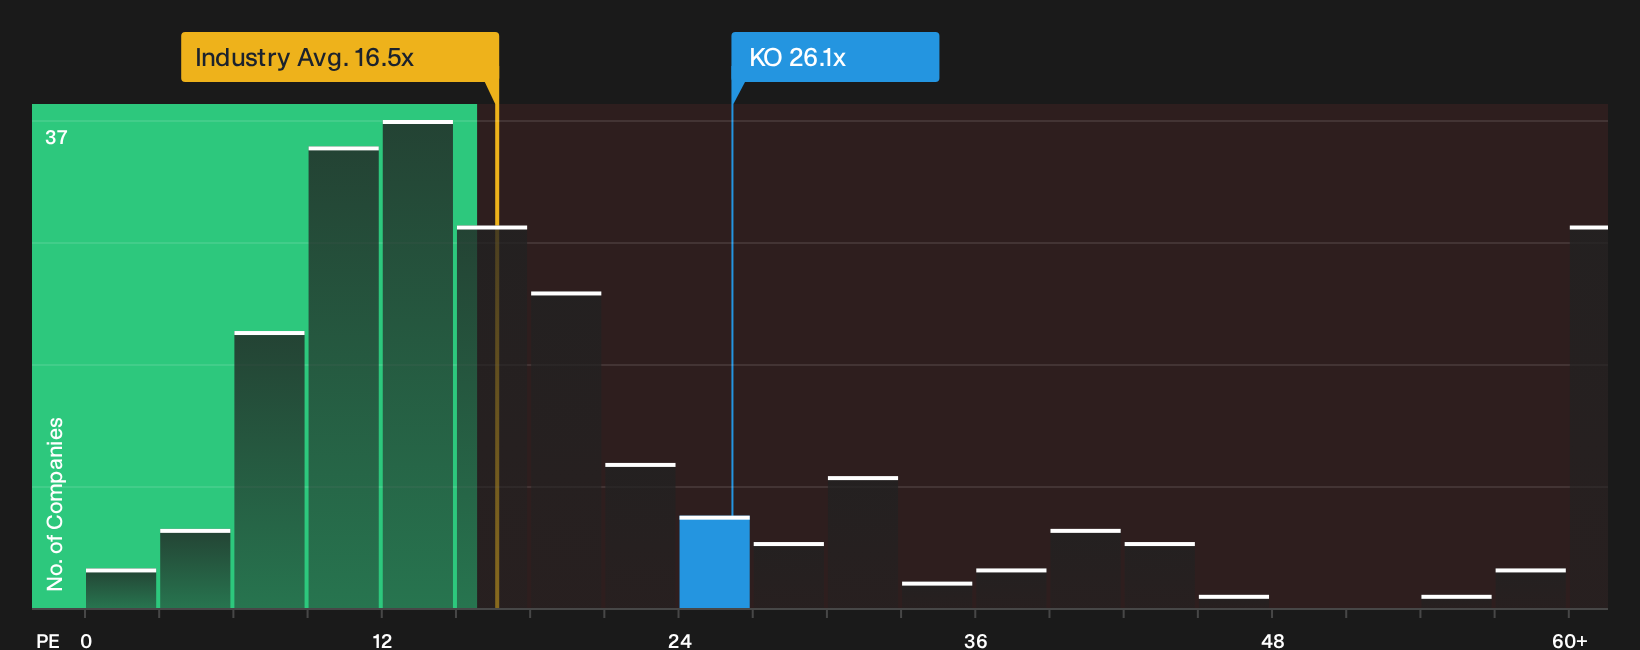
The SWS DCF model points to Coca-Cola trading below an intrinsic value estimate, yet the P/E picture tells a tighter story. At 26.1x earnings, the stock trades above a fair ratio of 24.6x, the global beverage average of 16.5x and a peer mark of 26x, which lifts valuation risk if sentiment cools.
For a closer look at what this earnings multiple might imply for future moves, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Coca-Cola story so far feels mixed to you, that is the point. It is exactly why you should move fast and test the numbers, then weigh both sides through 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Coca-Cola?
If Coca-Cola has sharpened your focus on quality, do not stop here. Use the Simply Wall Street Screener to uncover other opportunities that might fit your plan.
- Target dependable income by scanning for companies in the 6 dividend fortresses that could complement Coca-Cola in a long term portfolio.
- Unearth potential value by reviewing the 32 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them yet.
- Strengthen your downside protection by filtering for businesses in the list of solid balance sheet and fundamentals (25 results) before market sentiment shifts again.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com