
WiseTech Global (ASX:WTC) Shares May Be About Right Despite Migration News
WiseTech Global has seen its share price come under heavy pressure over the past year, which puts the focus on whether the current A$32.46 level still lines up with the earnings behind the story. With much of the investment case tied to profit generation from its software platform, the key issue is how much income the present multiple asks investors to pay for.
- WiseTech Global shares have fallen 64.1% over the past year, which puts more weight on the question of what investors are now paying for each dollar of earnings.
- ShipDNA's Safe Passage program, built around WiseTech Global's Transtream product, may support expectations for how reliably the business can turn its logistics software into profit and cash flow.
- There is a second opinion on WiseTech Global worth weighing. See what analysts think WiseTech Global's shares could be worth.
The issue now is whether WiseTech Global's current share price is supported by the earnings it generates today and by what the market expects those earnings to do next.
If you want to test the same earnings question that WiseTech Global now faces against a wider set of opportunities, it can help to compare it with 5 high quality undervalued stocks.
Is WiseTech Global Fairly Priced on Earnings?
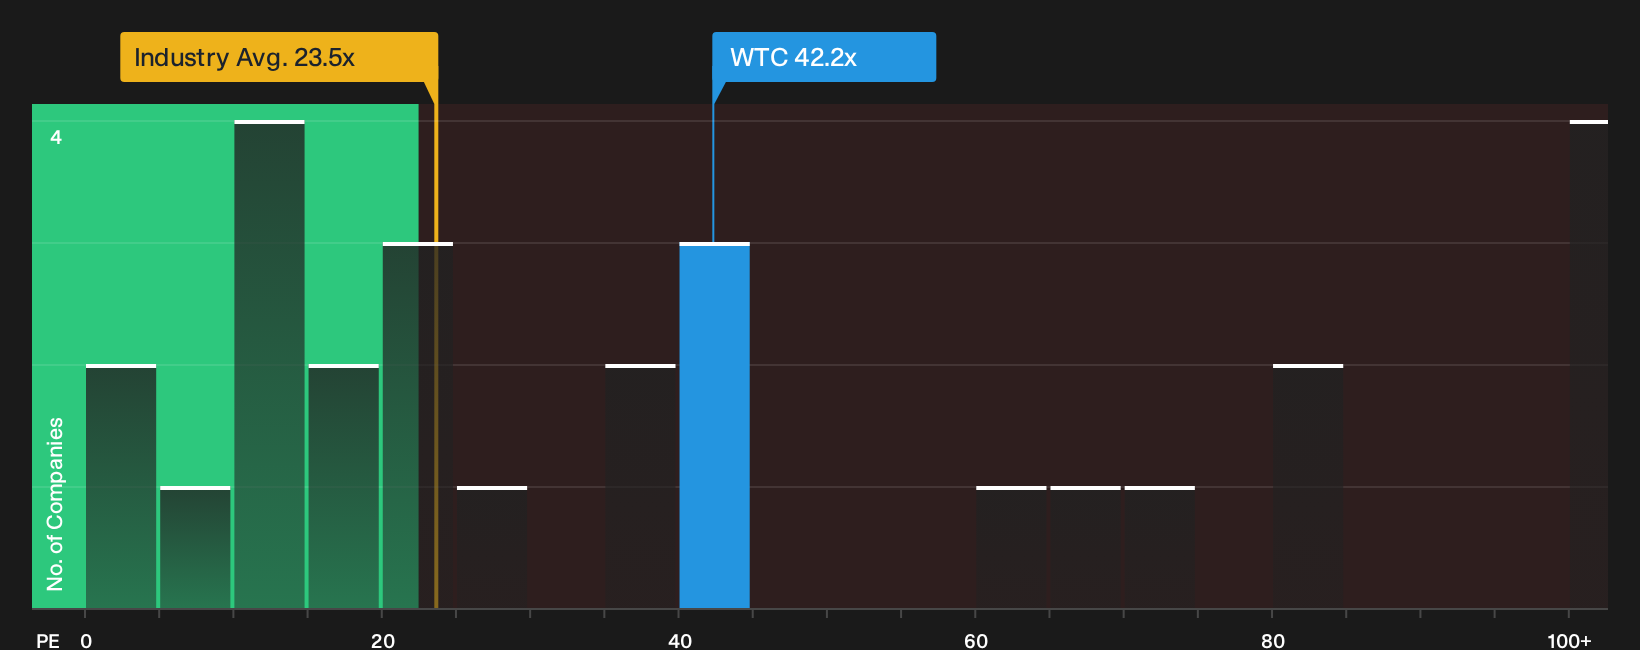
The P/E ratio suits WiseTech Global because earnings still sit at the centre of how investors frame the story. At roughly 42.2x, WiseTech Global trades close to both its software peer group on about 43.2x and the Fair Ratio that reflects its own mix of growth prospects, profitability profile, size and risk. Against a broader software industry average of 23.5x, that is a materially higher earnings multiple, which indicates the market is prepared to pay a premium for each dollar of profit.
Because ShipDNA's Safe Passage program underscores customer commitment to WiseTech Global's Transtream platform, sentiment around the durability of earnings may be playing a role in keeping the P/E around that Fair Ratio anchor rather than pushing it to a clear discount or steep premium. For you as a shareholder or potential buyer, the current multiple suggests the price broadly lines up with what this framework implies for WiseTech Global given its business characteristics. The key question is whether you are comfortable paying that kind of earnings tag for this type of software exposure. Explore the numbers behind WiseTech Global's P/E valuation.
The WiseTech Global Narrative: What Would Justify Today's Price?
WiseTech Global's valuation puzzle only really comes into focus once you spell out the future paths that might justify a meaningfully higher or lower outcome than today's price, and that is where Simply Wall St Narratives on the Community page come in. Each one links its number to a clear view of how WiseTech Global's growth, margins and risk profile might evolve, giving you a reference point you can revisit whenever fresh information arrives.
One of the top community narratives on WiseTech Global: 51% undervalued
"Adoption of unified, AI-driven SaaS solutions and strategic acquisitions are driving deeper market penetration, new revenue streams, and higher customer retention..."
Discover why this Narrative puts WiseTech Global at 51% undervalued.
One more WiseTech Global piece that could change your view
Everything so far has focused on what WiseTech Global looks like today, but professional coverage also sketches where this business might be a few years from now. This gives you another lens to compare with the current share price. Explore where analysts expect WiseTech Global to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com