
Is Option Care Health (OPCH) A Bargain As Home Infusion Growth Comes Back Into Focus?
Option Care Health (OPCH) is back in focus after fresh commentary comparing it with BrightSpring Health Services, highlighting how both are tied to the ongoing shift of complex care into lower cost home and alternate treatment settings.
Recent trading has been softer, with a 30 day share price return down 4.6% and year to date share price return down 29.3%. The 1 year total shareholder return is lower by 17.8%, suggesting momentum has faded even as investors reassess Option Care Health against peers like BrightSpring.
Scan beyond Option Care Health and compare it with other home-care and defensive healthcare operators by reviewing our curated list of 32 resilient stocks with low risk scores that have kept volatility in check.
Option Care Health now trades well below recent levels, even as its business remains tied to the same long term home-infusion shift. Is most of the stock reset already done, or is the remaining potential upside still ahead?
Most Popular Narrative: 20.2% Undervalued
Measured against the most followed fair value estimate of $28.58, Option Care Health at a last close of $22.81 screens as materially cheaper, while the narrative leans heavily on long run specialty infusion demand and payer relationships.
Deepening partnerships with national payers and pharmaceutical manufacturers, supported by system wide shifts to lower cost, value based care and payers' focus on medical loss ratios, are enhancing contract wins and broadening patient access, supporting revenue growth and pricing power.
See why 3 investors see Option Care Health as 20% undervalued.
Result: Fair Value of $28.58 (UNDERVALUED)
Still, the narrative around Option Care Health can be knocked off course if the therapy mix shifts toward lower margin drugs or if payer pushback tightens reimbursement terms.
Find out about the key risks to this Option Care Health narrative.
Another View on Option Care Health Valuation
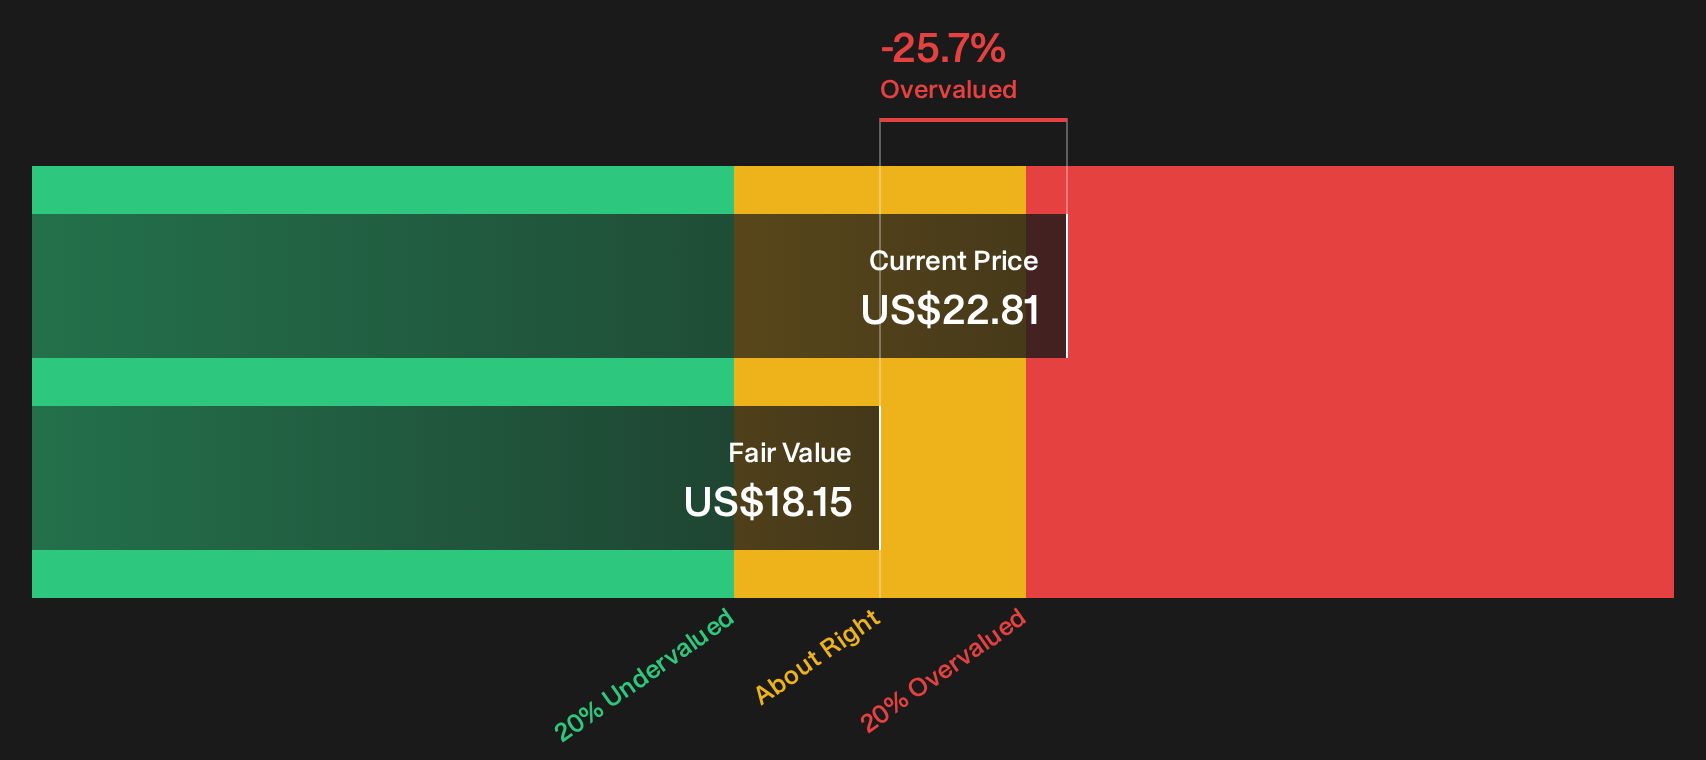
The SWS DCF model paints a very different picture for Option Care Health. On this view, the shares at $22.81 sit above an estimated future cash flow value of $18.15, which screens as overvalued rather than cheap. If cash generation matters more than earnings multiples, how much weight should this carry in your thesis?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Option Care Health for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Option Care Health is clearly mixed, with both concerns and bright spots on display. Move quickly. Review the full data set and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Option Care Health?
If Option Care Health has your attention, do not stop here. Use the screener to surface fresh ideas that fit your own risk, income, and value preferences.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) for companies that aim to keep financial risk contained.
- Hunt for potential value opportunities by reviewing the 32 high quality undervalued stocks that currently trade below their assessed worth on key measures.
- Build a cash flow focused watchlist by zeroing in on income opportunities using the 6 dividend fortresses that aim to pair yield with stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com