
Vicor (VICR) Looks Repriced As VPD Licensing Deal Lifts The Valuation Narrative
Vicor (VICR) is back in focus after granting a non-exclusive license that allows a new OEM to source Vertical Power Delivery modules for high-performance AI and networking hardware from multiple suppliers.
Recent trading reflects that story. Vicor’s share price is now at $290.68, with a 1 month share price return of 54.88% and a year to date share price return of 148.74%, while the 1 year total shareholder return is very large at about 5x. Momentum has accelerated further in recent weeks as the VPD licensing deal and upgraded earnings expectations have shifted how investors are pricing future opportunity and risk.
Spot emerging AI infrastructure stories that rhyme with Vicor's VPD momentum by scanning our hand picked 89 AI infrastructure stocks for potential next movers in the space.Vicor now trades well below the average analyst target, even after this sharp move, while intrinsic value estimates point in a very different direction. Where does a reasonable fair value range ultimately land for this run up?
Most Popular Narrative: 25% Undervalued
Vicor's most followed narrative pegs fair value at $386.25, well above the last close at $290.68. This puts the recent run against a still sizable implied upside in that framework.
The analysts have a consensus price target of $386.25 for Vicor based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $450.0, and the most bearish reporting a price target of just $320.0.
See why 27 investors see Vicor as 25% undervalued.
Result: Fair Value of $386.25 (UNDERVALUED)
Still, the bullish Vicor story depends on orders and licensing holding up. Any prolonged demand softness or weaker settlement activity could quickly challenge that fair value case.
Find out about the key risks to this Vicor narrative.
Another View on Vicor Valuation
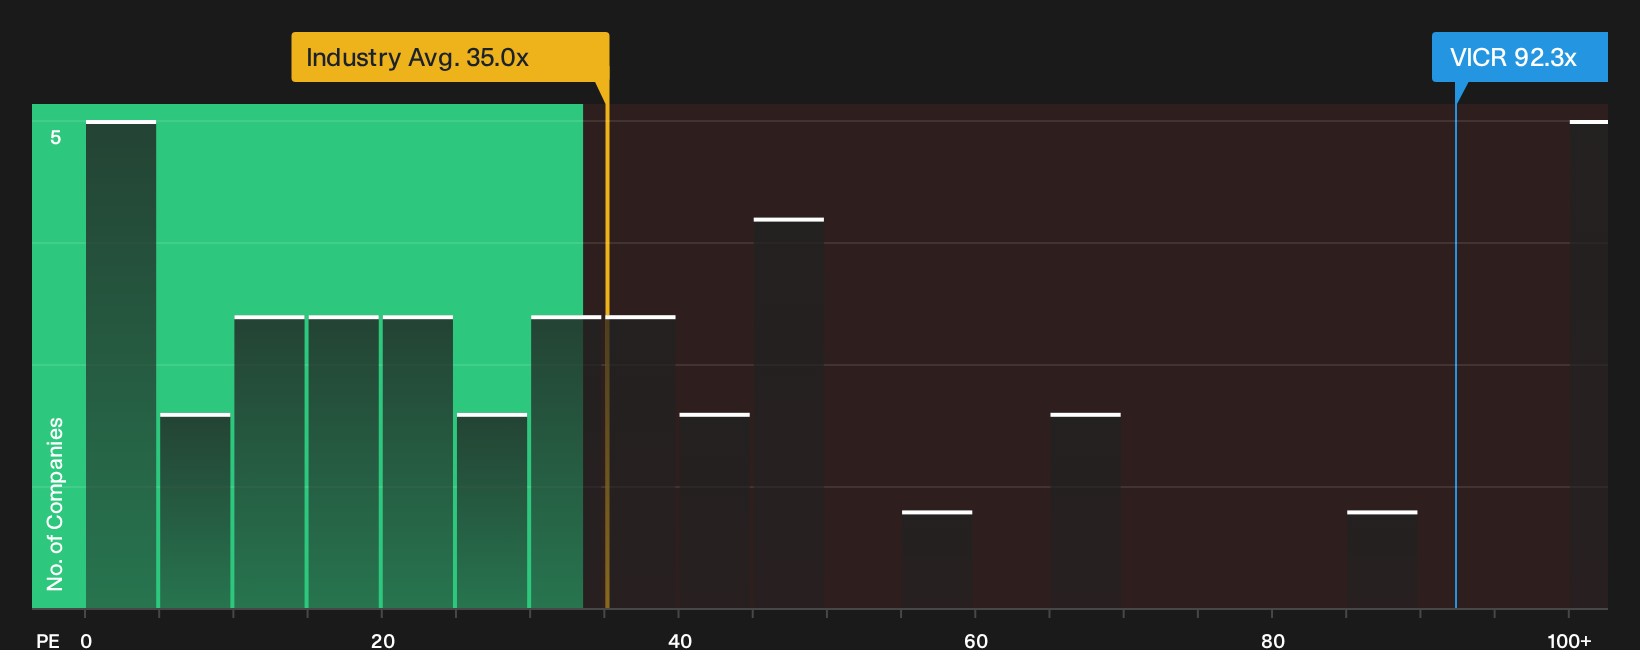
Vicor might look inexpensive compared to the $386.25 fair value narrative, but its current P/E of 92.3x is well above the US Electrical industry at 35x and the peer average at 30.1x. It is also significantly higher than the 72.2x fair ratio. Is this investor enthusiasm or valuation excess?
See what the numbers indicate about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed feelings on Vicor after this surge. Check the numbers, weigh both the upside story and the concerns, and then ground your stance in the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Vicor?
Do not stop with Vicor. Broaden your watchlist now, because the next move often starts quietly in corners of the market most investors ignore.
- Target companies that combine quality and a potential price gap by scanning our hand picked 32 high quality undervalued stocks before the crowd catches on.
- Protect your downside first and let upside surprise you by checking a curated 32 resilient stocks with low risk scores that filters for resilience when conditions turn.
- Hunt for tomorrow's quiet leaders by reviewing a focused 17 high quality undiscovered gems that filters for strong fundamentals before they hit the spotlight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com