
Has Bandwidth (BAND) Run Ahead Of Its Valuation Following Its Recent Rally?
Bandwidth (BAND) has drawn fresh attention after recent trading left the stock with a month return above 25%. This has sharpened investor focus on how its communications platform-as-a-service model lines up with that repricing.
The recent surge sits on top of a much bigger move in Bandwidth, with a year-to-date share price return of 326.93% and a 1-year total shareholder return of 279.67% that point to strong momentum, even though the 90-day share price return declined 1.44% and the 5-year total shareholder return fell 25.45%.
Scan how Bandwidth's sharp move compares with other fast repricing opportunities by reviewing our hand picked list of 32 high quality undervalued stocks.
Bulls see Bandwidth’s sharp rerating as proof the business is catching up to its potential, while bears point to a bruising 5 year record. Which story do the current valuation markers support?
Most Popular Narrative: 10% Undervalued
Against a last close of $60.71, the most followed narrative pegs Bandwidth's fair value at $67.25, implying modest undervaluation and putting the focus squarely on whether its AI and cloud tools can sustain current expectations.
Accelerating enterprise adoption of AI-powered voice applications, driven by Bandwidth's Maestro platform and integrations, is already delivering a 3x-4x uplift in revenue per call for AI-enabled use cases, and is expected to further increase platform usage, ARPU, and gross margin as more enterprises embed AI into customer workflows.
See why 10 investors see Bandwidth as 10% undervalued.
The narrative builds this fair value using a 7.24% discount rate and a set of explicit forecasts that investors can weigh against their own expectations. In that framework, analysts model revenue growth of about 11.2% a year, net profit margins rising from 0.3% to 6.4%, and earnings reaching $72.9 million by around 2029, compared with $2.3 million today. To get to the $67.25 figure, the story also assumes Bandwidth would trade on a P/E of 44.6x those future earnings, which sits well above the 20.7x level quoted for the wider US Telecom industry in the same narrative.
Price targets inside that storyline are not uniform, which matters if you are using them as a reference point for your own work. The most optimistic analyst points to $86.00, while the most cautious lands at $38.00, creating a wide range around the $67.25 central case. With the current share price closer to the lower end of that spectrum, the narrative frames roughly 10% upside to its fair value estimate and about one third upside to the central analyst target mentioned in the text, leaving room for different views about how Bandwidth’s Maestro platform, AI use cases, and enterprise contracts play out over time.
Result: Fair Value of $67.25 (UNDERVALUED)
Still, the Bandwidth story can unravel if AI adoption slows and Maestro-driven use cases stall, or if a concentrated enterprise customer base starts to churn.
Find out about the key risks to this Bandwidth narrative.
Another View on Bandwidth’s Valuation
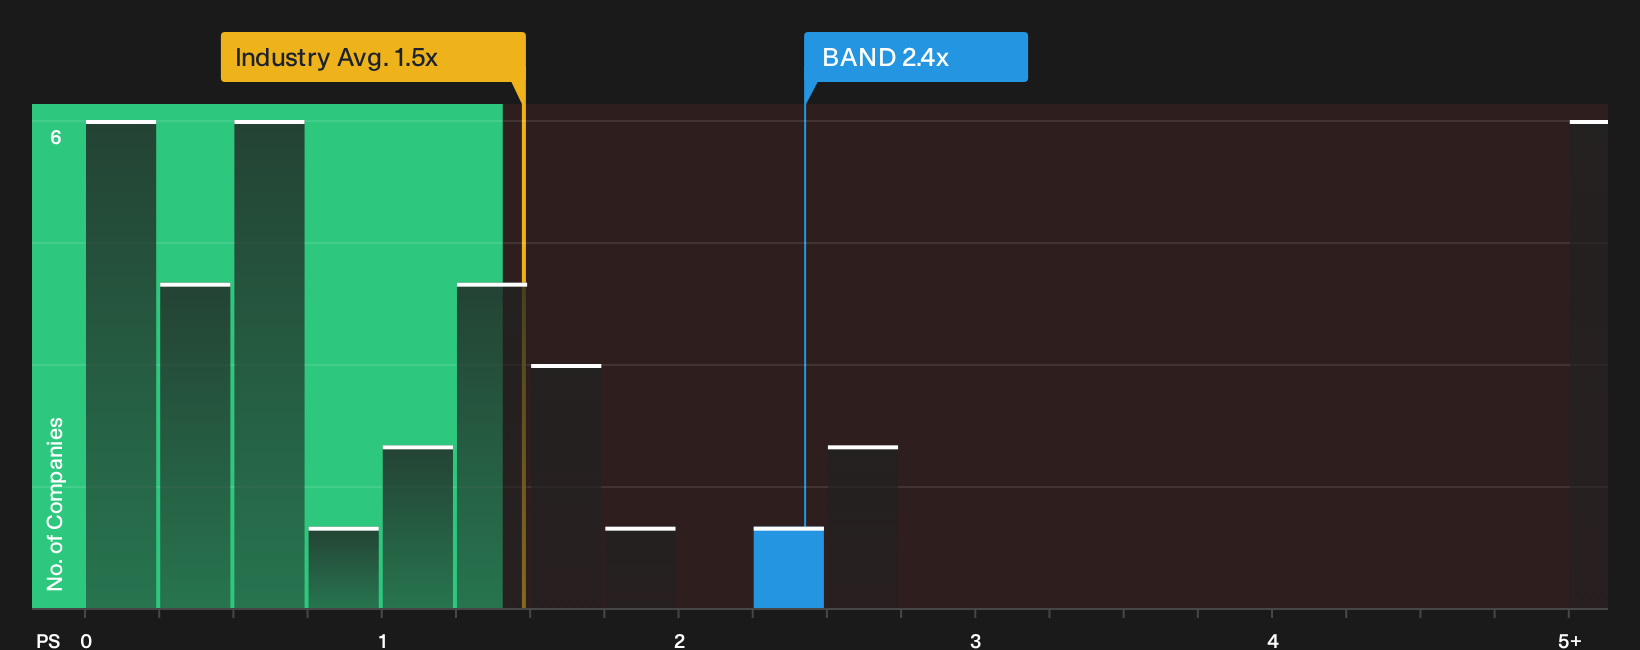
That 10% undervalued narrative meets a very different signal when you look at simple pricing yardsticks. On a P/S of 2.4x, Bandwidth trades well above the US Telecom group at 1.4x, not only richer than peers at 2.2x but also above an estimated fair ratio of 1.3x. Is the premium a sign of quality or just valuation risk building up?
Before leaning too heavily on any one ratio, it is worth stress testing how those assumptions hold up when the story changes or sentiment cools. This is exactly what the detailed valuation breakdown is designed to do, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With Bandwidth’s mixed history of sharp gains and past drawdowns, sentiment is clearly split. This is exactly why you should press into the numbers yourself and move quickly to frame your own stance using the full view of 3 key rewards and 3 important warning signs.
Looking for more Bandwidth-sized investment ideas?
If you stop your search with Bandwidth, you risk missing other opportunities that fit your style just as well, or even better, on Simply Wall Street.
- Target resilient cash generators that can handle stress by scanning a carefully filtered list of solid balance sheet and fundamentals (25 results) built around balance sheet strength and solid fundamentals.
- Hunt for mispriced opportunities where quality lines up with valuation by running a focused screen across 17 high quality undiscovered gems before other investors catch on.
- Prioritise sleep-at-night holdings by filtering for 32 resilient stocks with low risk scores so you keep potential shocks in check while still working toward your financial goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com