
Centerra Gold (TSX:CG) Has A Fresh Update, But Why Is It Drawing Attention?
BQE Water’s restart of its selenium removal plant at the Kemess Project, in partnership with Centerra Gold (TSX:CG), gives investors fresh information on environmental performance and long term project readiness.
Centerra Gold’s share price has pulled back slightly in the last week, yet the 90 day share price return of 32.16% and year to date gain of 59.78% sit alongside a 1 year total shareholder return of 100.33% and a 3 year total shareholder return above 4x, which points to strong momentum despite near term softness.
Scan beyond Centerra Gold and see how other producers with strong operations and environmental credentials stack up in our hand picked list of 36 elite gold producer stocks.
After a 100% 1 year total return and a recent pullback, Centerra Gold now trades only about 7% below the average analyst target. So where does a reasonable fair value range actually sit in that gap?
Most Popular Narrative: 28% Undervalued
Centerra Gold’s most followed valuation storyline puts fair value at CA$43.01, well above the last close of CA$31.03. This leaves a sizeable gap that bullish investors are trying to explain through project growth, margins, and capital discipline.
Analyst consensus expects extension of Mount Milligan's mine life and increased throughput to modestly impact future revenues. However, this likely understates the upside, as tailings expansion, continued high-grade discoveries, and ongoing process optimization could result in production levels and mine life significantly exceeding current projections, greatly boosting long-term revenues and free cash flow.
See why 3 investors see Centerra Gold as 28% undervalued.
Result: Fair Value of CA$43.01 (UNDERVALUED)
Still, that upside story for Centerra Gold leans heavily on supportive gold prices and smooth permitting, and setbacks on either front could quickly weaken the bullish case.
Find out about the key risks to this Centerra Gold narrative.
Another View on Centerra Gold’s Valuation
There is a very different message coming from the SWS DCF model. At a share price of about CA$31.03, Centerra Gold is shown as trading above an estimated future cash flow value of CA$13.28, which implies the stock screens as expensive on that cash flow approach.
For readers who lean on cash flow models rather than earnings based narratives, this gap raises a simple question: Is the market correctly pricing long term project risk, or is the DCF framework being too strict for a multi mine producer with moving parts?
Look into how the SWS DCF model arrives at its fair value.
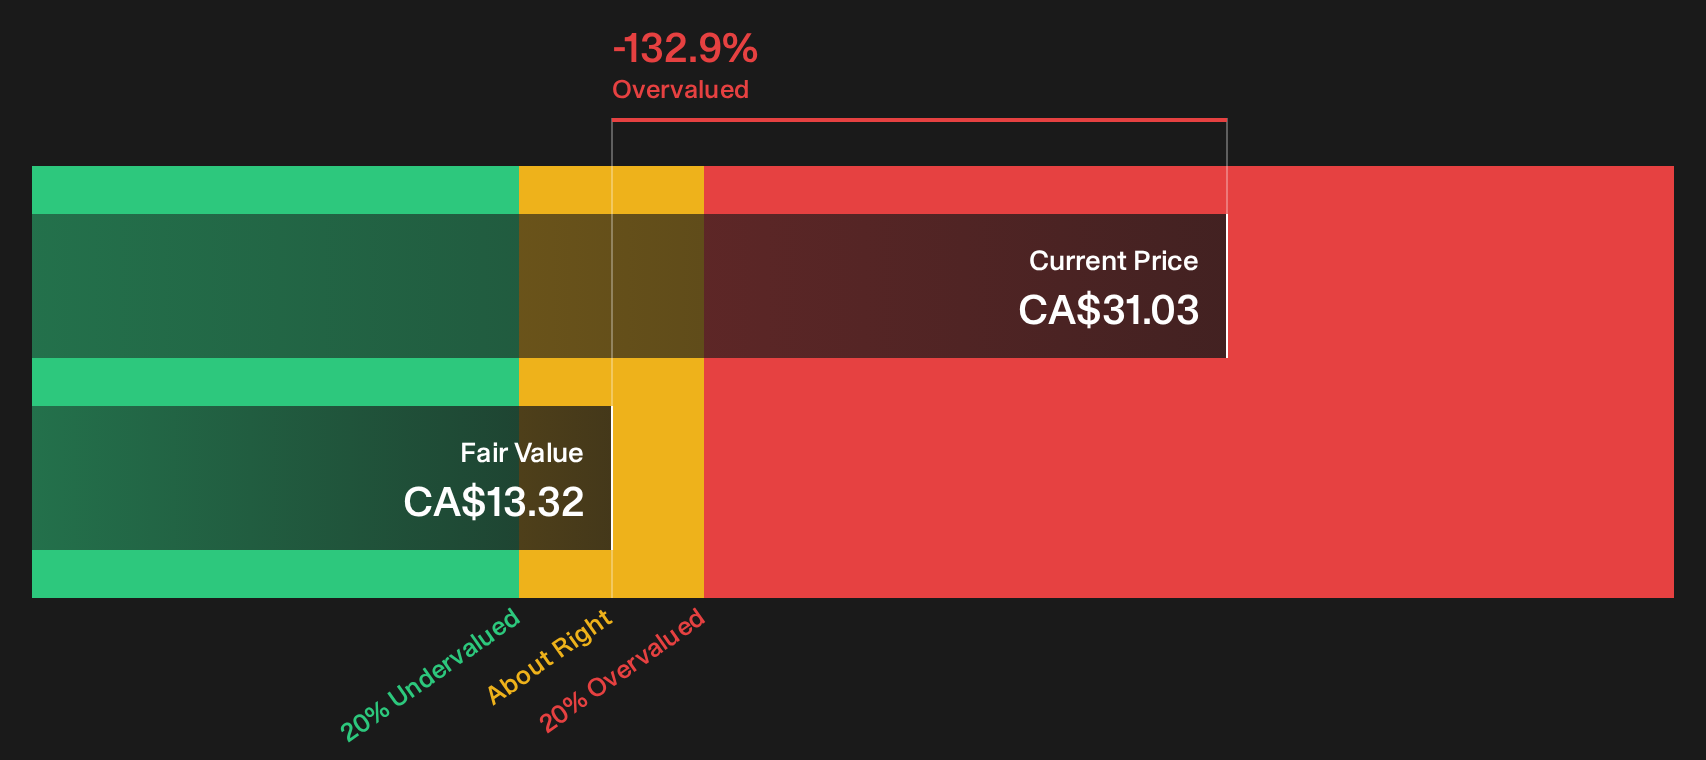
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Centerra Gold for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Centerra Gold’s value and risk profile can feel messy, so move quickly, test the numbers yourself, and weigh the 4 key rewards and 2 important warning signs.
Looking for more Centerra Gold sized ideas?
If you stop with Centerra Gold, you risk missing other opportunities that could better match your goals, risk comfort, and income needs.
- Target future upside with disciplined valuation by scanning our curated pool of companies that look mispriced on fundamentals through the 6 high quality undervalued stocks.
- Build a steadier income stream by reviewing dependable payers with robust yields and fundamentals using the 1 dividend fortresses.
- Reduce downside surprises by focusing on companies with healthier financial footing via the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com