
Silvercorp Metals (SVM) Is Up 75%. The Hard Part Was Not Believing The Bull Case
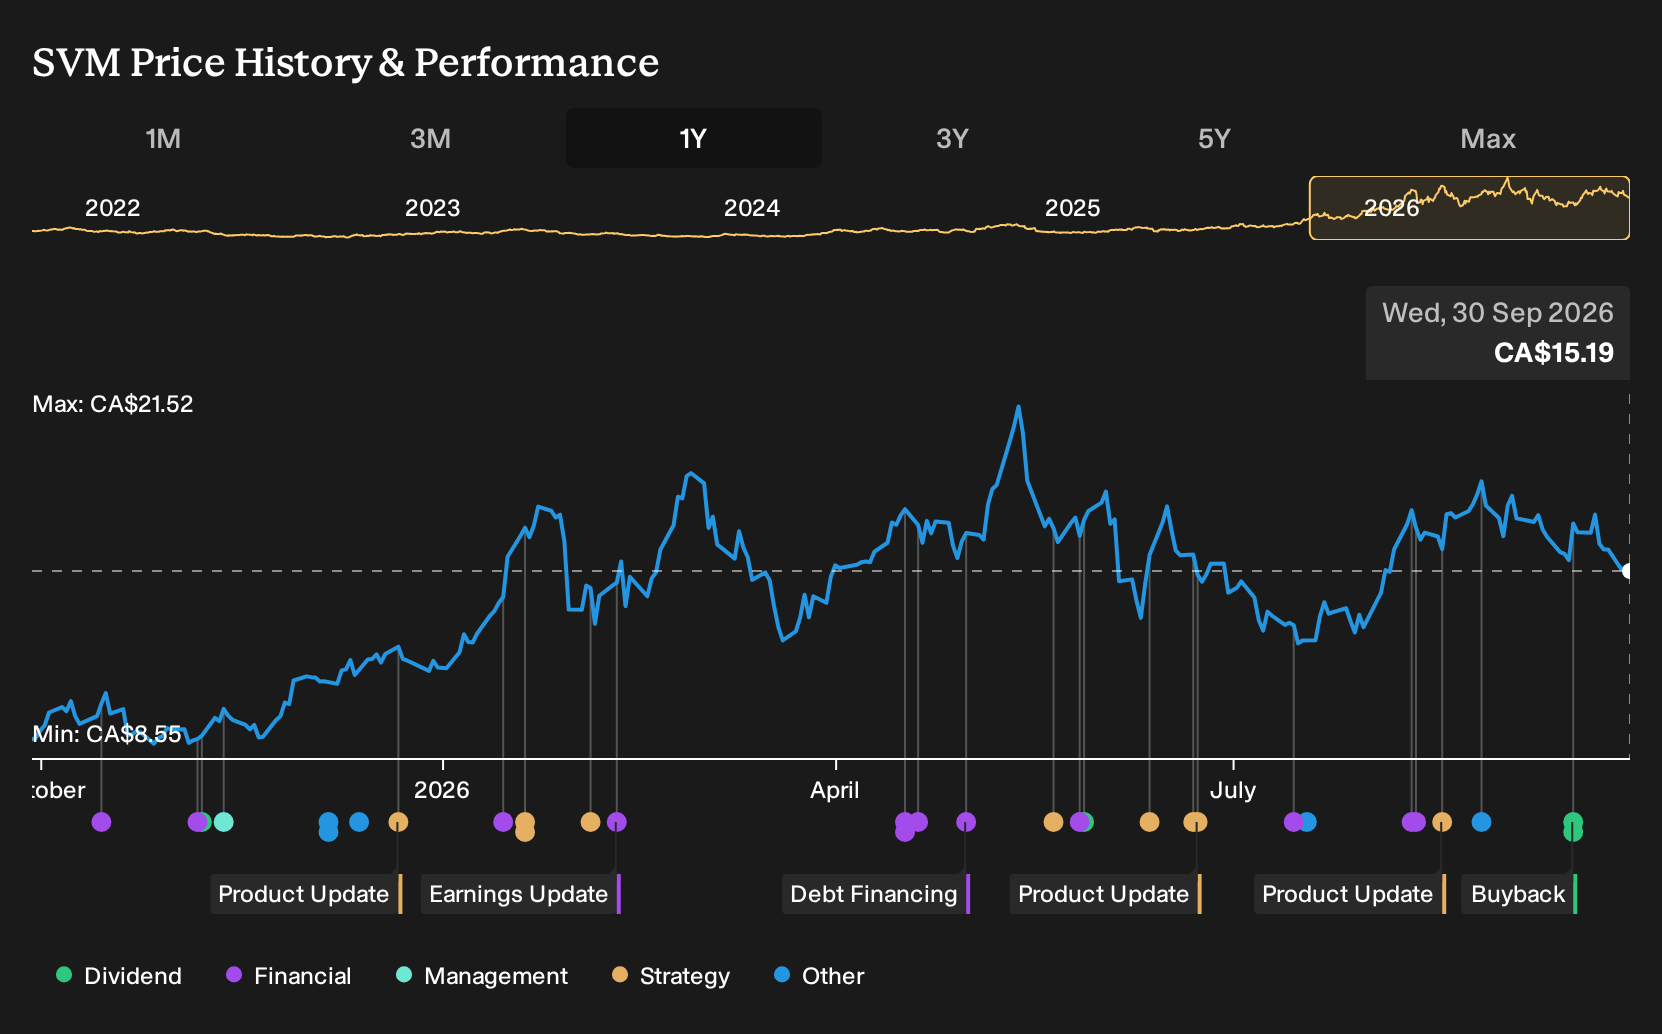
If Silvercorp Metals was sitting on your watchlist instead of in your account, the past year might feel like an expensive lesson. Holding Silvercorp Metals over the past year would have returned 75.3%, including dividends. That outcome sits between a bullish model at $100/oz silver and a more cautious China focused view. If you roll the clock back to 2025, what clues in those competing profit margin and P/E assumptions could have flagged this as more than just another high risk miner?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Silvercorp Metals is not the only name tied to this theme. Zero in on 10 top silver producer stocks and compare how each one is priced.
The Case For, And Against, Silvercorp Metals Back Then
The shares cost CA$8.71 at the start of the period, and Silvercorp Metals sat between two very different stories about where it could go next. Both were built from real numbers and specific assumptions, not just vague optimism or worry.
The bullish narrative put Fair Value at CA$28.58. It relied on a silver price assumption of $100/oz, revenue growth assumptions of 91.6%, and a future P/E of 12.2x over five years.
The cautious view pointed to a Fair Value of CA$7.47. It focused on concentration in China, higher production and compliance costs, and the risk that ESG and regulatory pressure could weigh on long-term profitability.
What The Silvercorp Metals Results Put To The Test
Record Q1 2027 numbers for Silvercorp Metals, with revenue of US$138.7m and net income of US$59.4m, plus a net margin rising to 42.8%, leaned toward the bullish case on profitability and capital access. Safety driven production curbs in China and heavy Kyrgyzstan and Ecuador spending pulled the story back toward the cautious view. Overall, the evidence cut both ways.
The whole episode turned on whether high margins and funding outweighed country and project risk. For the next stock on your list, check whether margin gains and fresh financing sit alongside concentration in one jurisdiction or a single large build out.
What Silvercorp Metals Buyers Are Paying For Now
Silvercorp Metals now trades at CA$15.35, after a 75.3% gain over the past year. The selected Narrative places its Fair Value above that level, based on a view that balances cash generation with project and jurisdiction complexity.
The argument focuses on how El Domo, Chinese assets and ESG pressures interact. The key test is whether future earnings can support both higher production and the extra cost of tighter regulation and new-country build outs.
"While Silvercorp Metals has reported record revenues and strong cash flows driven by expanded production capacity and higher realized silver prices, its operations focus in China exposes it to geopolitical and regulatory risks that may affect the stability of future earnings. Alongside investments in diversification and resource growth such as the El Domo and Condor projects in Ecuador, evolving global decarbonization initiatives may influence how capital for mining projects is priced and accessed over the long term."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 38% below our estimate - accelerates higher grade ore feed and underground expansions to lift output.
- Company 2 - 22% below our estimate - ramps drilling and mine development to pursue greater silver volumes and sales.
- Company 3 - 49% below our estimate - opens additional premium stores while scaling a faster data driven online channel.
That is three of the list. See every one of the 6 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com