
Is Real World Study Launch Altering The Investment Case For Cytokinetics (CYTK)?
- Cytokinetics has begun ASPEN-HCM, a prospective multicenter observational study tracking the real world safety and effectiveness of MYQORZO in adults with symptomatic obstructive hypertrophic cardiomyopathy.
- The focus on real world evidence links MYQORZO’s clinical profile to everyday practice, with potential implications for treatment patterns and health system economics in obstructive hypertrophic cardiomyopathy.
- The focus now turns to how Cytokinetics' investment narrative could be reshaped by real world evidence generation through the ASPEN-HCM study.
Scan how Cytokinetics fits into the wider cardiology and biotech story by reviewing a curated set of 17 high quality undiscovered gems that are still flying under most investors' radar.
Cytokinetics Investment Narrative Recap
To own Cytokinetics, you need to believe that MYQORZO and the broader cardiac portfolio can turn a small commercial base into a more substantial cardiology franchise, despite current losses and negative equity. The near term focus sits on execution in oHCM, reimbursement traction, and keeping funding smooth while the pipeline stays expensive.
The ASPEN-HCM study looks more like a supporting piece than a swing factor for the next catalyst. It helps build a real world story around MYQORZO but does not change the binary nature of remaining regulatory and reimbursement decisions or the key risk that uptake and pricing could lag while operating losses remain heavy.
With no fresh corporate announcements beyond ASPEN-HCM, the most relevant reference point is still the broader plan to commercialize aficamten and related cardiac myosin inhibitors across HCM and heart failure. That blueprint underpins expectations for revenue growth, even as analysts see Cytokinetics remaining unprofitable over the next three years.
ASPEN-HCM plugs directly into that plan. Strong real world data could help Cytokinetics argue for broader adoption and value based discussions with payers, which matters if generics and rival myosin inhibitors pressure share and pricing. If outcomes, safety and economic signals in routine practice look weaker than trial data, that would work against those same catalysts.
Cytokinetics' narrative projects US$1.0b revenue and US$178.9 million earnings by 2029. This assumes revenue growth of 114.3% per year and an earnings swing of about US$1.0b from a current loss of US$829.6 million to the forecast profit.
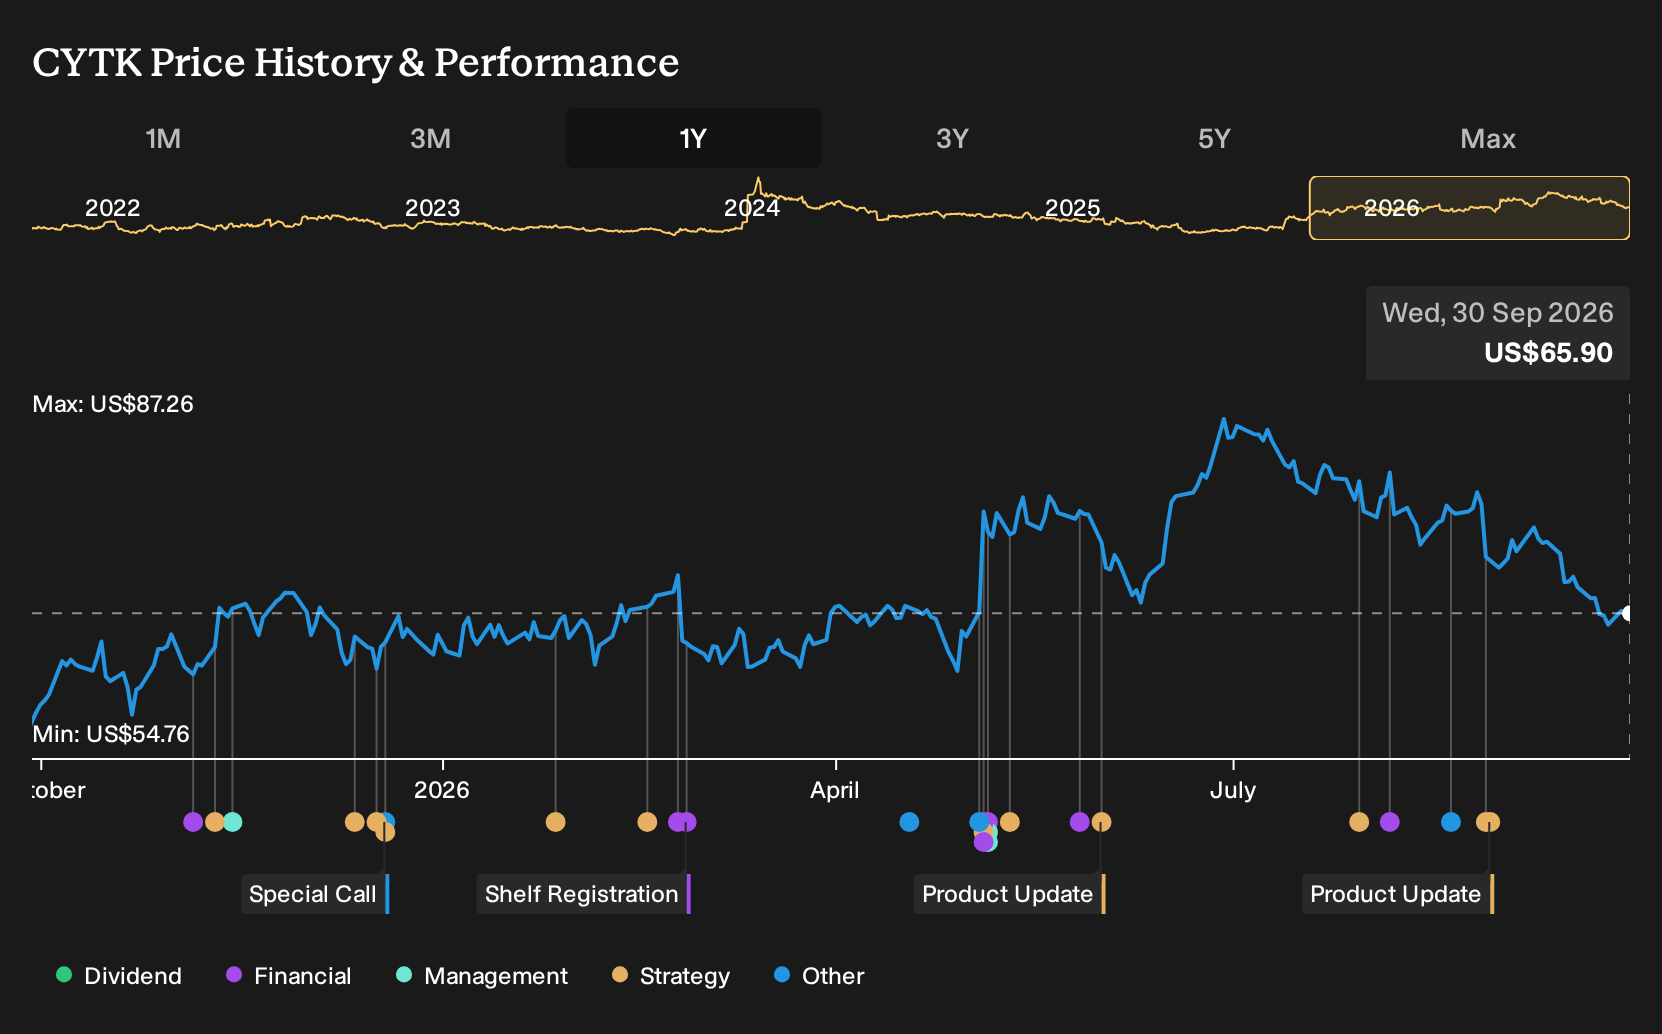
Uncover why Cytokinetics' fair value indicates a 64% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle to watch is payer pushback. The most cautious analysts already framed Cytokinetics around tougher reimbursement, even while modeling revenue of US$892.0m and earnings of US$155.6m by 2029. That group sounded more skeptical, not more bullish. ASPEN-HCM could shift those views in either direction once real world data arrives.
Explore 2 other Cytokinetics fair value estimates, including one that suggests it could be worth just $107.80!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cytokinetics research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Cytokinetics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cytokinetics' overall financial health at a glance.
Looking for more Cytokinetics style investment ideas?
If the Cytokinetics story has sharpened your thinking about risk, upside, and execution, you can apply that same lens to a wider watchlist by running a few focused screens on Simply Wall St.
- If capital preservation matters most to you, you can start with a basket of companies that score well on stability and resilience using our 32 resilient stocks with low risk scores.
- For investors who are looking for quality at a reasonable entry point, you can filter for attractively priced businesses with strong fundamentals through the 31 high quality undervalued stocks.
- If balance sheet strength is your anchor, you can build a shortlist around companies with solid financial footing using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com