
Xinxiang Chemical Fiber And 2 Other Undiscovered Gems In Asia
As global markets navigate the complexities of inflation and interest rate dynamics, small-cap stocks in Asia present intriguing opportunities amid broader market fluctuations. While the Russell 2000 Index has seen some pullback, the resilience of certain sectors in Asia offers potential for growth, making it an opportune moment to explore lesser-known companies like Xinxiang Chemical Fiber that could thrive under current economic conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Apex Mining | 22.02% | 24.39% | 37.14% | ★★★★★★ |
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Eurocharm Holdings | 2.66% | 3.48% | 7.39% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| SPRIX | 13.12% | 6.95% | -5.71% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
Let's review some notable picks from our screened stocks.
Xinxiang Chemical Fiber (SZSE:000949)
Simply Wall St Value Rating: ★★★★★☆
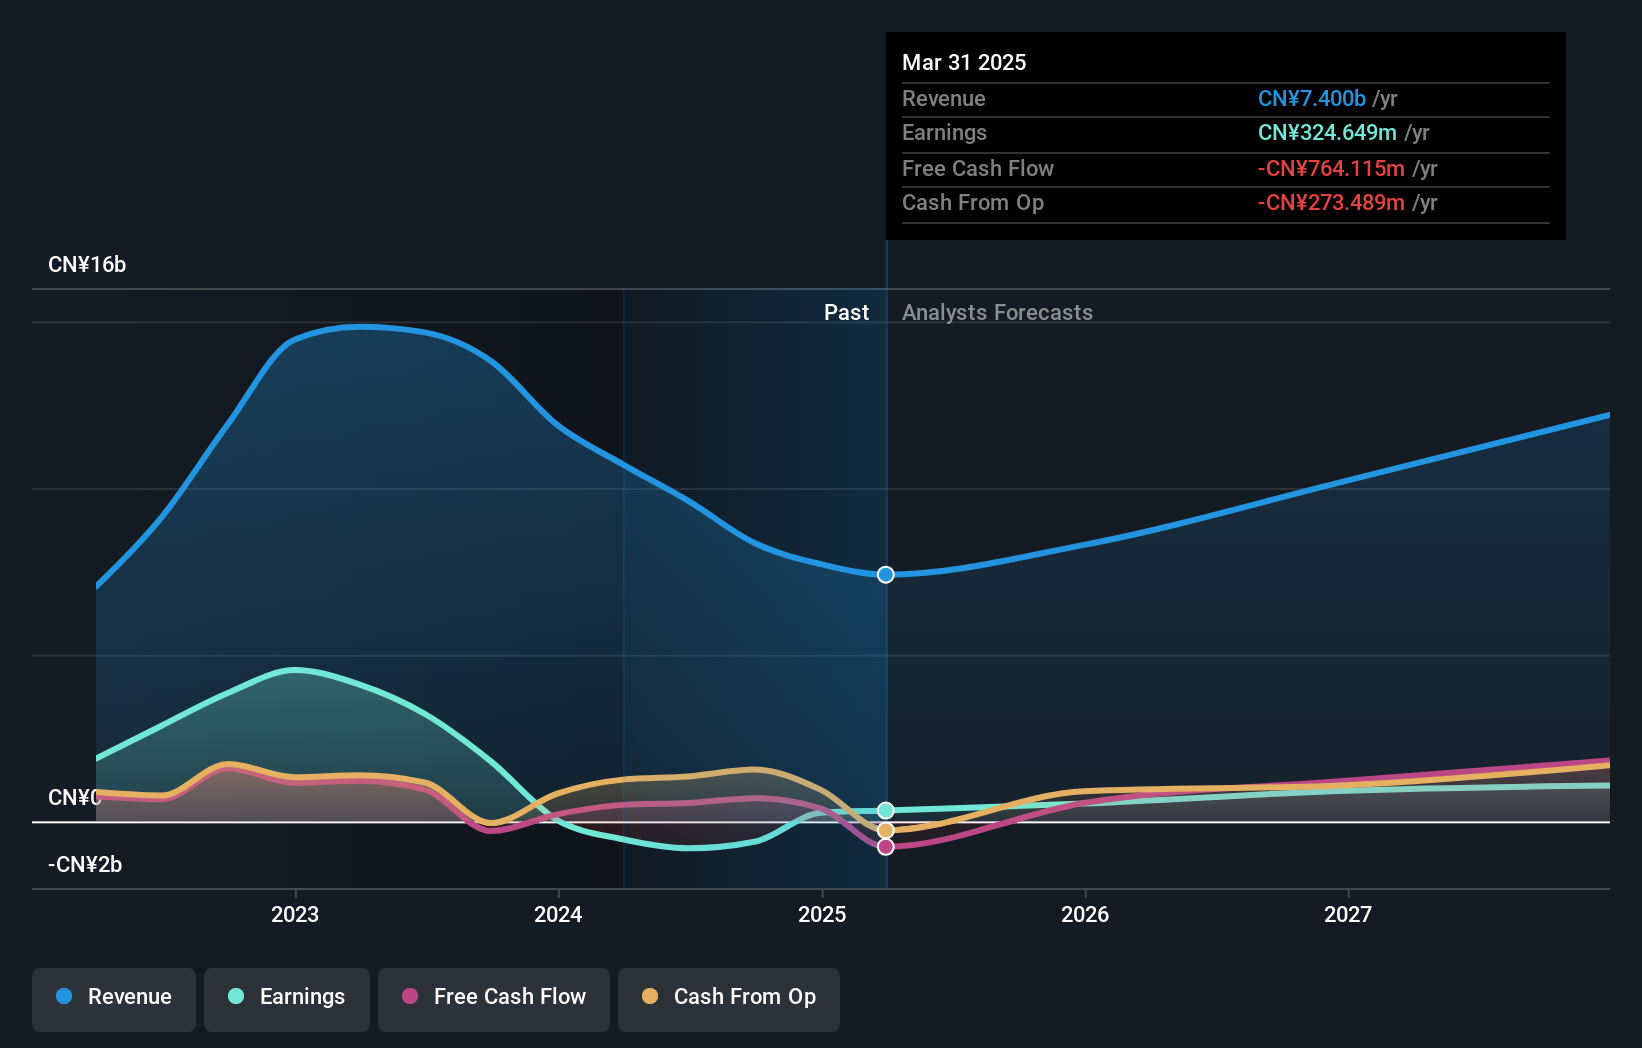
Overview: Xinxiang Chemical Fiber Co., Ltd. is a company engaged in the production and sale of chemical fiber products in China, with a market capitalization of approximately CN¥10.67 billion.
Operations: Xinxiang Chemical Fiber generates revenue primarily from its chemical fiber industry, amounting to CN¥8.70 billion.
Xinxiang Chemical Fiber stands out with a notable earnings growth of 206% over the past year, surpassing the Chemicals industry average of 3.5%. The company reported net income of CNY 344.51 million for the first half of 2026, a significant jump from CNY 62.75 million in the previous year. Despite its high net debt to equity ratio at 53.1%, interest payments are well covered by EBIT at a multiple of 5.7x, indicating sound financial management amidst high leverage. Furthermore, trading at nearly 70% below estimated fair value suggests potential upside in comparison to peers and industry standards.
- Click to explore a detailed breakdown of our findings in Xinxiang Chemical Fiber's health report.
Assess Xinxiang Chemical Fiber's past performance with our detailed historical performance reports.

Sichuan Yahua Industrial Group (SZSE:002497)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Sichuan Yahua Industrial Group Co., Ltd. operates in the lithium and civil explosive sectors both domestically and internationally, with a market capitalization of approximately CN¥17.95 billion.
Operations: Yahua generates revenue primarily from its Lithium Industry Division, contributing approximately CN¥8.27 billion, and its Civil Explosion Division, which adds around CN¥4.25 billion.
Yahua Industrial, a notable player in the chemicals sector, has shown remarkable growth with earnings surging by 489.1% over the past year, far outpacing the industry average of 3.5%. The company's net income for H1 2026 was CNY 1.22 billion compared to CNY 135.77 million a year ago, reflecting substantial profitability improvements. Despite its debt-to-equity ratio increasing from 4.9% to 13.6% over five years, Yahua holds more cash than its total debt and trades at an attractive valuation—85% below estimated fair value—suggesting potential upside as it continues to grow faster than peers in its industry.
Tokuyama (TSE:4043)
Simply Wall St Value Rating: ★★★★★☆
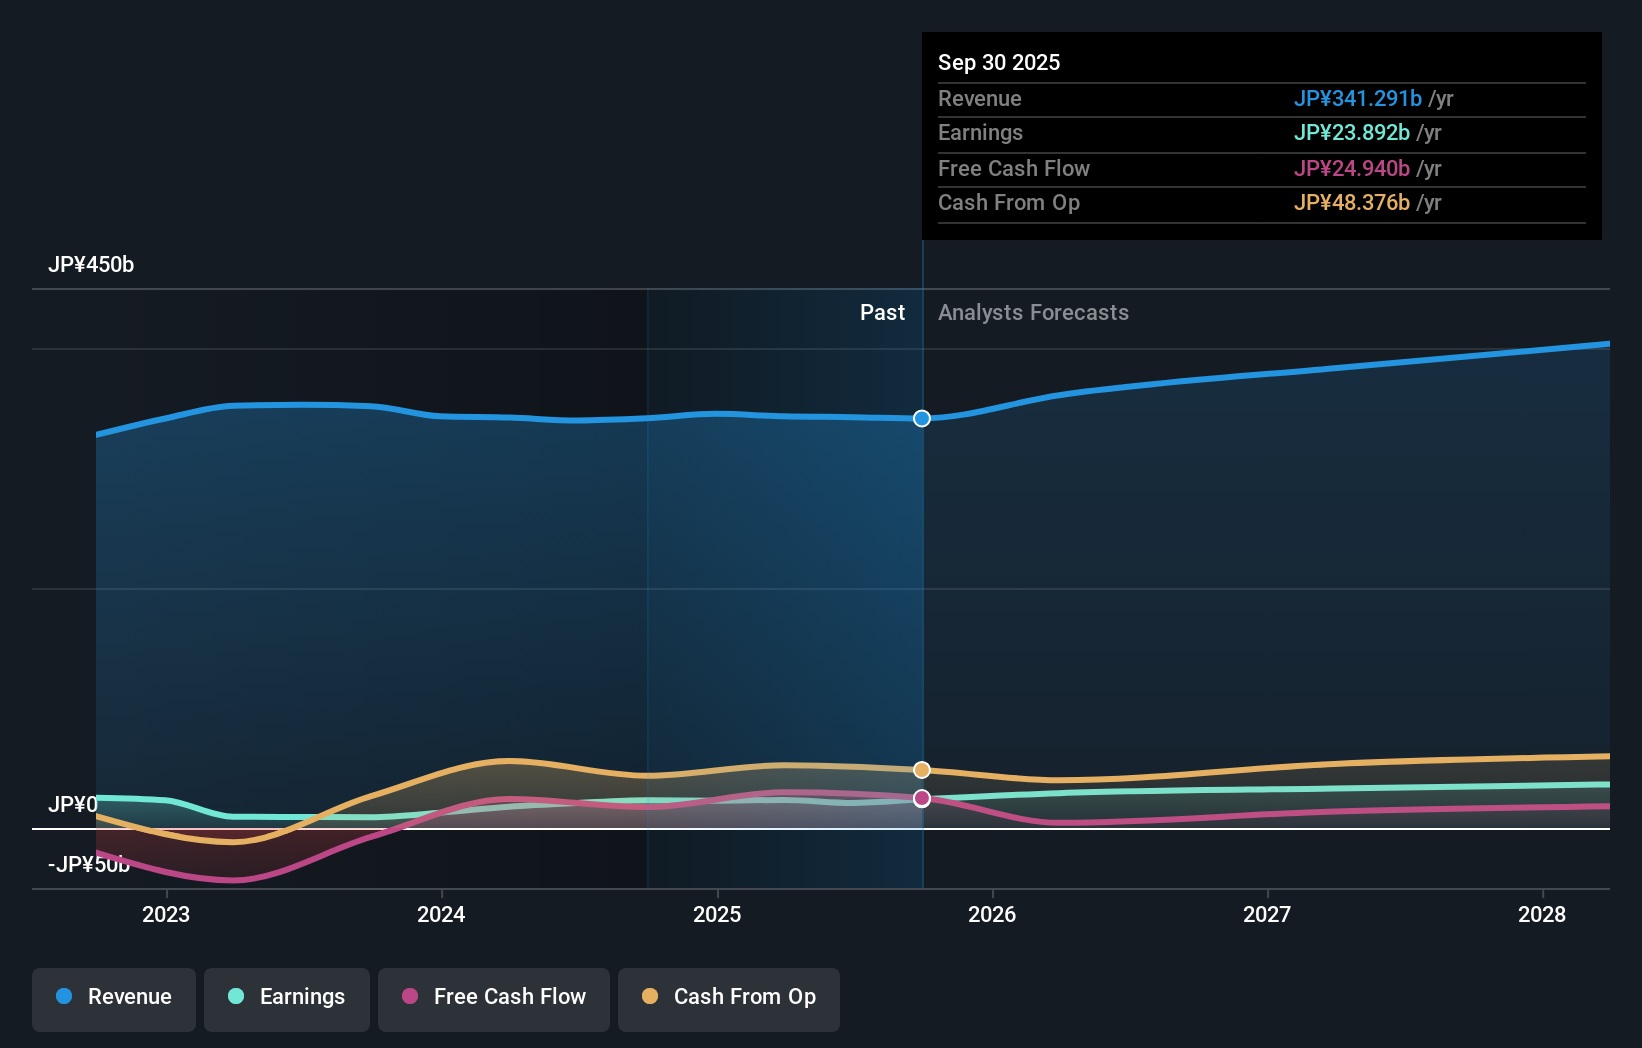
Overview: Tokuyama Corporation is a diversified chemical company engaged in the production and sale of various chemical products across Japan, Asia, and international markets with a market capitalization of ¥293.20 billion.
Operations: Tokuyama Corporation's primary revenue streams include Chemical Products at ¥103.44 billion and Electronic & Advanced Materials at ¥92.74 billion, with Cement contributing ¥66.85 billion and Life Science generating ¥54.98 billion in sales. The Environmental Business segment adds ¥5.74 billion to the overall revenue structure.
Tokuyama, a noteworthy player in the chemicals sector, has been making strategic moves despite its relatively modest market size. The company reported first-quarter sales of ¥85.65 billion, up from ¥81.83 billion last year, with net income rising to ¥5.20 billion from ¥4.91 billion. Basic earnings per share increased to ¥72.34 compared to the previous year's ¥68.27, reflecting solid operational performance amidst industry challenges where its earnings growth of 7.7% lagged behind the sector's 24.9%. Tokuyama's debt-to-equity ratio climbed over five years but remains satisfactory at 36%, while interest payments are well-covered by EBIT at 68x coverage, showcasing financial resilience and quality earnings potential as it navigates future opportunities like its recent business expansion in cement sales through a new subsidiary structure with Taiheiyo Cement Corporation.
- Unlock comprehensive insights into our analysis of Tokuyama stock in this health report.
Gain insights into Tokuyama's historical performance by reviewing our past performance report.
Where To Now?
- Investigate our full lineup of 117 Asian Undiscovered Gems With Strong Fundamentals right here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com