
High Insider Stakes Drive Growth In These 3 Asian Stocks
Amidst the evolving landscape of Asia's financial markets, where technology and semiconductor sectors are gaining traction, insider ownership emerges as a significant factor in assessing potential growth opportunities. High insider stakes often signal confidence in a company's future prospects, making them an attractive focus for investors navigating today's complex economic environment.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Seojin SystemLtd (KOSDAQ:A178320) | 18% | 106.6% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Meitu (SEHK:1357) | 23% | 26.7% |
| Meiko Electronics (TSE:6787) | 19.2% | 34.3% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Underneath we present a selection of stocks filtered out by our screen.
Semight Instruments (SHSE:688808)
Simply Wall St Growth Rating: ★★★★★★
Overview: Semight Instruments Co., Ltd. develops and supplies test and measurement instruments and equipment in China and internationally, with a market cap of CN¥235.01 billion.
Operations: Revenue Segments (in millions of CN¥):
Insider Ownership: 27.5%
Earnings Growth Forecast: 69.2% p.a.
Semight Instruments exhibits robust growth potential, with earnings forecast to grow 69.25% annually and revenue expected to increase by 61.6% per year, outpacing the Chinese market significantly. Despite high share price volatility, the company's recent half-year results show remarkable performance with net income soaring from CNY 56.54 million to CNY 567.13 million year-over-year. The recent stock split reflects confidence in future growth, although insider trading data over the past three months is unavailable.
- Click here and access our complete growth analysis report to understand the dynamics of Semight Instruments.
- Upon reviewing our latest valuation report, Semight Instruments' share price might be too optimistic.
M31 Technology (TPEX:6643)
Simply Wall St Growth Rating: ★★★★★★
Overview: M31 Technology Corporation offers silicon intellectual property design services within the integrated circuit industry and has a market capitalization of NT$23.36 billion.
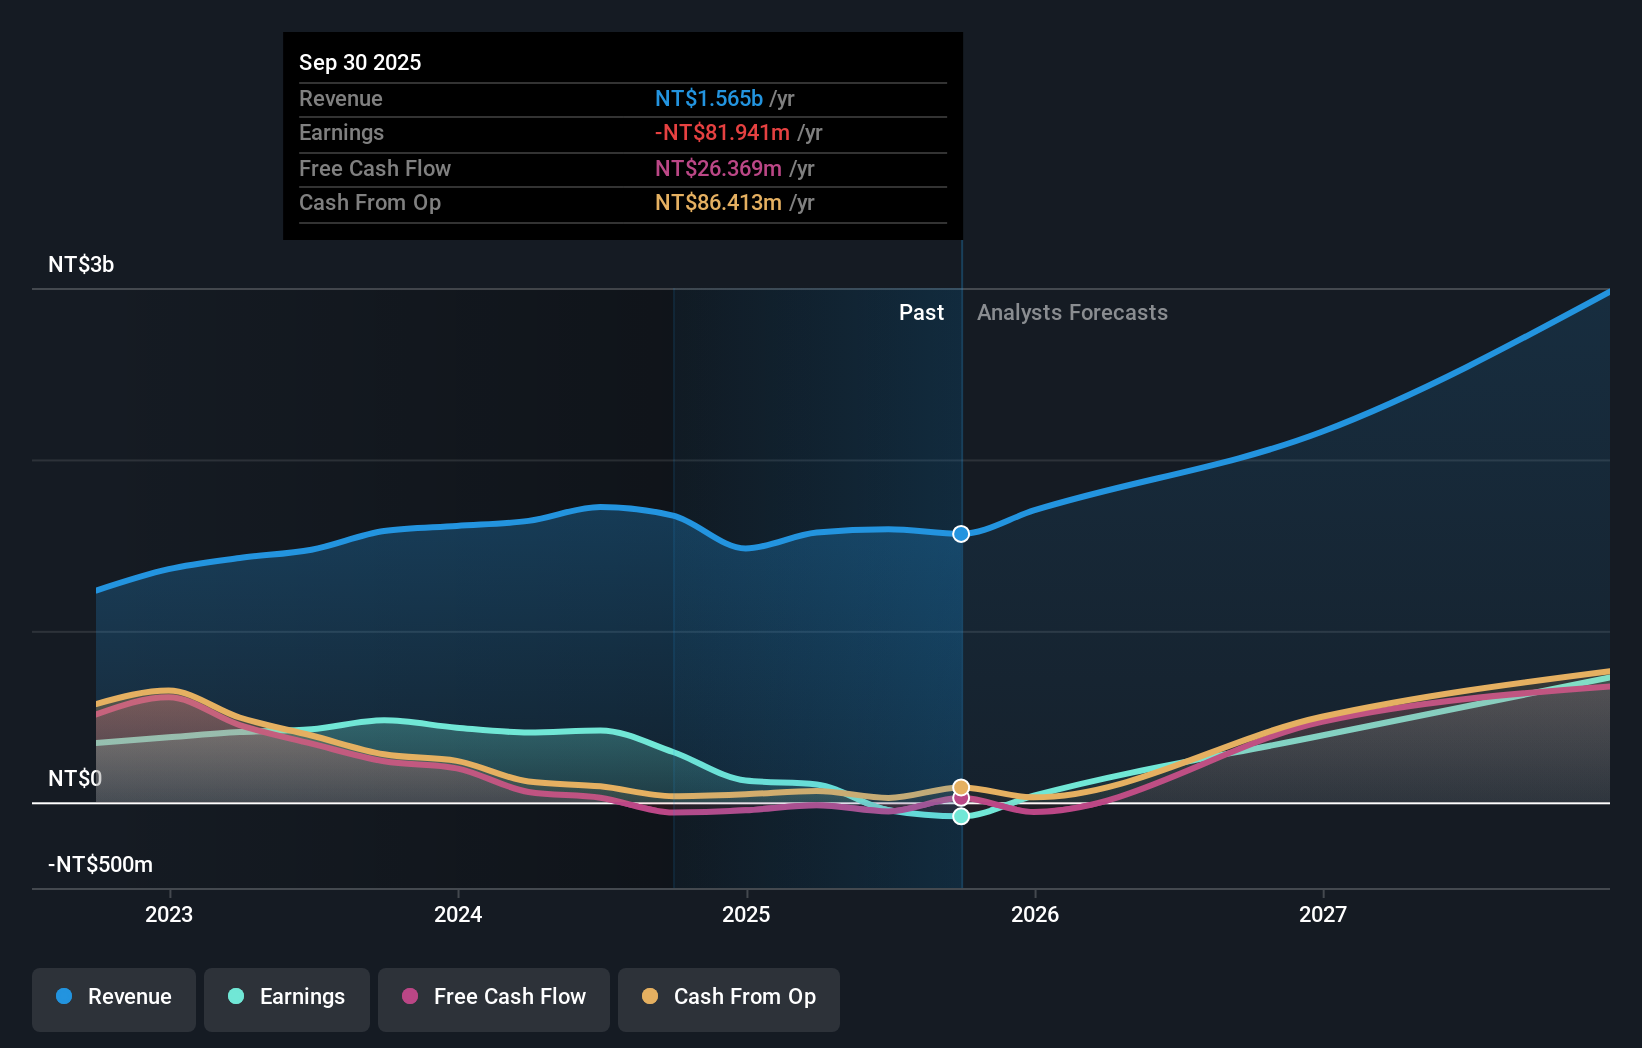
Operations: The company generates revenue of NT$1.72 billion from its semiconductor equipment and services segment.
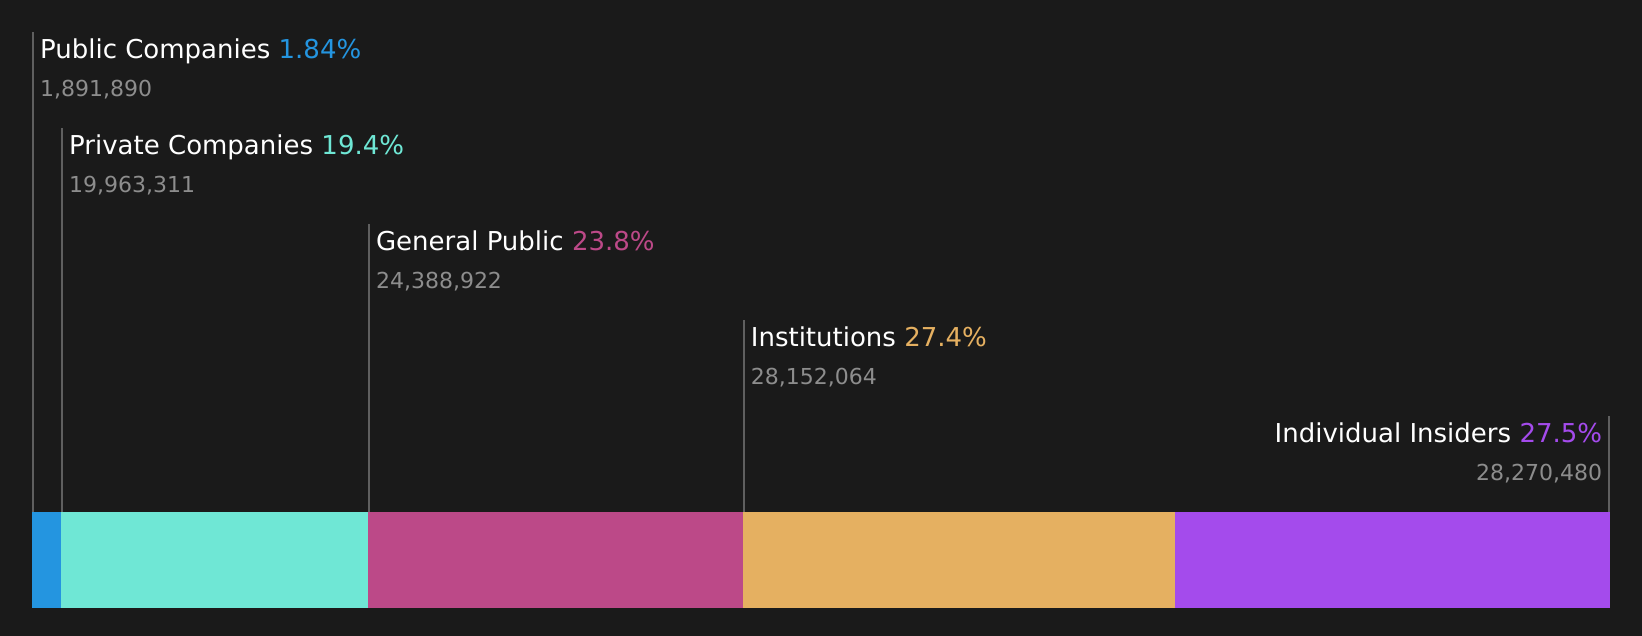
Insider Ownership: 25.7%
Earnings Growth Forecast: 78.4% p.a.
M31 Technology demonstrates strong growth prospects with earnings expected to grow significantly at 78.4% annually, surpassing the Taiwan market. Despite recent losses, strategic alliances with Ambiq and Rambus enhance its competitive edge in AIoT and MIPI interface markets. The private placement involving ASPEED Technology aims to strengthen partnerships for future development. While share price volatility remains a concern, M31's innovative collaborations and expanding IP portfolio position it well for sustained growth in high-demand sectors.
- Take a closer look at M31 Technology's potential here in our earnings growth report.
- Our valuation report unveils the possibility M31 Technology's shares may be trading at a premium.
Astroscale Holdings (TSE:186A)
Simply Wall St Growth Rating: ★★★★★★
Overview: Astroscale Holdings Inc. focuses on the research and development of on-orbit service technologies across Japan, the United Kingdom, the United States, and France, with a market cap of ¥179.37 billion.
Operations: Astroscale Holdings Inc.'s revenue primarily comes from its Orbital Services segment, totaling ¥5.89 billion.
Insider Ownership: 12.6%
Earnings Growth Forecast: 64.6% p.a.
Astroscale Holdings shows promising growth potential, with revenue forecasted to grow at 44.2% annually, outpacing the Japanese market. Despite a recent increase in net losses and volatile share prices, the company's strategic initiatives like the EUR 13.2 million deorbiting mission contract under France's 2030 program highlight its expanding role in space sustainability. The company is expected to become profitable within three years, supported by high return on equity projections and innovative space solutions.
- Dive into the specifics of Astroscale Holdings here with our thorough growth forecast report.
- The valuation report we've compiled suggests that Astroscale Holdings' current price could be inflated.

Next Steps
- Unlock more gems! Our Fast Growing Asian Companies With High Insider Ownership screener has unearthed 491 more companies for you to explore.Click here to unveil our expertly curated list of 494 Fast Growing Asian Companies With High Insider Ownership.
- Contemplating Other Strategies? The best AI stocks today may lie beyond giants like Nvidia and Microsoft. Find the next big opportunity with these 18 smaller AI-focused companies with strong growth potential through early-stage innovation in machine learning, automation, and data intelligence that could fund your retirement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com