
Exploring 3 Undervalued Small Caps With Insider Action In The Asian Market
As the Asian markets navigate a landscape marked by fluctuating economic indicators and shifting investor sentiment, small-cap stocks have experienced varied performance amid these dynamics. Despite the broader market challenges, certain small-cap companies in Asia are attracting attention due to insider activity, suggesting potential opportunities for investors seeking value.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 4.0x | 0.9x | 23.16% | ★★★★★★ |
| Q Technology (Group) | 3.5x | 0.2x | 43.23% | ★★★★★☆ |
| Australian Finance Group | 7.3x | 0.3x | 25.61% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 7.1x | 0.9x | 37.35% | ★★★★★☆ |
| Credit Corp Group | 9.2x | 2.0x | 41.90% | ★★★★★☆ |
| Universal Robina | 11.4x | 0.7x | 28.90% | ★★★★☆☆ |
| Aztech Global | 11.9x | 1.0x | -89.41% | ★★★★☆☆ |
| GT Capital Holdings | 3.0x | 0.3x | 15.53% | ★★★★☆☆ |
| Domino's Pizza Enterprises | NA | 1.0x | 9.33% | ★★★★☆☆ |
| Citicore Energy REIT | 13.3x | 10.0x | 26.61% | ★★★☆☆☆ |
Let's take a closer look at a couple of our picks from the screened companies.
DMCI Holdings (PSE:DMC)
Simply Wall St Value Rating: ★★★★☆☆
Overview: DMCI Holdings operates in real estate, mining, and other business segments with a market cap of ₱878.31 billion.
Operations: DMCI Holdings generates revenue primarily from its DMCI Homes and DMCI Mining segments, with a significant segment adjustment contributing to the overall figures. The company experienced fluctuations in its net income margin, which was 21.51% as of June 2022 and decreased to 15.15% by September 2026. This indicates variability in profitability over time, despite consistent revenue streams from its key business units.
PE: 5.6x
DMCI Holdings, a small cap in Asia, showcases mixed signals for investors. Despite a drop in second-quarter sales to PHP 3.72 billion from PHP 4.08 billion last year, revenue surged to PHP 36.35 billion from PHP 29.74 billion, with net income rising significantly to PHP 6.52 billion from PHP 4.02 billion the previous year, reflecting potential growth avenues amid declining earnings forecasts of 0.4% annually over three years and reliance on external borrowing for funding without customer deposits adding risk factors into the mix.
- Get an in-depth perspective on DMCI Holdings' performance by reading our valuation report here.
Review our historical performance report to gain insights into DMCI Holdings''s past performance.

Maynilad Water Services (PSE:MYNLD)
Simply Wall St Value Rating: ★★★★★★
Overview: Maynilad Water Services operates in the water and wastewater services sector, providing essential utilities to its customers, with a market capitalization of ₱38.50 billion.
Operations: The company generates its revenue primarily from water and wastewater services, with recent figures reaching ₱37.41 billion. Its cost of goods sold (COGS) stands at ₱5.24 billion, contributing to a gross profit margin of 85.99%. Operating expenses are significant, including general and administrative expenses totaling ₱4.24 billion. The net income margin is recorded at 43.48%, reflecting the company's profitability after accounting for all expenses and non-operating costs.
PE: 7.5x
Maynilad Water Services, a smaller player in the Asian market, shows potential through its recent earnings growth and strategic initiatives. The company's net income for Q2 2026 rose to PHP 4.52 billion from PHP 3.85 billion in the previous year, despite operating with higher-risk external borrowing. Insider confidence is evident as they increased their shareholdings recently. Additionally, Maynilad's involvement in a long-term public-private partnership for New Clark City underscores its commitment to expanding water services infrastructure.
- Dive into the specifics of Maynilad Water Services here with our thorough valuation report.
Learn about Maynilad Water Services' historical performance.
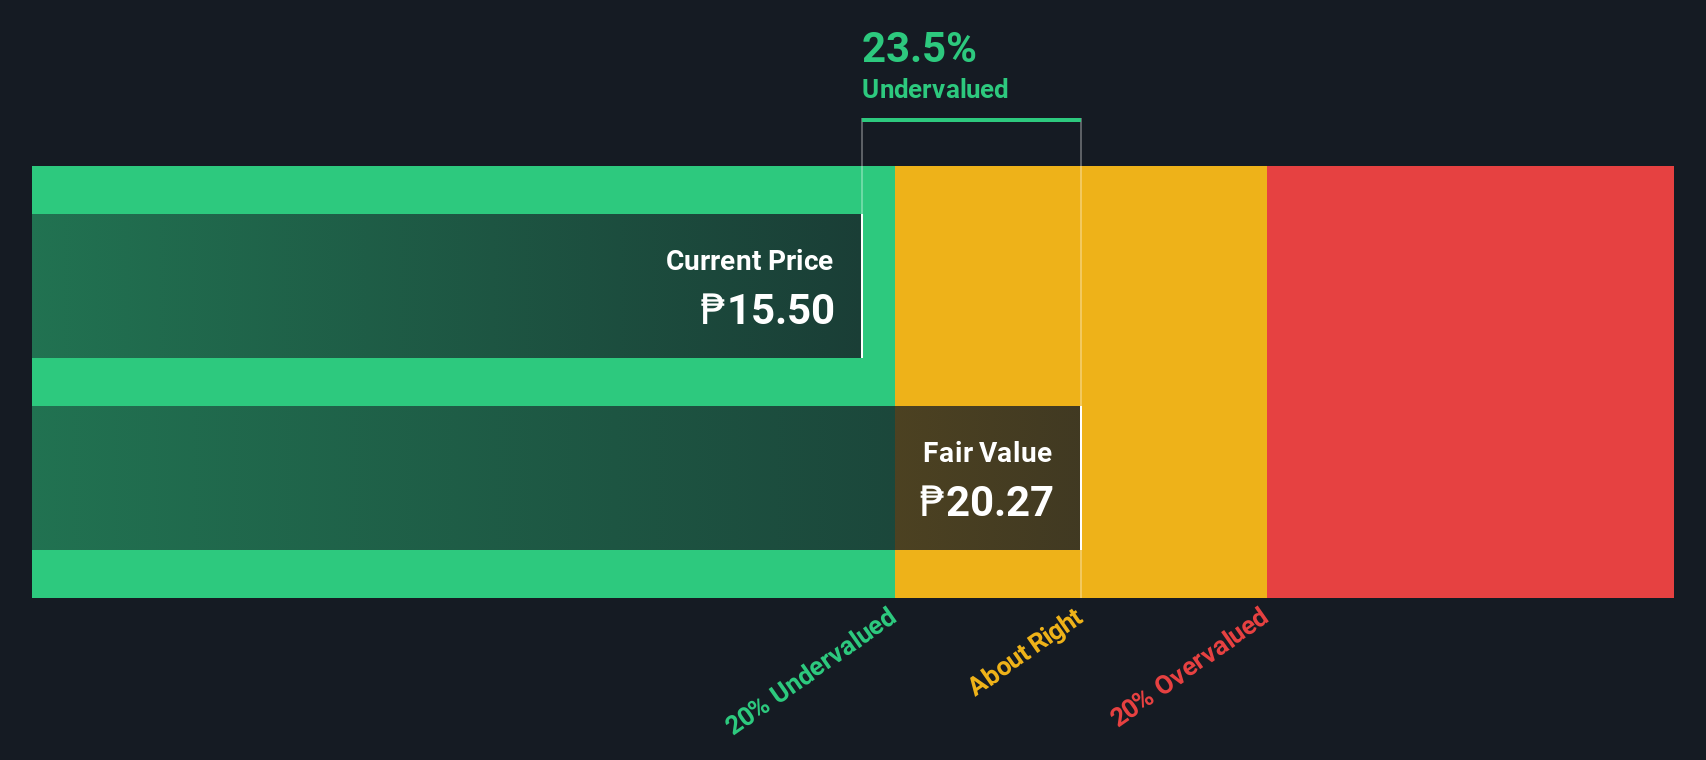
Security Bank (PSE:SECB)
Simply Wall St Value Rating: ★★★★★★
Overview: Security Bank is a financial institution that provides a range of services including retail banking, business banking, financial markets, and wholesale banking with operations contributing to its market capitalization of ₱103.38 billion.
Operations: Security Bank generates revenue primarily through Retail Banking and Wholesale Banking, with significant contributions also from Financial Markets. The bank's net income margin has experienced fluctuations, reaching a high of 41.62% in late 2016 and declining to around 21.04% by mid-2026. Operating expenses are dominated by general and administrative costs, which have shown an upward trend over the years.
PE: 4.0x
Security Bank, a smaller player in the Asian financial sector, recently joined the S&P Global BMI Index, signaling increased recognition. Their earnings for Q2 2026 hit PHP 3.4 billion, up from PHP 3 billion the previous year. Despite a high bad loans ratio of 3%, their forecasted annual earnings growth of 15.41% suggests potential for future gains. Recent insider confidence through share purchases indicates belief in its prospects amidst executive changes and strategic planning discussions.
- Take a closer look at Security Bank's potential here in our valuation report.
Assess Security Bank's past performance with our detailed historical performance reports.
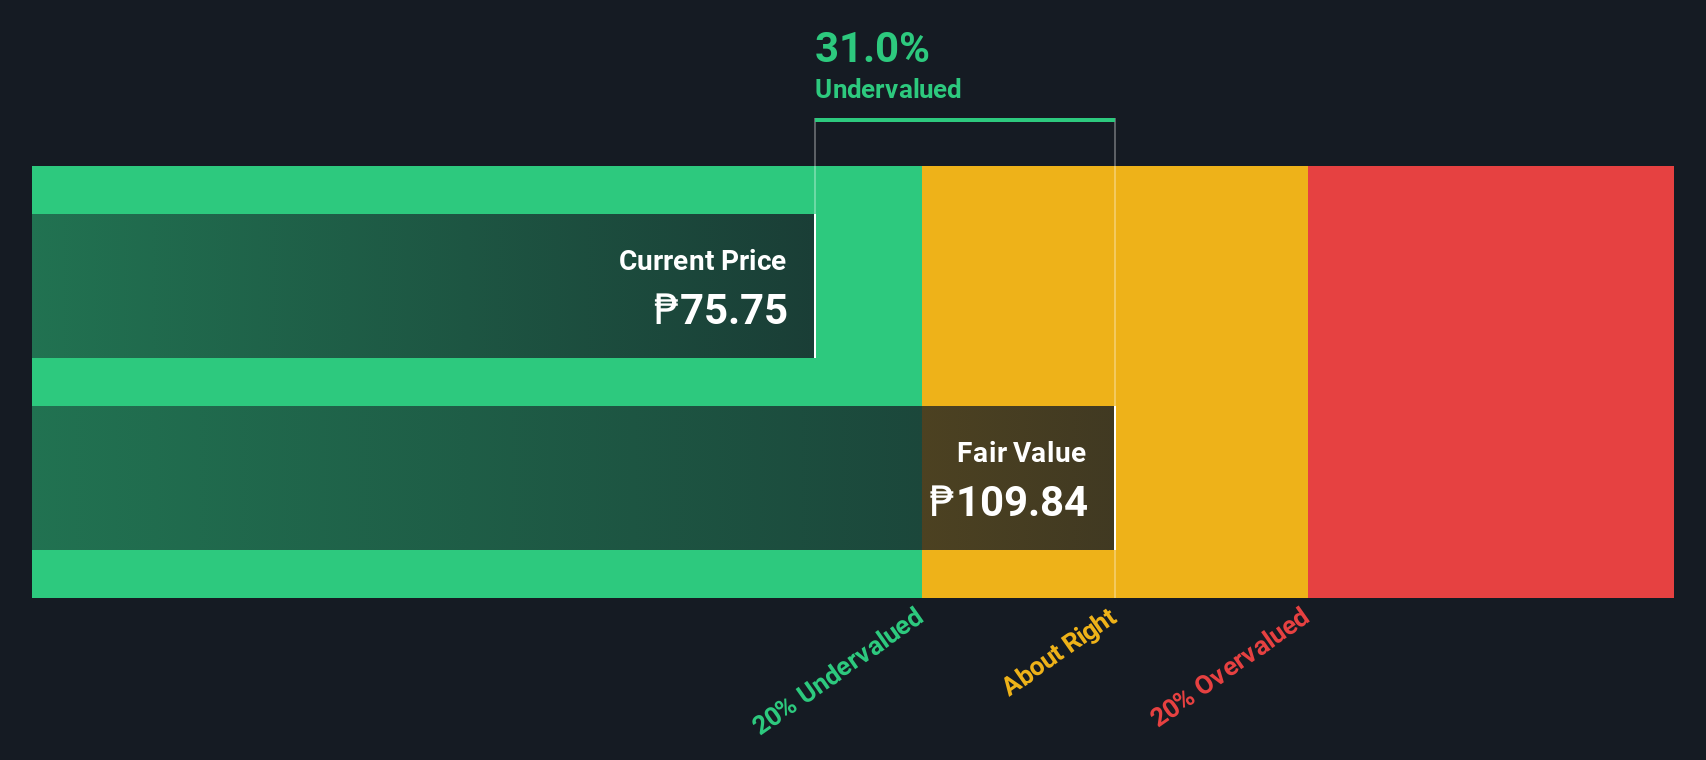
Turning Ideas Into Actions
- Take a closer look at our Undervalued Asian Small Caps With Insider Buying list of 53 companies by clicking here.
- Hold shares in these firms? Setup your portfolio in Simply Wall St to seamlessly track your investments and receive personalized updates on your portfolio's performance.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Interested In Other Possibilities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com