
The Lesson In Boozt's 61% Run Was Not The Revenue You Saw
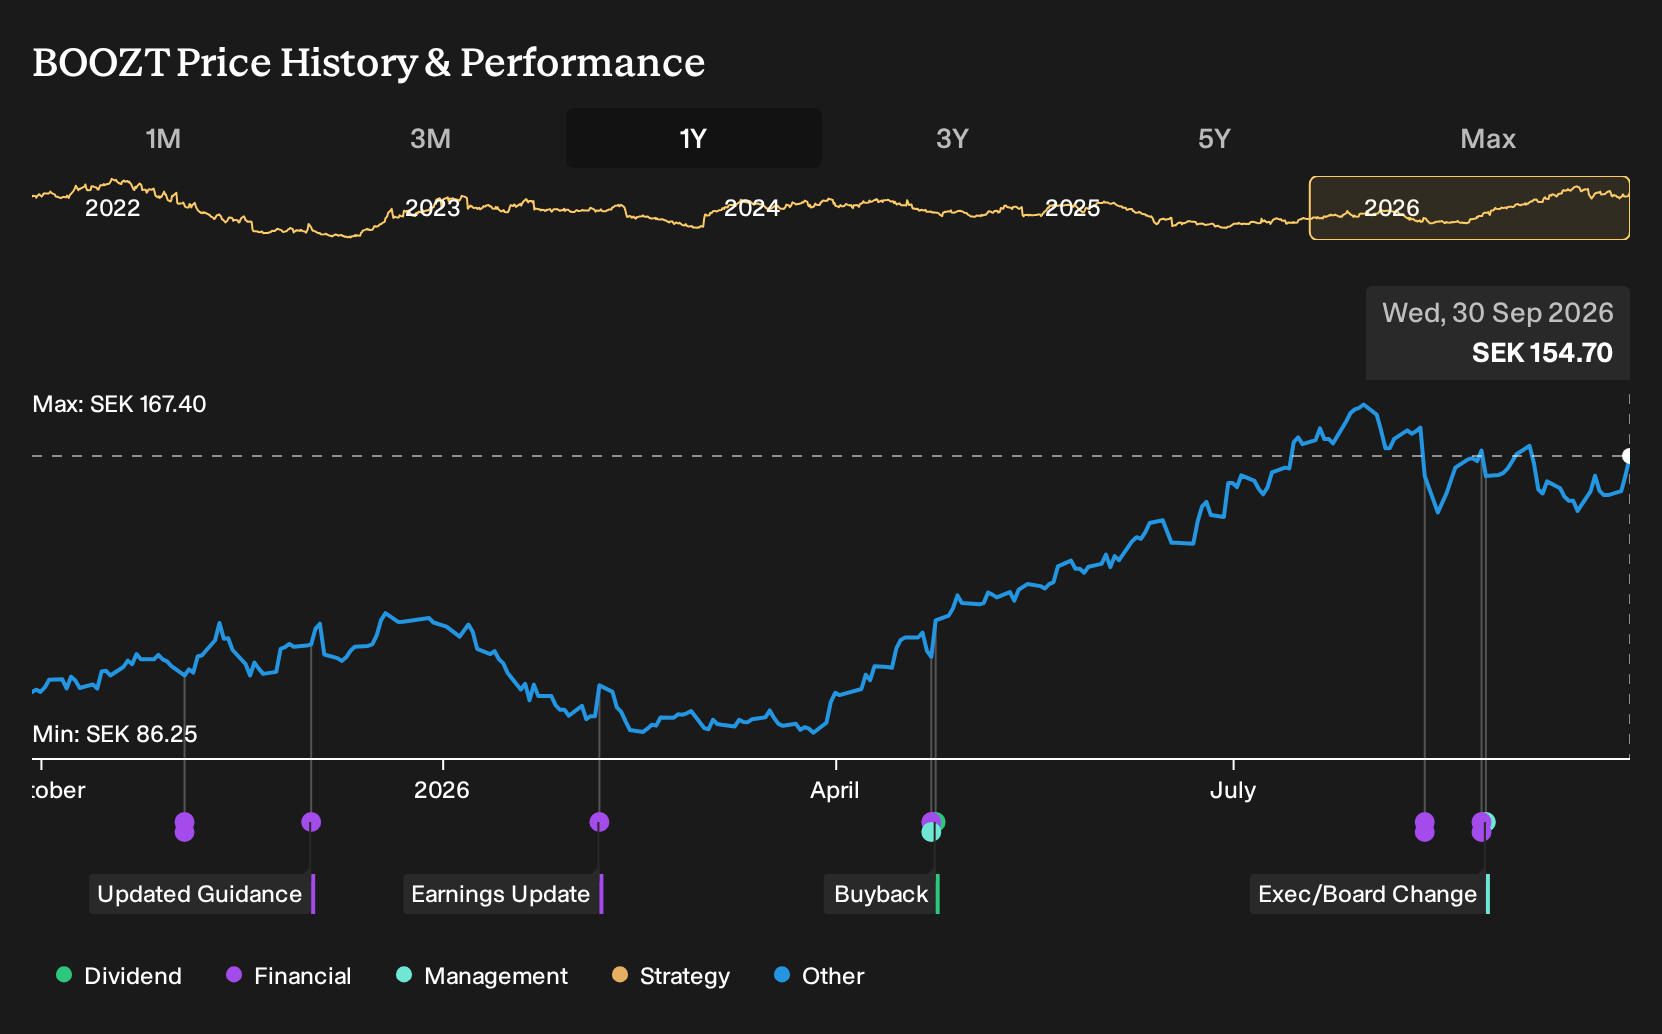
If you had bought Boozt at the end of September 2025, the past year probably feels very different now that the latest quarterly figures are on the table. For Boozt shareholders, the return over the past year was 60.6%, including dividends. That outcome sits beside fresh numbers showing revenue at 2,061 million SEK and net income at 70 million SEK. If you faced that choice again, how much weight would you put on premium growth hopes compared with rising cost and margin worries?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Boozt has already moved. See which of 190 high quality undervalued stocks still trade below our estimates.
The Two Boozt Stories Investors Had To Weigh
The shares cost SEK96.9 at the start of the period, and Boozt investors had to choose between two very different but credible stories about what might come next.
The bullish narrative put Fair Value at SEK110 and focused on Boozt using Booztlet, premium positioning and AI-driven personalisation to support 7.8% assumed annual revenue growth with profit margins reaching 4.9% over three years.
The bearish view set Fair Value at SEK85 and highlighted rising environmental rules, higher logistics and digital marketing costs, plus margin pressure in the Nordic-heavy business with profit margins assumed to be 3.7%.
What The Results Changed In The Boozt Debate
The most concrete evidence came from the latest quarter. Boozt reported revenue of 2,061 million SEK versus 1,823 million SEK a year earlier, which supported the bullish focus on top-line expansion. Profit moved the other way. Net income slipped from 76 million SEK to 70 million SEK and net margin compressed from 4.2% to 3.4%, which backed the cautious view on profitability. Overall, the evidence cut both ways.
The main lesson is simple. When a story leans on higher margins, treat net margin as the key checkpoint. Track whether Boozt and any peer actually convert extra sales into a higher percentage of profit before paying up for a richer multiple.
What Boozt's 1 Year Run Leaves You Paying For
Boozt now trades at SEK155 after a 60.6% gain over the past year. The selected narrative places its fair value above that quote and builds its case around how Booztlet, premium positioning and AI tools might scale together.
If you buy here, you are effectively judging whether Booztlet can evolve into a lower-cost, higher-volume engine that steadily lifts net margin.
"While analysts broadly agree that Booztlet is effective for inventory clearance and margin protection, they may be underestimating the platform's potential to unlock significant long-term operating leverage as it scales, turning Booztlet from a margin-dilutive clearance channel into a high-volume, lower-cost driver of both revenue and net margin, particularly as multi-category purchases and average basket size expand."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Boozt
Boozt leans heavily on digital retail, personalisation and fulfilment efficiency. Your next question is where similar online ambitions could lead elsewhere.
Large ecommerce players also chase better forecasting, smarter logistics and smoother checkout journeys. They keep pouring money into tools that cut friction and sharpen targeting.
One global platform builder supplies that kind of backbone. It helps merchants run online stores, handle payments, manage content and add AI tools.
As more retailers push for speed and automation, that infrastructure provider gains different leverage. You are no longer just watching a shopfront.
You are watching the rails underneath it, where small technical shifts can reshape competition.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 81% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com