
Resona Holdings (TSE:8308) Climbed, What Is Driving Attention Now?
Resona Holdings (TSE:8308) has put income on the table again by declaring a total dividend of $0.12 per share with an ex-dividend date of 29 September 2026, keeping its payout ratio at 24% of earnings.
Recent price action has been strong, with Resona Holdings’ share price up 2.7% over the last day, 4.0% over the past week and 16.0% across 90 days. This has contributed to a 64.1% year to date share price return and a 1 year total shareholder return of 74.4% that reflects increasingly positive sentiment around the stock’s risk and reward profile.
Scan beyond Resona Holdings and explore other dividend-focused banks with disciplined payout ratios using our hand picked 20 dividend fortresses
Resona Holdings has sprinted ahead, yet the share price still sits just below analyst targets and carries a steep modelled discount to estimated fair value. Is that gap a bargain, or a warning that the market is right to stay cautious?
Most Popular Narrative: 19% Undervalued
On the most followed view, Resona Holdings screens cheap, with a narrative fair value of ¥3,150 against a last close of ¥2,549, anchored on richer earnings and margin assumptions than the base case.
Resona's aggressive structural reforms, including full-scale generative AI adoption, end-to-end digital customer journeys, and multi-bank operational unification, position it to compress the cost/income ratio toward global best-in-class retail banking levels and structurally expand net margins over the medium and long term.
See why 0 investors see Resona Holdings as 19% undervalued.
Result: Fair Value of ¥3,150 (UNDERVALUED)
Still, the bullish Resona Holdings story relies on interest rates and loan demand not staying weak, and on fintech rivals not eroding its fee income ambitions.
Find out about the key risks to this Resona Holdings narrative.
Another View: Resona Holdings On Earnings Multiples
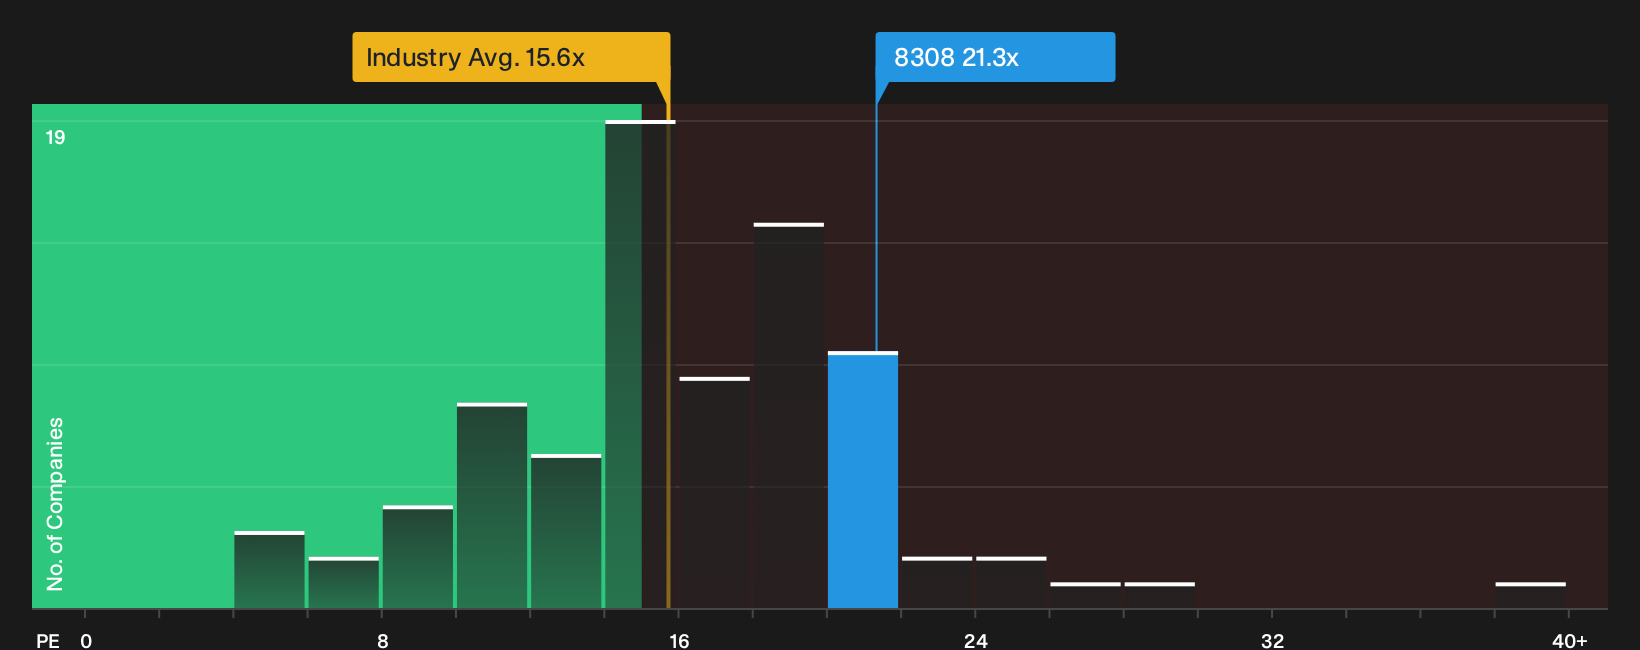
Resona Holdings looks cheap on a narrative fair value of ¥3,150, yet the current P/E of 21.3x sits well above both the JP Banks industry at 15.6x and a fair ratio of 18.5x. That richer multiple can signal optimism, or it can point to valuation risk if sentiment cools.
Investors weighing that gap may want a closer look at how earnings, peers and the fair ratio line up before deciding which story to trust. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
So far, the signals on Resona Holdings appear mixed. To move from headline stories to your own conviction, review the full balance of 3 key rewards and 1 important warning sign.
Looking for more Resona Holdings style ideas?
If Resona Holdings has sharpened your focus on opportunity, do not stop here. Broader idea hunting now can shape your next few years.
- Target compelling value setups by scanning our hand picked 18 high quality undervalued stocks before others price in their potential.
- Prioritise resilience and sleep easier at night by checking companies in the 21 resilient stocks with low risk scores built around sturdier risk profiles.
- Hunt for tomorrow's potential standouts early by reviewing the 76 high quality undiscovered gems that most investors are not watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com