
Bank of China (SEHK:3988) Could Trade At A 50% Discount After Zacks Upgrade
Bank of China (SEHK:3988) moved into focus after Zacks upgraded its rating, citing an upward trend in earnings estimates that is contributing to a more constructive view of the bank’s business outlook.
Recent price action has been firm, with Bank of China’s share price returning 26.51% over the past 90 days and 34.33% year to date. The 1 year total shareholder return of 50.70% and 5 year total shareholder return of 220.66% point to momentum that has built over a longer horizon.
Scan how Bank of China’s upgraded outlook compares with other large lenders showing strong recent returns by reviewing our hand picked list of solid balance sheet and fundamentals (205 results) in the banking space.
After a run like this, investors in Bank of China are asking the same thing: Is the sharp re rating already done, or does current pricing still leave meaningful upside on the table once valuation is unpacked next?
Most Popular Narrative: 6.9% Overvalued
The most followed narrative on Bank of China pegs fair value at HK$5.69 compared with the last close at HK$6.09. This frames the recent rally as a premium to that intrinsic value estimate.
Bank of China offers large scale, systemically important exposure to China’s banking sector, combining stability via state backing, moderate growth, and dividend yield potential. Yet the same state influence, alongside macro and property related risks, keeps a lid on how much investors are typically willing to pay versus global peers.
See why 5 investors see Bank of China as 7% overvalued.
Result: Fair Value of HK$5.69 (OVERVALUED)
Still, the Bank of China narrative can break if property related stress worsens, or if policy driven lending pressures profitability more than current assumptions allow.
Find out about the key risks to this Bank of China narrative.
Another View on Bank of China’s Value
A different lens gives a very different answer. The SWS DCF model estimates Bank of China’s fair value at HK$12.28 per share, while the stock trades around HK$6.09. That implies roughly a 50% discount. Is the current price a value gap, or is the model too optimistic about future cash flows?
Look into how the SWS DCF model arrives at its fair value.
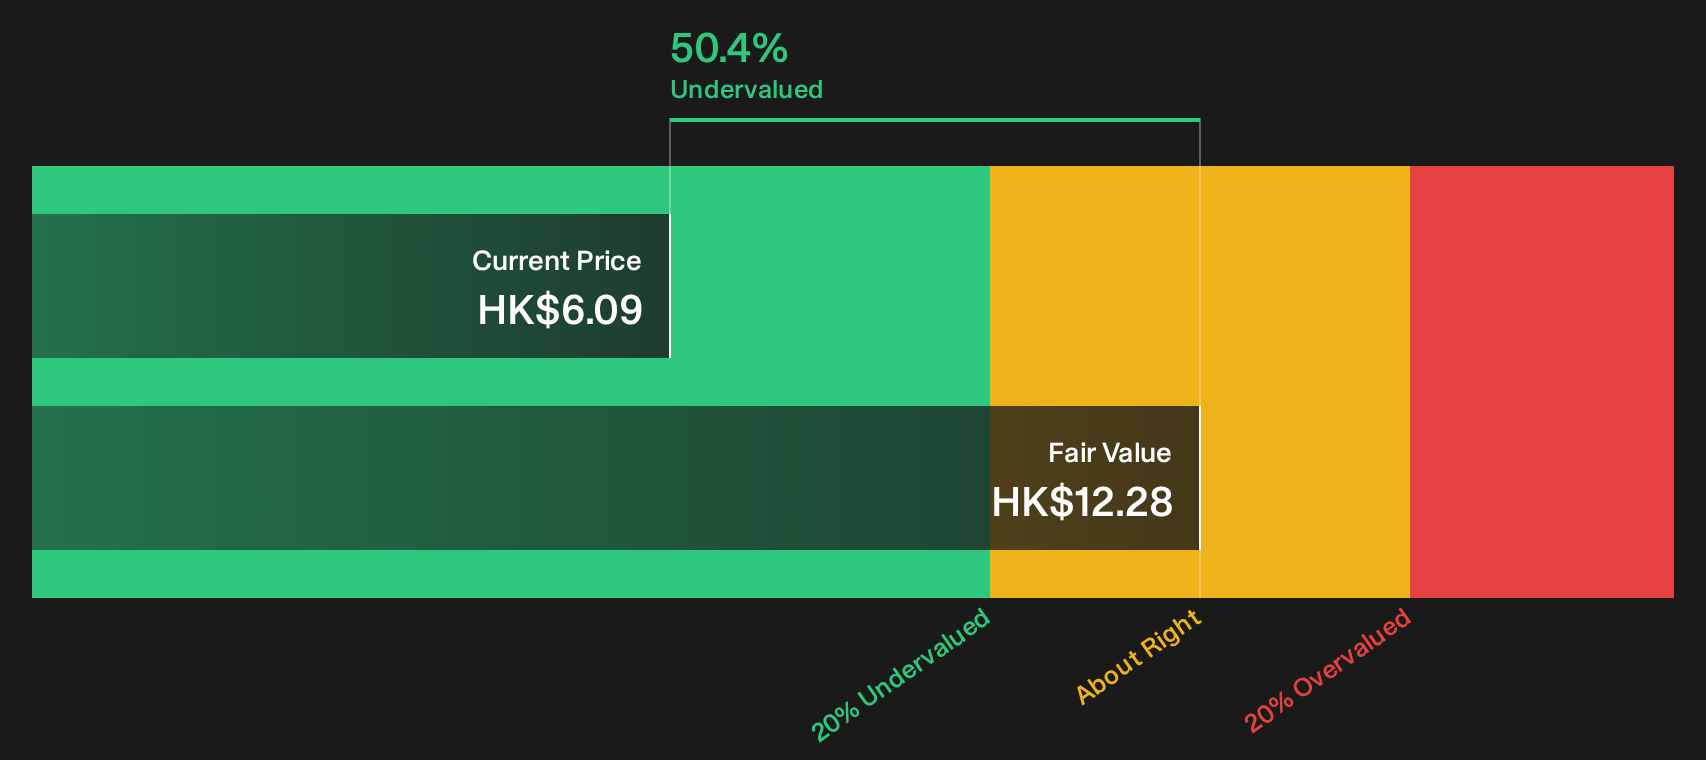
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of China for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment split on whether Bank of China is fairly priced or still misjudged, move quickly from headline takes to your own verdict by examining the upside signals in 4 key rewards.
Ready for more ideas beyond Bank of China?
If you stop with Bank of China, you risk missing other opportunities that fit your style. Use the Simply Wall Street Screener to quickly surface focused, data driven ideas that match how you like to invest.
- Target higher income potential by scanning companies we flag as 157 dividend fortresses for investors who care about cash returns today.
- Hunt for mispriced quality and see which businesses appear in our 190 high quality undervalued stocks before the crowd catches on.
- Dial down volatility in your portfolio by filtering for sturdier businesses through our 225 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com