
Ternium (TX) Gets A Fresh Value Nod As Pesqueria Growth Meets Fair Value
Ternium (TX) has drawn fresh attention after Zacks assigned the stock a Rank #1 rating with an A grade for Value, highlighting its lower P/E and PEG ratios compared with the broader steel industry.
Recent trading has been choppy for Ternium, with the share price slipping 3.0% over the past week and 1.0% over the last month. However, the 90-day share price return of 30.1% and 1-year total shareholder return of 62.1% point to momentum that has been building rather than fading.
Scan beyond Ternium and compare this value story with a curated list of other companies trading on strong fundamentals in the 32 high quality undervalued stocks.
Bulls point to Ternium’s value grades and strong recent run, while bears see a cyclical steel producer that has already moved. The valuation work shows which side the current numbers lean toward.
Most Popular Narrative: 5% Undervalued
Ternium is trading at $54.30 against a widely followed fair value estimate of $57.08, so the narrative frames the stock as slightly mispriced rather than deeply discounted. The discount rate is set at 9.13% to bring those future expectations back to today.
Substantial ongoing investment in the Pesqueria Industrial Center in Mexico is set to increase capacity by 1.5 million tons annually, with new cold rolling and galvanized lines starting ramp-up from late 2025 onward, positioning Ternium to capitalize on potential long-term demand growth from nearshoring and infrastructure projects boosting future top-line growth and operational leverage.
See why 34 investors see Ternium as 5% undervalued.
Result: Fair Value of $57.08 (UNDERVALUED)
Still, the Ternium narrative can break if global steel overcapacity keeps pricing under pressure or if the heavy Pesqueria investment strains cash flow for longer than expected.
Find out about the key risks to this Ternium narrative.
Another View: Cash Flows Point The Other Way
Ternium looks slightly undervalued on the consensus fair value of $57.08, yet the SWS DCF model tells a different story. On that approach, the shares at $54.30 sit above an estimated future cash flow value of $50.69, which frames the stock as overvalued instead.
For investors, that split matters. Price based on earnings and price based on cash generation can pull in opposite directions, so the real question is which lens you trust more when the gap is only a few dollars.
Look into how the SWS DCF model arrives at its fair value.
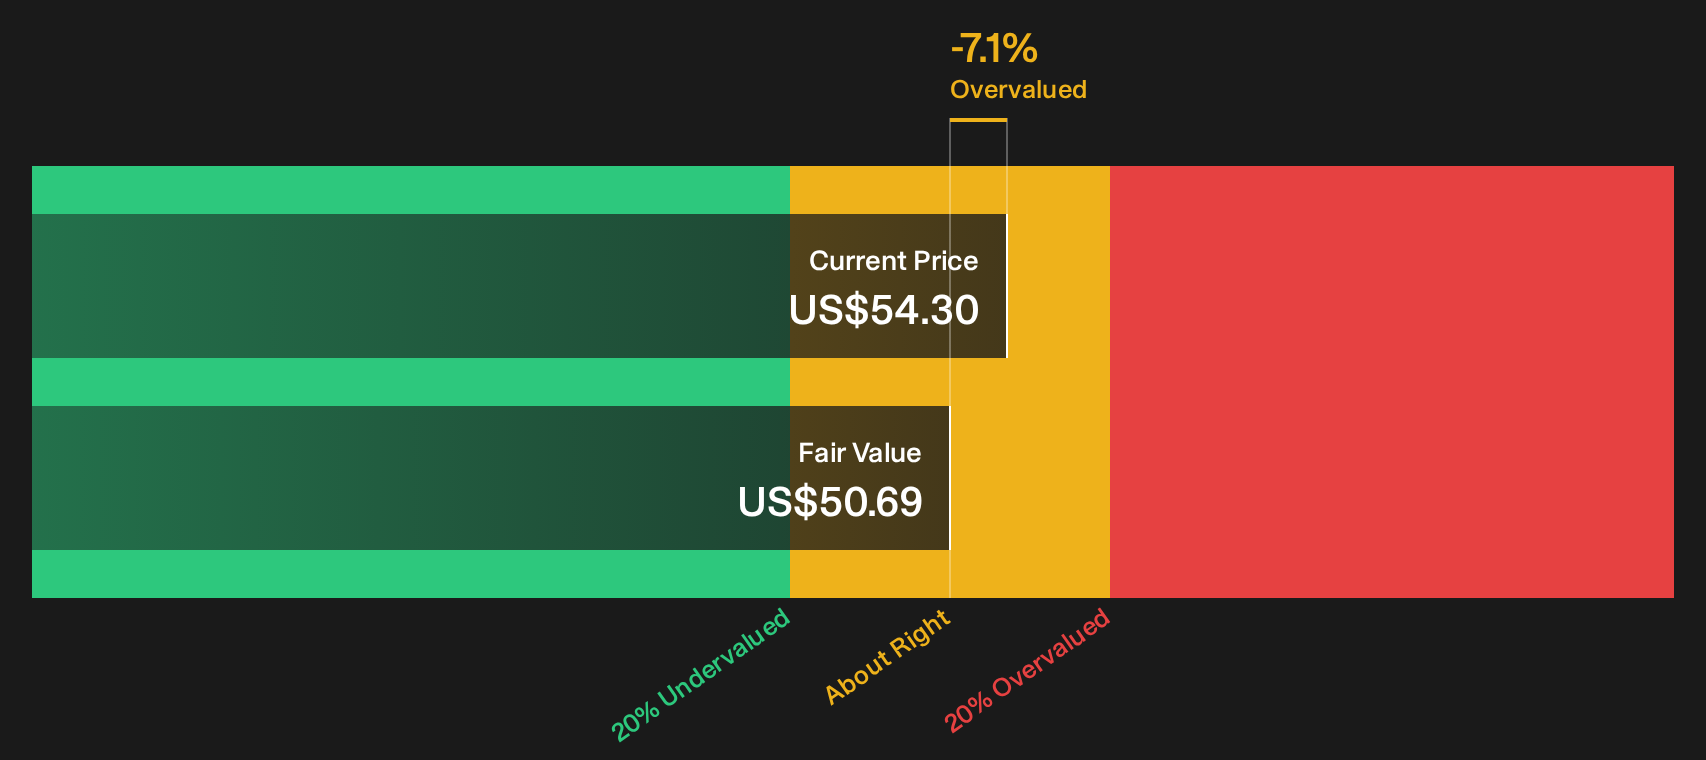
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ternium for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Ternium and not sure which way you lean yet? Use the data, stress test the thesis, then weigh up the 3 key rewards and 1 important warning sign.
Looking for more Ternium-sized investment ideas?
If Ternium has you thinking harder about value, do not stop here. Use the Simply Wall Street Screener to surface other opportunities before the crowd does.
- Target reliable income streams by reviewing companies tagged as 7 dividend fortresses that focus on higher yields with balance sheet support.
- Spot financially resilient operators through the list of solid balance sheet and fundamentals (25 results) and concentrate on businesses with stronger fundamentals backing their valuations.
- Hunt for potential future leaders hiding in plain sight using the 18 high quality undiscovered gems that couple quality metrics with limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com