
Why Everyone Is Watching Zealand Pharma (CPSE:ZEAL) Today
Zealand Pharma (CPSE:ZEAL) has just put fresh clinical data in front of investors. Phase 2 results for obesity candidate petrelintide and a positive CHMP opinion on Zeydovio are moving its late stage pipeline forward.
Recent momentum has been mixed. The share price is up 0.97% over the last day, yet has fallen 9.63% over the past month and 41.08% year to date. The 5 year total shareholder return of 47.90% shows a much stronger longer run outcome than the 1 year total shareholder loss of 45.23%.
Spot opportunities around Zealand Pharma by scanning our hand picked 134 healthcare AI stocks that could benefit from the same long term trends in obesity and specialty care.Zealand Pharma has fallen hard this year while the analyst target still sits far above the current DKK 271.1 quote. Does fair value lean closer to recent trading or to that DKK 416 marker?
Most Popular Narrative: 54% Undervalued
On the most followed view, Zealand Pharma’s fair value sits at DKK 595, well above the last close at DKK 271.1. This puts the current quote against a much richer long term story built around its peptide pipeline and partnerships.
Zealand's nimble, capital-efficient R&D engine, powered by expertise in peptide drug platforms and now supercharged by an unparalleled cash position and major milestone payments, is poised to deliver a multi-generational pipeline with lower development risk and better margins than slower-moving, less focused biotechs. As the global obesity and metabolic disease epidemic intensifies, and direct-to-consumer/payor-driven demand for better tolerated, long-term therapies accelerates, Zealand's first-mover advantage in next-gen peptide treatments could open up entirely new commercial channels, enabling them to tap into both high-margin prescription and cash-pay patient populations, further expanding revenue and profit upside beyond what traditional models forecast.
See why 1 investors see Zealand Pharma as 54% undervalued.
Analysts behind this narrative apply a DKK 595 fair value using a 5.75% discount rate and factor in forecast earnings of DKK 435.6 million by around 2029, even though their own models build in declining revenue of 3.6% a year and a drop in profit margins from 59.0% to 10.5%. That mix of lower projected profitability and a high implied future P/E of 107.9x on those earnings shows how much weight this view places on Zealand Pharma’s longer term obesity and specialty care opportunity rather than near term reported numbers.
Result: Fair Value of DKK 595 (UNDERVALUED)
Still, Zealand Pharma’s story rests heavily on late stage trial outcomes and on partners like Roche and Boehringer Ingelheim continuing to back key obesity assets.
Find out about the key risks to this Zealand Pharma narrative.
Another View: What Multiples Say About Zealand Pharma
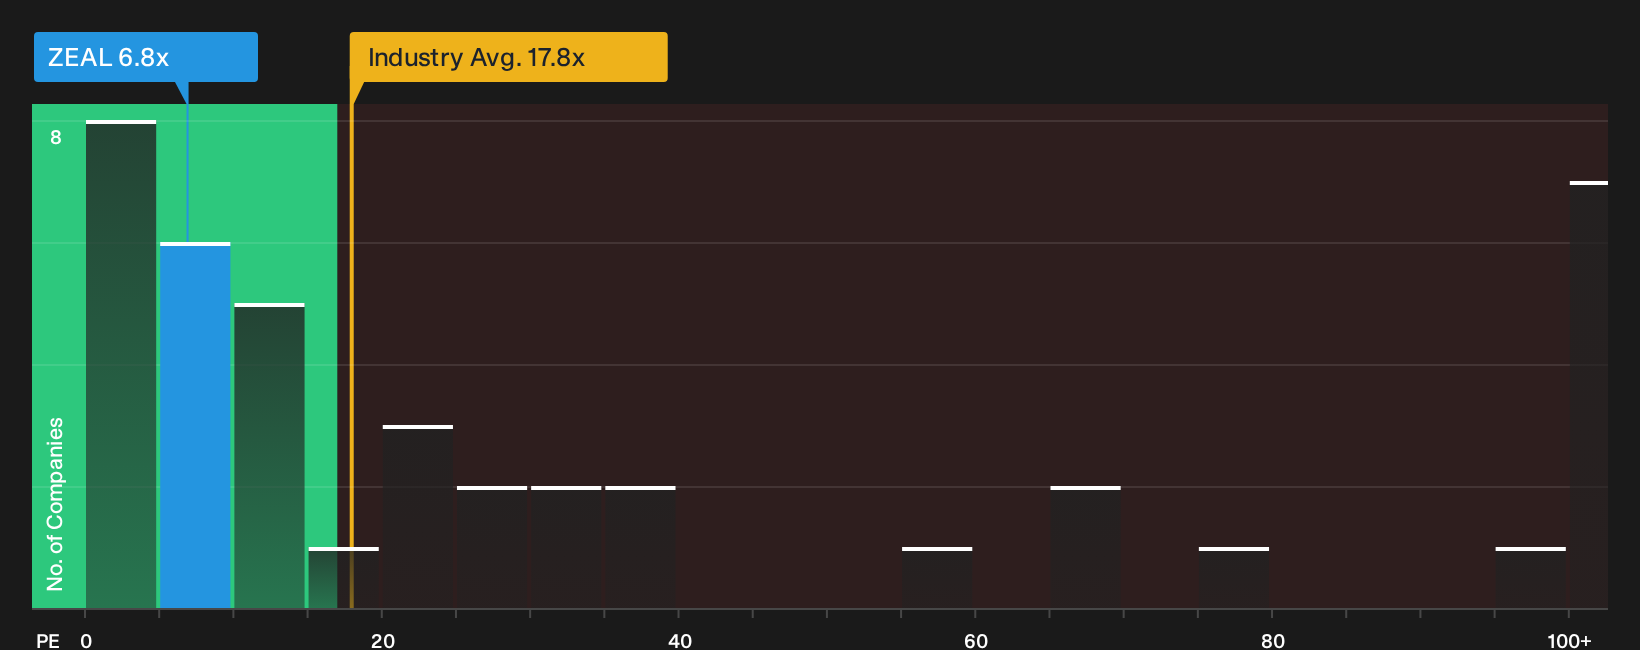
The bullish narrative leans on a DKK 595 fair value, yet the market is already paying about 6.8x earnings for Zealand Pharma. That is below the European Biotechs average P/E of 17.8x and the peer group on 44x, but slightly above its own fair ratio of 5.9x.
This mix of cheapness versus sector benchmarks and a premium to the fair ratio points to both upside potential and valuation risk. It raises a simple question for investors: Does the current DKK 271.1 price reflect a bargain on future pipeline success or a fair mark for declining earnings and revenue forecasts?
For a closer look at how this pricing gap could close, and what it might mean for valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Zealand Pharma is clearly split, so move quickly to review the full picture yourself and weigh both sides of the story. To see the balance between potential upside and the issues investors are worried about, start with 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Zealand Pharma?
If you want a broader watchlist alongside Zealand Pharma, use the Simply Wall St Screener to identify other opportunities that fit your approach.
- Explore potential upside early by scanning 616 high quality undiscovered gems before they attract wider attention.
- Focus on resilience by filtering for companies with strong finances using the list of solid balance sheet and fundamentals (205 results).
- Emphasise consistency by reviewing income focused opportunities through the 157 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com