
DoorDash (DASH) Stock Looks Above Fair Value After Its 136% Run
DoorDash has given shareholders a bumpy ride lately, with a sharp pullback following a strong multi year run. That puts fresh focus on whether today's price still lines up with what its earnings can support.
- Over the past 3 years the stock has returned 135.5%, which makes the question of what investors are paying for its earnings power much more important.
- New products like DashOS, AI driven tools and drone delivery may support expectations for stronger profitability over time, while the US$131.5m New York worker settlement highlights potential cost and compliance pressures that can affect earnings quality.
- The analysts covering DoorDash have run their own numbers. See what analysts think DoorDash's shares could be worth.
For investors, the debate is whether DoorDash's current share price is adequately backed by the earnings the business is generating today and is expected to produce in the future.
If you are weighing DoorDash against other app based delivery and local commerce plays, it can help to see how it stacks up beside 32 high quality undervalued stocks.
Does DoorDash Look Pricey on Earnings?
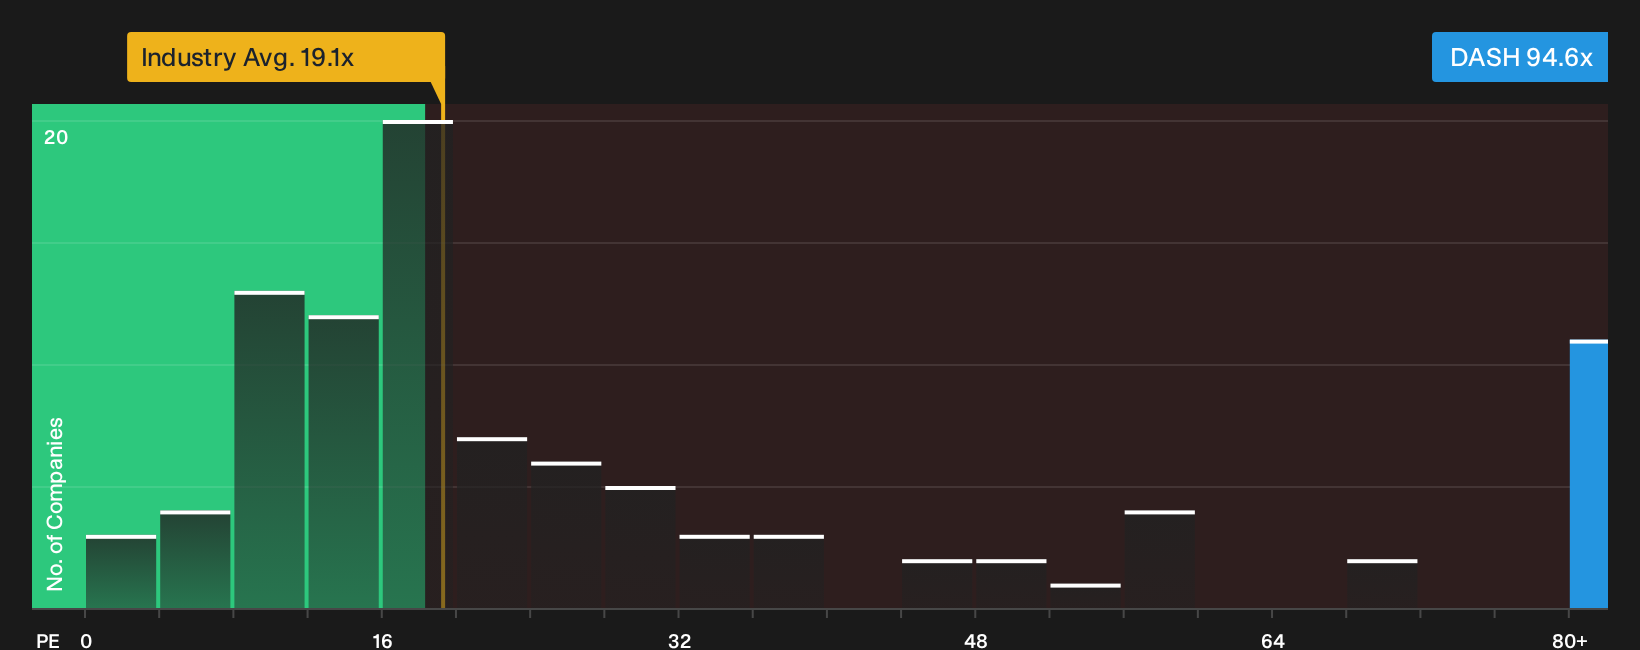
The P/E ratio is one way to see what you are paying today for each dollar of DoorDash earnings. Right now the stock trades on about 94.6x earnings, which is more than triple the Hospitality industry average of roughly 19.1x and also above the peer group on about 29.5x. A model that adjusts for DoorDash specific factors such as growth profile, margins, size and risk points to a lower multiple as a rough guide, so the current P/E appears expensive on that yardstick.
Because the market is already assigning such a rich earnings tag, fresh product launches like DashOS, AI tools and drone delivery need to justify that premium in terms of durable profitability rather than just headlines. The recent US$131.5m New York worker settlement also shows how regulatory and worker pay issues can pull against that high bar on earnings quality. For anyone considering the stock, the key question is whether DoorDash can grow into a valuation that already prices in a lot of optimism on future profit power. Explore the numbers behind DoorDash's P/E valuation.
The DoorDash Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DoorDash valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each narrative anchors a specific fair value to a clear story about DoorDash's potential catalysts and pressure points so you can track which version of events is actually unfolding over time on the Community page.
One of the top community narratives on DoorDash: roughly fairly valued
"Mounting consumer fatigue around high service and delivery fees, particularly against a backdrop of persistent inflation and economic strain, may drive customers to seek alternatives..."
Discover why this Narrative puts DoorDash at roughly fairly valued.
DoorDash’s valuation still leaves one crucial piece of the puzzle
Price tags on earnings only tell you so much when the real decisions come from the people in charge, how they think, and how they are rewarded for it. See who runs DoorDash and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com