
Mastercard (MA) Stock May Trade At A Discount As Stablecoin Push Grows
Mastercard has slipped modestly over the past year even after delivering a 62.9% gain over 5 years, which raises a sharper question for investors about whether the current share price is still supported by the returns the company earns on its capital.
- That 62.9% return over 5 years puts real weight on the idea that Mastercard's ability to earn high returns on the money it invests can justify a premium valuation over time.
- The push into stablecoin settlement and AI driven payment services, from the BVNK acquisition to new Agent Pay safeguards, may influence how efficiently Mastercard can deploy capital and turn its technology spend into future cash generation.
- Prefer to judge Mastercard on earnings? See why Mastercard's 29.7x P/E tells a different valuation story.
The issue now is whether Mastercard's current share price fairly reflects the returns it earns on its capital given this mix of long term gains and evolving payment technology bets.
For a broader view on whether Mastercard's recent moves in stablecoins and AI driven payments line up with how other businesses are putting capital to work, it can help to compare this activity against 37 profitable AI stocks that aren't just burning cash.
Does Mastercard Look Undervalued on Excess Returns?
The Excess Returns model looks at how effectively Mastercard turns each dollar of shareholder capital into profits above its equity cost. Here, the gap between what the firm earns and what it needs to earn is wide on the supplied numbers.
Analysts see a stable earnings power of $40.76 per share against a cost of equity of $1.30 per share, which implies an excess return of $39.46 built on an average return on equity that is more than 2x book value. That sits on a relatively low starting book value of $6.40 per share and a projected stable book value of $17.70 per share. In other words, the model is effectively saying Mastercard creates a lot of profit from a compact equity base. Against a traded price of $551.47, the Excess Returns projections put Mastercard's estimated intrinsic value substantially above the current share price.
Because Mastercard has started live stablecoin settlement with SoFi’s $25b card program while also pushing AI driven risk tools, the model’s view of strong excess returns may reflect how the market is weighing these newer profit pools against regulatory and execution risks. Find out what Mastercard could be worth using our Excess Returns estimate.
The Mastercard Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where Mastercard's valuation puzzle leaves off by spelling out which assumptions on future growth, margins and earnings would need to hold for the stock to be priced meaningfully higher or lower than it is today on the market. Each scenario is framed as a thesis about Mastercard's business that you can track over time rather than a single frozen estimate, all housed on Simply Wall St's Community page.
Community views on Mastercard are split between those who see a quality network on sale and those who think the payment giant already prices in a lot of good news.
Bull case: 26% undervalued
"It’s building settlement infrastructure and tools for "agentic commerce" around them instead of fighting the trend…"
Discover why this Narrative puts Mastercard at 26% undervalued.
Bear case: 6% overvalued
"Valuation premium: Mastercard trades around 30× forward earnings, above industry average (~22×), leaving little margin for error…"
Explore why this Narrative puts Mastercard at 6% overvalued.
Mastercard’s price is only one signal, insider moves are another
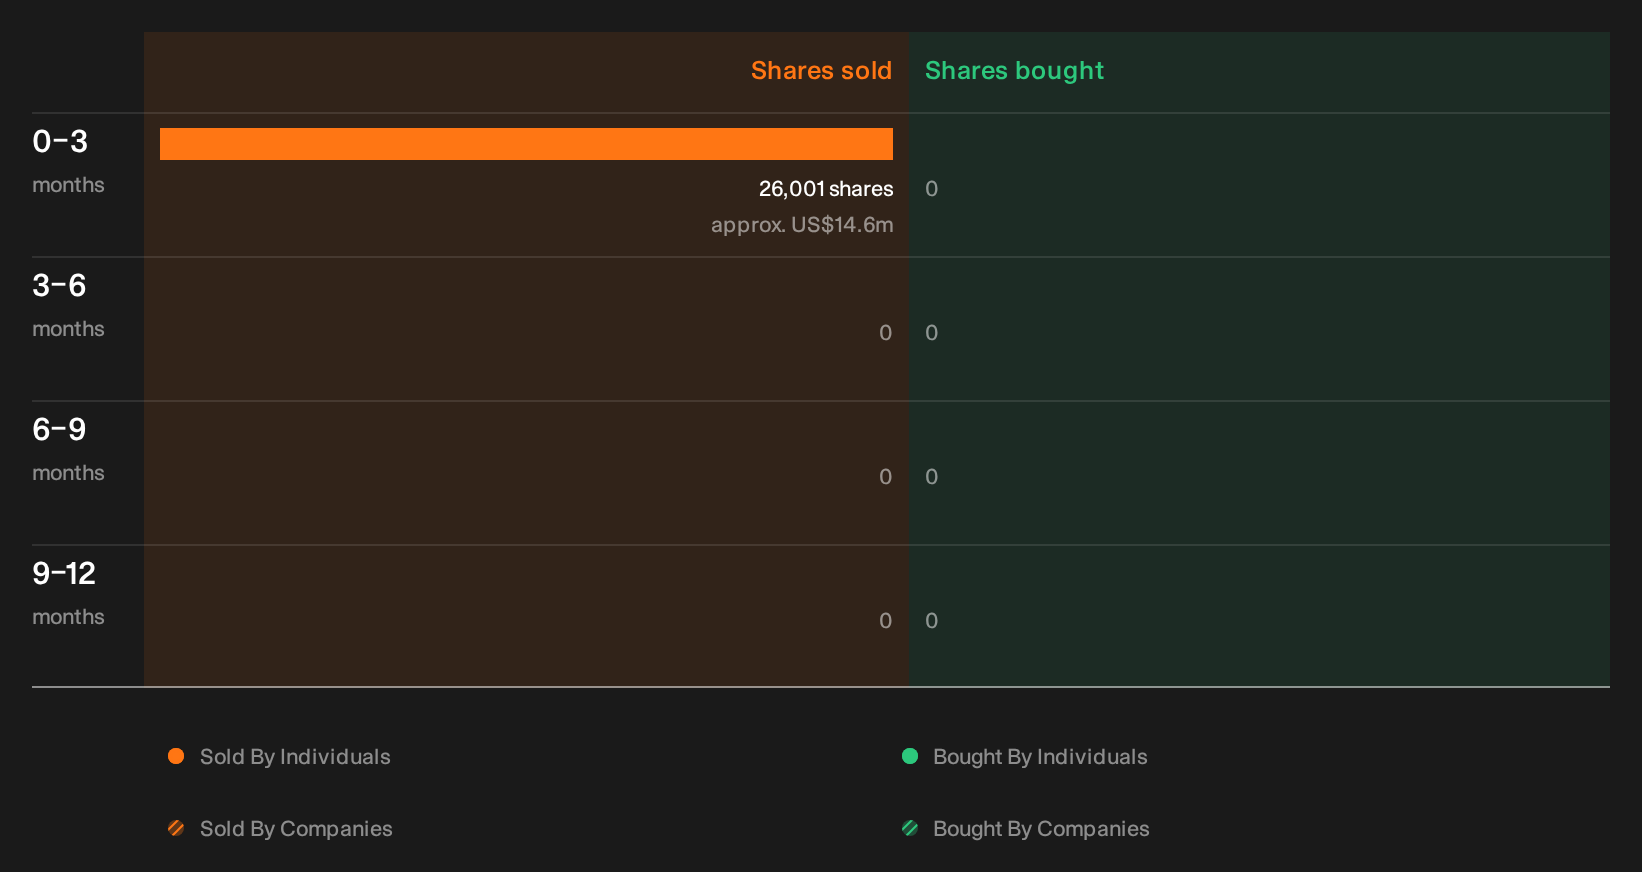
Before you focus only on Mastercard’s valuation story, it is worth knowing that recent trades by key insiders have been flagged by our checks and the identities, sizes and possible read through are all there for you to review. See the recent insider selling flagged for Mastercard.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com