
Carvana (CVNA) Stock May Trade At A Premium After Sales Growth News
Carvana has delivered a very large share price gain over the past three years, which now collides with a recent pullback and raises a simple question for you as an investor: Is the current US$62.54 price still supported by the earnings power that the business is generating today?
- The stock has returned roughly 7x over the past three years, which puts a lot of weight on whether the underlying earnings justify that kind of rerating.
- Recent commentary around accelerating vehicle unit growth and new reconditioning megasites suggests investors may be baking stronger future profitability into the valuation, which matters for how much you are really paying for each dollar of earnings.
- Your read on Carvana is one view; the desks covering it have another. See what analysts think Carvana's shares could be worth.
The stock's next move may depend on whether that recent share price level can be explained by Carvana's earnings when set against the Fair Ratio benchmark.
If you want a second reference point alongside Carvana's recent 3 year rerating, you can run the same earnings lens across 32 high quality undervalued stocks.
Does Carvana Look Pricey on Earnings?
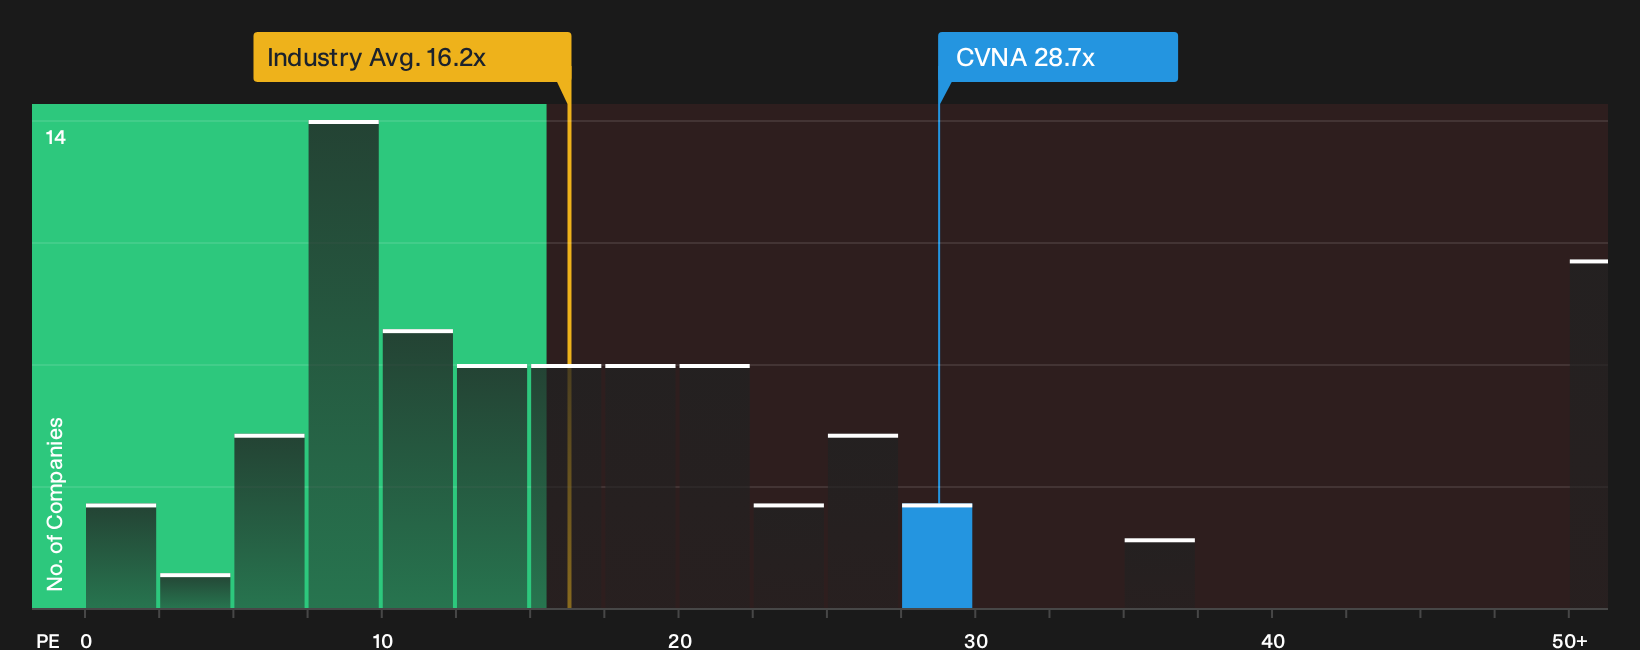
For Carvana, a P/E lens helps you anchor the share price directly to the earnings the business is already producing. The stock trades on a P/E of 28.7x, which is above both the Specialty Retail industry average of 16.2x and the wider peer group at 16.8x. That indicates investors are currently paying a higher price for each dollar of Carvana’s earnings than is typical across similar retailers.
The Fair Ratio benchmark, which adjusts for Carvana’s own growth profile, margins, size and risk, points to the current 28.7x multiple being overvalued rather than conservative. Because the recent news flow highlights stronger vehicle unit growth and upbeat sales expectations, some of this premium likely reflects optimism that current profitability can be built on, not just maintained. The key question for you is whether that richer multiple is justified by the earnings path you expect Carvana to deliver from here, or whether the stock leaves less room for disappointment than lower rated peers. Explore the numbers behind Carvana's P/E valuation.
The Carvana Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for Carvana by spelling out which combinations of future growth, profitability and earnings power would need to play out for today’s valuation to look either stretched or conservative. Each scenario ties its number to a specific view on where Carvana’s expansion, margins and key risks go next. This gives you a framework you can revisit as fresh information appears.
One of the top community narratives on Carvana: 25% undervalued
"The main thing that has to go right is Carvana executing its inventory and reconditioning expansion so that unit growth, delivery speed and unit economics stay aligned..."
Discover why this Narrative puts Carvana at 25% undervalued.
One more angle on Carvana that could change how you see this price
Earnings and narratives only tell part of the story for Carvana. Professional coverage also sketches where the business might be a few years from now, which gives you another yardstick to compare with today's valuation. Explore where analysts expect Carvana to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com