
Why Everyone Is Watching Bird Construction (TSX:BDT) Today
Bird Construction (TSX:BDT) is back in focus after second quarter revenue moved past $1b for the first time, reflecting a 22.6% year-over-year increase and a record $6.1b backlog.
Investors have been quick to react to Bird Construction's stronger order book and financing moves. The share price is at CA$82.03 after a 21.17% 1 month share price return and a 31.14% 3 month share price return, while the 5 year total shareholder return above 9x signals powerful long term momentum.
Scan other construction and infrastructure contractors showing similar backlog strength and revenue momentum with the curated list of solid balance sheet and fundamentals (7 results).
Bird Construction’s recent surge lines up neatly with higher revenue and a record backlog, not just a mood shift on the trading screen. The key issue now is how that strength stacks up against the current price tag.
Most Popular Narrative: 3% Undervalued
On the most followed view of Bird Construction, the CA$84.63 fair value sits only slightly above the last close at CA$82.03, so the recent rally already reflects much of the optimism baked into that model.
The company's strong balance sheet and liquidity, combined with an opportunistic approach to M&A, supports continued diversification into resilient, high-growth sectors and expansion of capabilities, positioning Bird to capture a greater share of major project opportunities and support multi-year revenue and adjusted EPS growth.
See why 172 investors see Bird Construction as 3% undervalued.
Result: Fair Value of CA$84.63 (UNDERVALUED)
Still, the bullish Bird Construction narrative depends on large capital projects staying on track, as well as on sector slowdowns not dragging out and pressuring margins.
Find out about the key risks to this Bird Construction narrative.
Another View on Bird Construction's Valuation
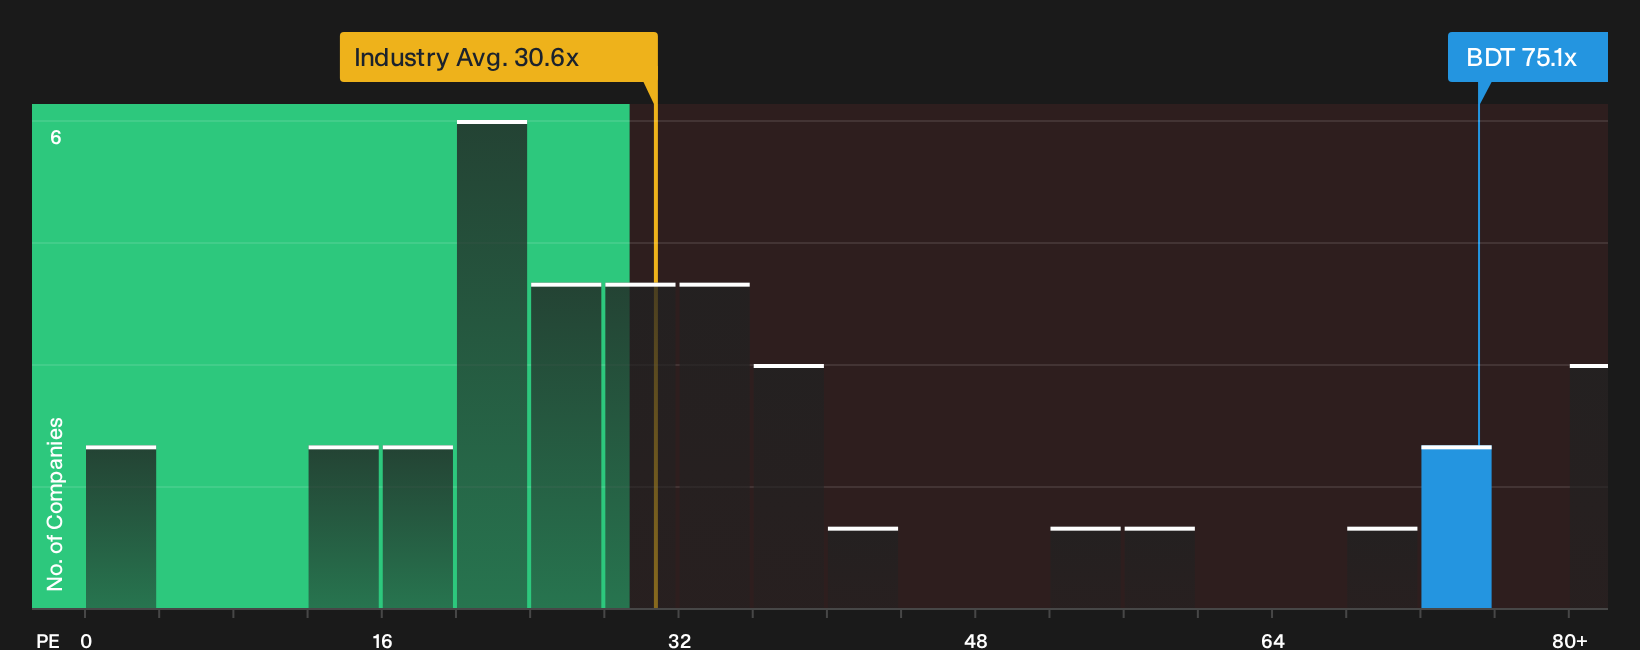
While the popular narrative frames Bird Construction as about 3% undervalued on a fair value of CA$84.63, the plain P/E comparison tells a much tougher story. The stock trades on 76.5x earnings, compared with about 30.6x for the wider North American Construction group and 29.1x for peers.
The fair ratio for Bird Construction is 54.8x. That is materially lower than the current multiple and suggests the share price could have less room for error if project execution, margins or earnings forecasts disappoint. The question for you is which valuation story feels more realistic for your risk tolerance.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Bird Construction's valuation story. If you want to move fast and cut through the noise, weigh both sides yourself with 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Bird Construction?
Do not stop your research with Bird Construction. Broaden your watchlist with fresh opportunities that match different goals, risk levels, and income needs.
- Target potential mispricing and look for quality companies trading below their implied worth with the 7 high quality undervalued stocks.
- Strengthen your income stream by scanning for reliable high yield payers that might complement Bird Construction with the 1 dividend fortresses.
- Dial down risk and focus on durability by reviewing resilient businesses that carry lower risk scores through the 7 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com