
Should Nuclear Power Deals Require Action From Vistra (VST) Investors?
- Vistra has grown its zero carbon power footprint through the completed Energy Harbor acquisition and secured long-term nuclear supply deals with hyperscalers including Amazon and Meta, while also participating in Helix Digital Infrastructure to support AI focused data centers.
- This mix of contracted nuclear output and involvement in AI oriented power infrastructure tightens the link between Vistra’s operating results and long-duration, data center driven electricity demand.
- We will now look at how Vistra’s investment narrative could shift as AI focused nuclear contracts reshape its long-term earnings mix.
Scan beyond Vistra and see which other power and grid operators are positioned for AI driven electricity demand with our hand picked 40 power grid technology and infrastructure stocks
Vistra Investment Narrative Recap
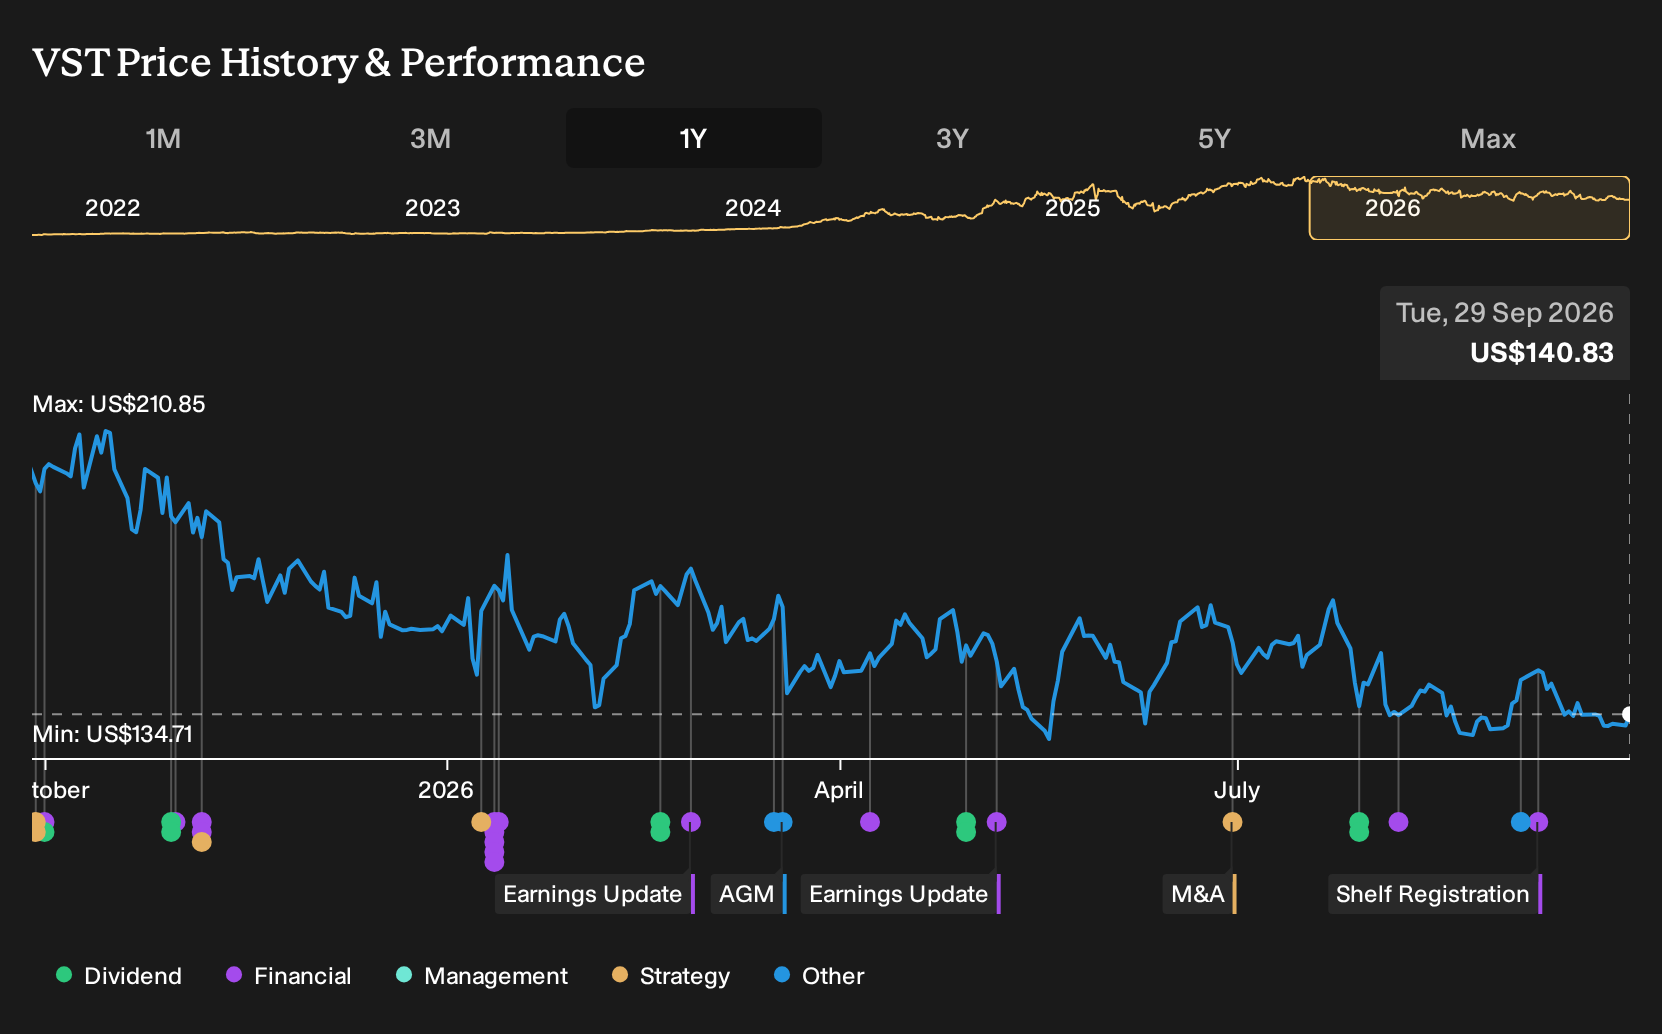
To own Vistra, you need to believe that rising power demand from AI and data centers will keep rewarding a large, integrated generation and retail platform that already serves about 5 million customers with roughly 44,000 megawatts of capacity. The near term swing factor is how effectively Vistra converts its new zero carbon footprint and long term hyperscaler contracts into steadier earnings, while still dealing with recent share price weakness.
The biggest operational risk remains execution under a heavy capital and debt load, especially as coal and gas assets face policy and cost pressure. Recent news around expanded nuclear contracting and AI linked infrastructure does not remove those issues, but it can improve revenue visibility if the plants keep running reliably and management avoids project delays or cost overruns.
The Energy Harbor acquisition and related contracts with Amazon and Meta sit right at the center of this story. These deals tie a larger zero carbon nuclear fleet to long dated, data center driven demand, which can give Vistra more contracted volumes and potentially smoother cash generation than a pure merchant exposure to volatile power prices.
For you as an investor, the key question is whether Vistra can use this nuclear and AI oriented shift to support its catalyst path. That path already leans on higher utilization, storage and renewables buildout, and capital returns. Execution still runs through disciplined spending, leverage management, and reliable operations at both legacy fossil plants and new assets that support AI focused data centers.
What Analysts Are Baking Into Vistra’s AI And Nuclear Shift
Analysts are effectively treating Vistra’s AI linked nuclear push as part of a broader step up in the scale and profitability of the business. Their current models point to Vistra generating about $25.8b of revenue and $4.0b of earnings by 2029, with earnings today sitting near $2.0b. That implies revenue growth of roughly 10.3% a year and an earnings increase of about $2.0b over that period.
Uncover why Vistra's fair value indicates a 57% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community shows 11 fair value views on Vistra, stretching from about $170.91 to roughly $464.08 per share. That spread reflects very different expectations around AI driven demand, nuclear execution, and balance sheet risk. Use these contrasting opinions as a starting point to explore multiple independent angles before deciding how Vistra fits your portfolio.
Explore 10 other Vistra fair value estimates, including one that suggests up to 235% potential increase from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vistra research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vistra. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vistra's overall financial health at a glance.
Looking For More Ideas Beyond Vistra?
Once you have formed a view on Vistra, it can help to widen the lens and compare it with other potential opportunities using the Simply Wall St Screener so you can see where the risk, income, and value profiles differ.
- If you want steadier balance sheets and fewer surprises, start with a 31 resilient stocks with low risk scores that may suit a more conservative approach.
- For investors who care most about robust finances and staying power, filter for a list of solid balance sheet and fundamentals (25 results) that can help anchor a portfolio.
- If you are hunting for mispriced opportunities with quality fundamentals, scan the 18 high quality undiscovered gems that the wider market may not be focused on yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com