
FactSet (FDS) Stock Jumps As Margin Strength Restores Confidence
FactSet Research Systems stock snapped a rough month with a sharp reset in mood. Shares climbed 3.9% to US$270.16 as investors latched onto one thing that cuts through the noise: the margin story.
Adjusted operating margin for the year landed at 34.5% while annual free cash flow reached US$707 million. That combination of healthy profitability and cash generation is what pulled sentiment back after a 14% slide over the past 30 days. The market is treating this as a margin and cash flow reaffirmation rather than just another earnings print.
Love FactSet Research Systems' 34.5% adjusted operating margin and US$707 million in free cash flow, but want a broader set of high quality cash generators on your radar? Screen for peers with similar profitability and balance sheet strength using our list of solid balance sheet and fundamentals stocks (25 results).
Q4 2026 Earnings Summary
- Revenue (Q4 2026 vs. Q4 2025): US$634.7m vs. US$596.9m (up about 6.3%)
- Net Income, Excl. Extra Items (Q4 2026 vs. Q4 2025): US$121.1m vs. US$153.6m (down about 21.1%)
- Basic EPS (Q4 2026 vs. Q4 2025): US$3.42 vs. US$4.07 (down about 15.9%)
- Adjusted Operating Margin (FY 2026 vs. prior year): 34.5%, compared with a 35.7% trailing net margin proxy (down about 1.2 percentage points)
Tired of chewing through earnings summaries and raw tables to piece together what really matters for FactSet Research Systems? Get the full picture in one visual dashboard that brings together the valuation angle in our company report for FactSet Research Systems.
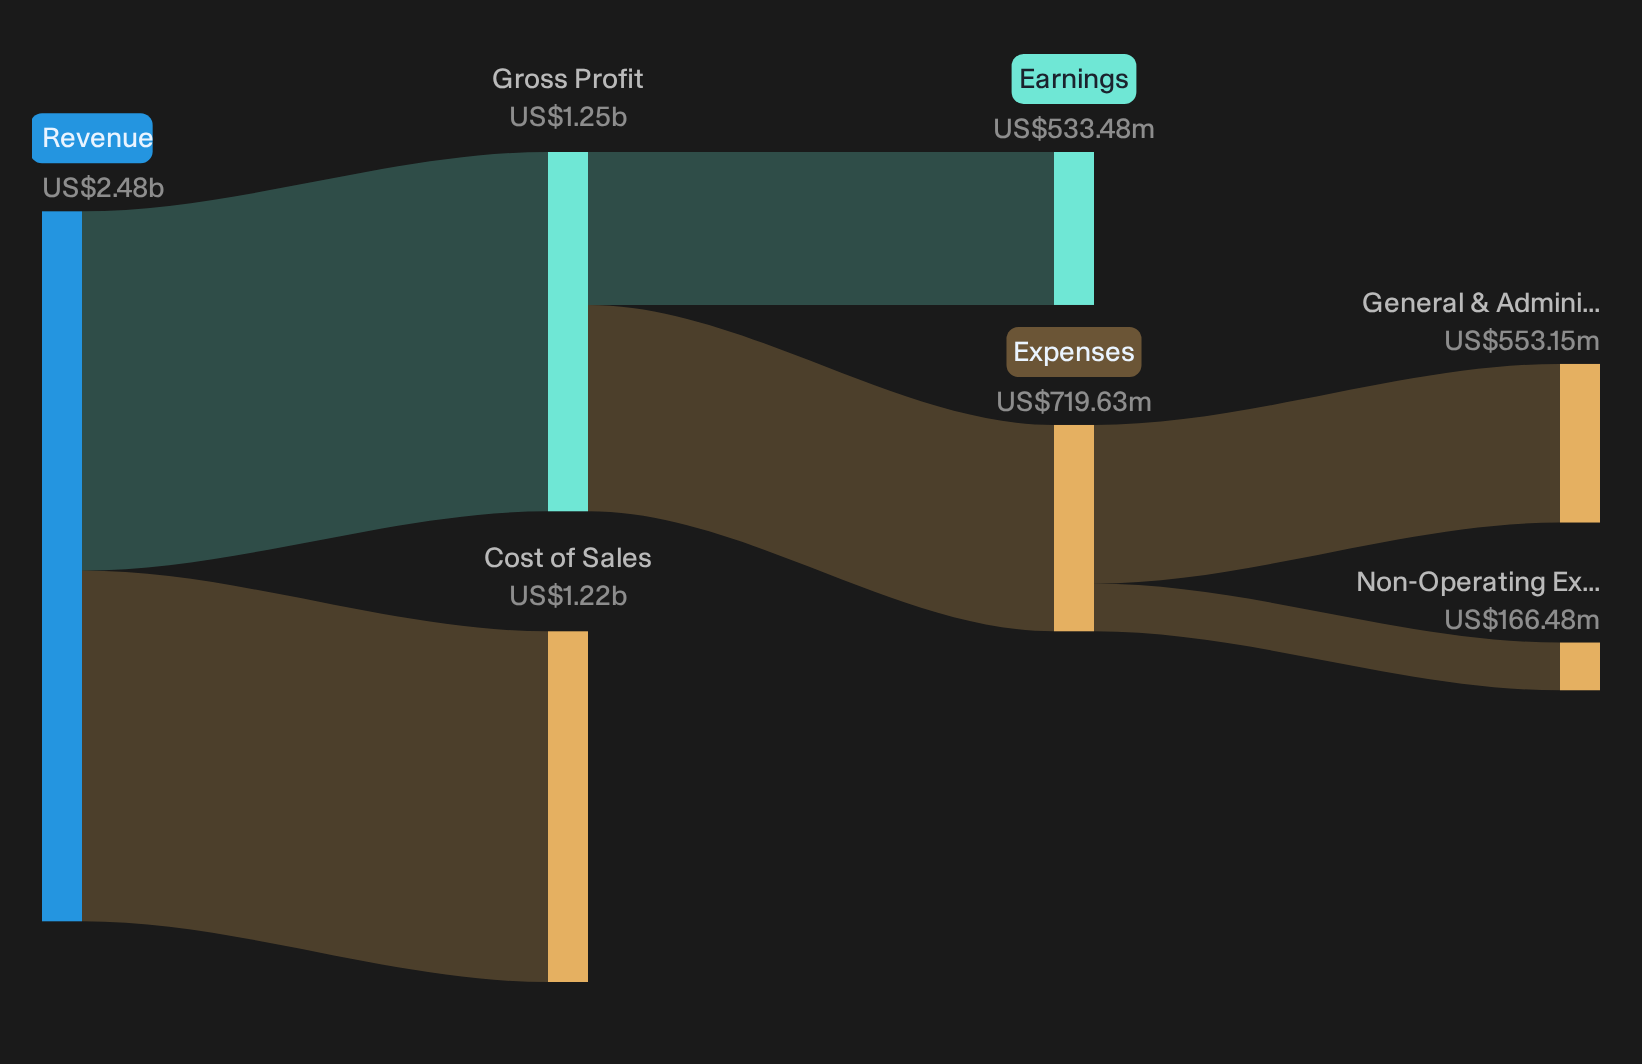
FactSet bull case leans on ASV and AI milestones
Bullish investors argue that FactSet can use AI, an open platform and broader workflow coverage to lift Annual Subscription Value and deepen recurring contracts. This quarter provides concrete markers. Organic ASV reached US$2.56b with 7% growth for FY26 and a record US$86m added in Q4, which aligns with the view that enterprise adoption is strengthening beyond smaller contracts.
AI is not just marketing language. Management reported that AI solutions contributed more than 10% of new Q4 ASV and that clients using these tools saw ASV expand at roughly twice the rate of others. That supports the idea that AI features can increase wallet share per client. Contract quality also moved in a positive direction, with ASV retention above 95% and average renewal terms about 30% longer, supporting the thesis of richer, longer subscription relationships across wealth, banking and broader portfolio workflows.
Reveal where the surface looks calm, but the models for FactSet Research Systems start to diverge over the next few years by accessing the full revenue, EPS and free cash flow analyst estimates for FactSet Research Systems.FactSet bear case zeroes in on margin strain
Cautious investors argue that FactSet will see pricing pressure, margin drag and lumpier renewals as AI competition intensifies and clients shift off the desktop. The latest quarter only partly undercuts that story. Organic ASV climbed 7% to US$2.56b with a record US$86m in Q4 and retention above 95%, so fears of broad renewal fatigue or deal slippage are not playing out in these numbers. Longer enterprise contracts and strong AI driven ASV suggest clients are leaning in rather than walking away.
Margin anxiety looks less settled. Adjusted operating margin for FY26 sits at 34.5%, slightly below the 35.7% proxy, and guidance only points to a modest 25 to 75 basis point lift in FY27 while investment in AI, cloud and content continues. That profile does not confirm a margin breakdown, but it also falls short of the clean operating leverage bears would need to abandon their thesis.
After a year in which FactSet Research Systems increased its investment in AI and accepted some margin compression, it is reasonable to ask whether this represents controlled spending or an early sign of structural cost creep that is being masked by strong ASV metrics. Review our independent risk analysis for FactSet Research Systems which shows 1 important warning signStay Ahead Of Your Next Move
If FactSet Research Systems' mix of strong free cash flow and AI driven ASV momentum has your attention, register for free with Simply Wall St and add it to your Watchlist to track price against fair value and wait for your preferred entry point. After you decide to take a position, keep the noise down and the signal high by managing your holdings through the Portfolio Command Center so you see only the updates that really matter. For a longer term lens, tap into thousands of viewpoints through the Community and see how other investors are interpreting the same data. Spot potential catalysts and emerging risks early so you can act faster and stay ahead of the market.
Seeking Fresh Alternatives Beyond FactSet?
Market leaders move first. Everyone else gets caught chasing old stories while the real breakout momentum quietly builds in fresh ideas under the radar for now. Consider researching new opportunities early.
- Identify resilient potential compounders early by scanning curated 31 resilient stocks with low risk scores before the broader market focuses on companies with stable earnings, strong balance sheets and quietly building momentum.
- Explore the AI infrastructure build out by reviewing 90 AI infrastructure stocks where revenue, capital investment and data center demand are influencing expectations for future cash flows.
- Review cash generative miners that may be on the cusp of sentiment shifts by examining 36 elite gold producer stocks while these producers remain relatively under the radar and before any changes in metal prices are fully reflected in valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com