
Conagra Brands (CAG) Stock Drops As Turnaround Progress Meets Trailing Loss
The market punished Conagra Brands on the headline, with the stock sliding about 5% to US$13.44, yet the quarter itself told a more complicated story. A packaged food group that many investors see as a slow, income-focused holding just put up Q1 earnings per share of about US$0.36 and reaffirmed its full year outlook while still sitting on a trailing loss of roughly US$1.9b. That clash between a firm intent on repairing its profitability and a share price drifting lower is the real tension running through this earnings print.
Love Conagra Brands for the income profile but worried about that trailing US$1.9b loss and sliding share price? Screen for food and consumer staples stocks that pair reliable dividends with cleaner balance sheets using our list of solid balance sheet and fundamentals stocks (25 results).
Q1 2027 Earnings Summary
- Revenue (Q1 2027 vs. Q1 2026): US$2,595.9 million vs. US$2,632.6 million (slight decline year over year)
- Net Income, Excl. Extra Items (Q1 2027 vs. Q1 2026): US$174.3 million vs. US$164.5 million (modest improvement in profitability)
- Basic EPS (Q1 2027 vs. Q1 2026): US$0.36 vs. US$0.34 (incremental earnings lift per share)
- Trailing Twelve Month Net Income, Excl. Extra Items (TTM Q1 2027 vs. TTM Q1 2026): loss of US$1.91b vs. profit of US$850.1 million (swing into sizeable cumulative loss over the past year)
If you prefer clear visuals instead of another page of dense earnings tables and footnotes on Conagra Brands, see the full picture of the business, including its valuation, in a simple dashboard via our company report for Conagra Brands.
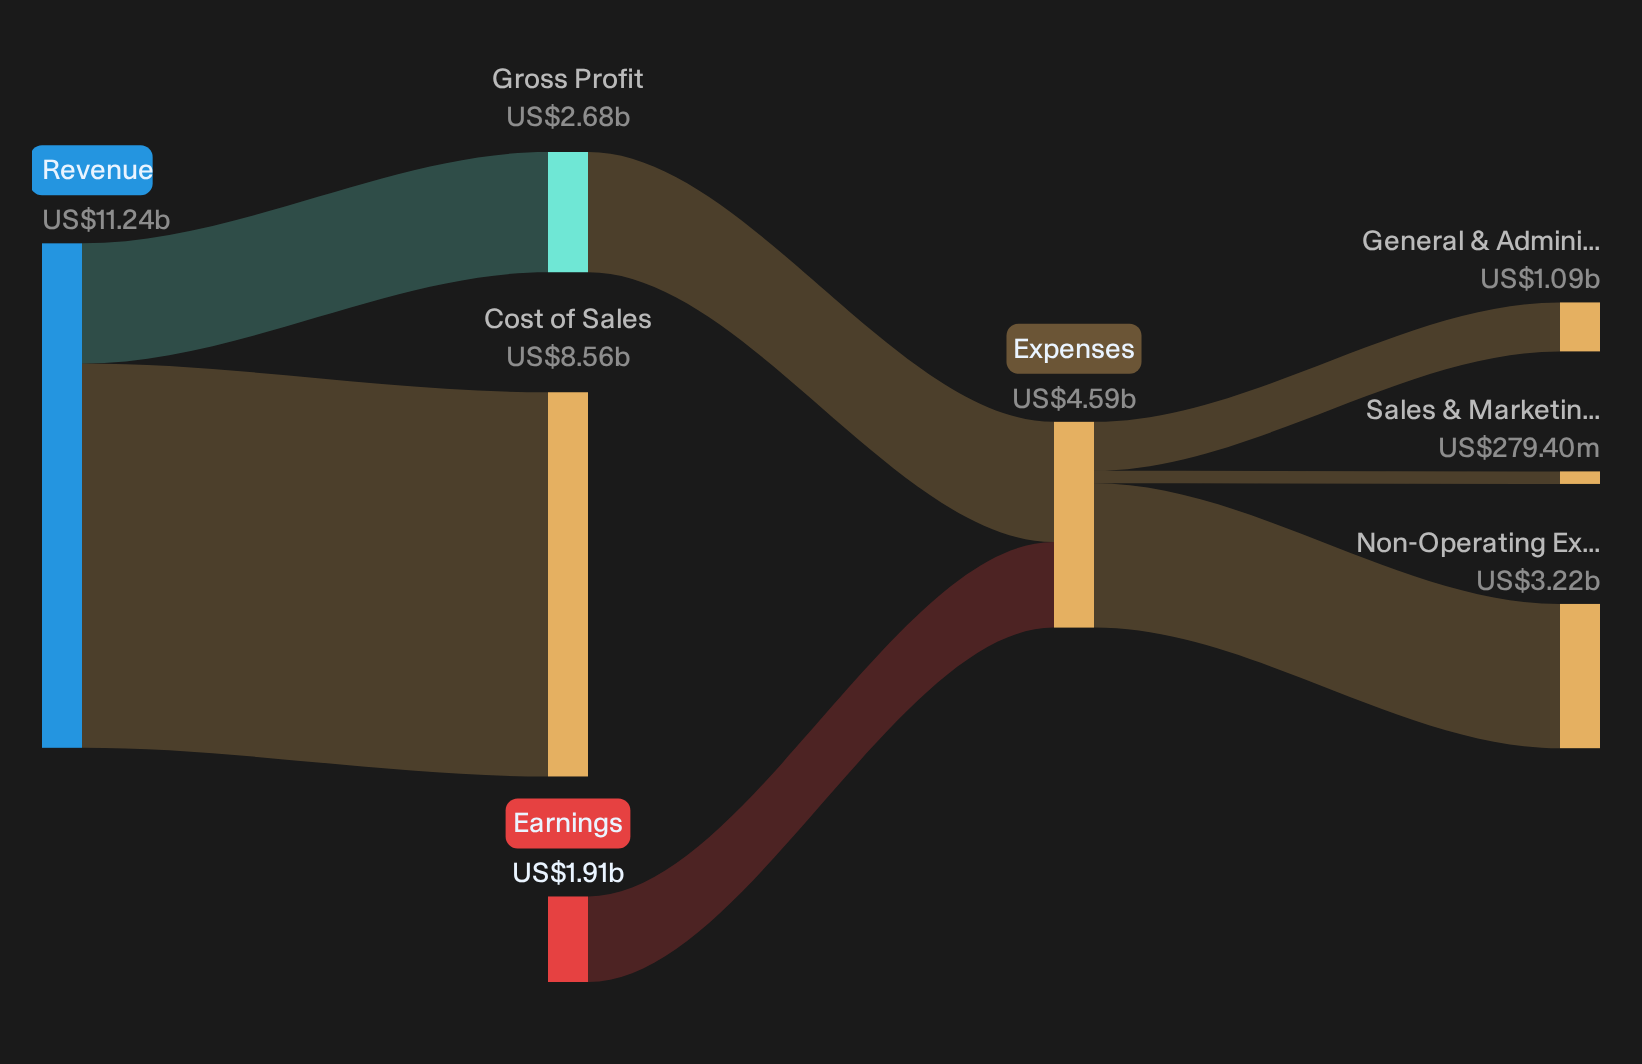
Evaluating Conagra’s Turnaround Milestones
Bulls argue Conagra Brands can reset earnings, rebuild margins and then let demand for convenient, health oriented meals do the heavy lifting. The first quarter gives partial proof. Adjusted EPS landed well above the prior US$0.28 consensus, and management held full year guidance despite a 1.4% net sales decline and weaker volumes in key frozen and snack lines. That supports the idea that pricing, promotion pruning and early portfolio work can offset softer shipments, at least near term.
The reset story also hinges on balance sheet repair and cleaner capital allocation. Here, concrete markers are showing up. Net leverage sits near 4x with a plan to pay down about US$250m of debt in FY27 and a dividend cut that management frames as credit positive. Those steps match the bullish claim that the turnaround is about earnings quality and leverage reduction, not just headline growth.
Access the analyst estimates for Conagra Brands to see where the consensus models quietly diverge on Conagra Brands, and where the street is really placing the odds on the next few years.Bear Case on Volumes and Dividends Gets More Fuel
Bears argue Conagra Brands is structurally exposed to weaker demand for packaged food, limited pricing power and a less secure income story. Q1 does not clear that bar. Organic net sales are guided to decline about 2% in Q2, and management is already modeling frozen volumes down roughly 10%. That lines up with concerns that consumers are drifting away from core categories and that pricing is costing units.
Margin resilience is another pressure point. Full year operating margin guidance is unchanged. However, Q2 is only expected to land in the high single digits while inflation is now skewed toward the top of the 5% to 6% range and transportation costs are rising. The dividend has already been cut in half and the stock has fallen about 16% over 30 days. For now, execution progress on marketing, SKU cuts and supply chain projects sits mostly in the future while the risks are visible in the current numbers.
After a dividend cut, rising costs and a share price that fell nearly 5% on the earnings reaction, it helps to know whether Conagra Brands has already surfaced the big problems or if more could be lurking off the balance sheet. Review our full risk analysis for Conagra Brands which shows 2 important warning signsStay Ahead Of Your Next Move
Conagra Brands just paired a reaffirmed outlook with a trailing loss and a sharp price reaction, which is exactly the kind of setup where timing matters. Register for free with Simply Wall St and add it to your Watchlist to track share price against fair value and spot an entry that fits your plan. After you build a position, manage everything through the Portfolio Command Center so you filter out noise and only see updates that actually affect your thesis. Over the long haul, compare your thinking with thousands of others through the Community and surface hidden catalysts or risks early so you can stay ahead of the wider market.
Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. Breakout moves, early momentum and quietly dropping valuations often get caught by those scanning under the radar for now. Do not wait. Get in early.
- Target resilient compounding by reviewing curated 31 resilient stocks with low risk scores that can help steady your portfolio when volatility spikes and capital is flying to perceived safety.
- Hunt for potential breakout yield by scanning our hand picked 7 dividend fortresses while payout strength and balance sheets still matter, before the crowd chases the headline yields.
- Spot future growth stories early by checking carefully filtered 18 high quality undiscovered gems while they remain underfollowed and pricing still reflects hesitation rather than full conviction.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com