
Elkem (OB:ELK) Could Be 8% Undervalued After Extra Carbon Allowances
Regulatory shift puts Elkem’s carbon costs in focus
Elkem (OB:ELK) just received 1.3 million additional free emission allowances under the EU Emissions Trading System, after Norwegian authorities corrected earlier unequal treatment versus comparable EU producers.
The decision also confirms that Elkem’s Norwegian plants will receive emission allocations aligned with EU peers for 2026 to 2030. This puts the group’s long term carbon cost exposure and competitiveness under closer investor scrutiny.
Investors have already been reacting to Elkem’s shifting carbon cost outlook. The share price is now NOK34.0, with a 90 day share price return of 8.97% and year to date return of 11.18%. The 1 year total shareholder return of 28.18% and 3 year total shareholder return of 73.78% point to momentum that has built over time rather than faded on the latest regulatory news.
Scan how Elkem’s regulatory shift compares with other materials players under pressure from carbon costs by running your eye over the 223 resilient stocks with low risk scores in this space.
Elkem’s sharp multi year return and fresh carbon relief now collide in the valuation debate. Is the recent climb about a stronger business footprint, or sentiment catching up to the new rulebook on costs?
Most Popular Narrative: 7% Undervalued
On the most followed view of Elkem, a fair value of NOK36.67 sits modestly above the last close at NOK34. The updated carbon allowances now plug into an already constructive earnings story rather than creating it from scratch.
Initiatives to supply the green transition, such as R&D in carbon capture, storage, and using biogenic materials, could enhance long-term revenue and net margins by meeting rising demand for sustainable products.
See why 20 investors see Elkem as 7% undervalued.
Result: Fair Value of NOK36.67 (UNDERVALUED)
Still, weak demand in China and the EU, as well as any disruption from the Silicones review, could quickly challenge Elkem’s higher margin narrative.
Find out about the key risks to this Elkem narrative.
Another view on Elkem’s valuation
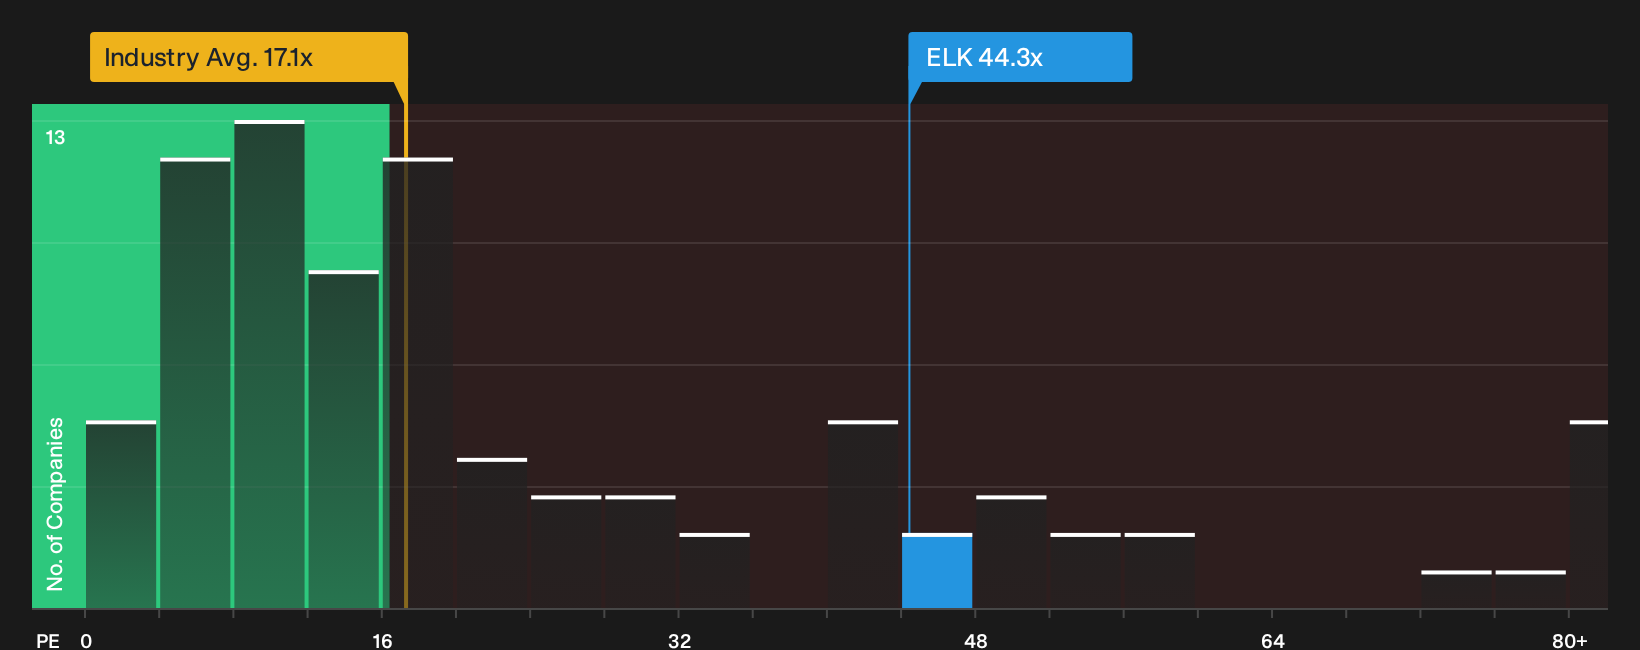
Elkem may look modestly undervalued against the NOK36.67 fair value, yet the current P/E of 44.3x is high compared with the European Chemicals average of 17.1x. The fair ratio of 63.2x points to a wide valuation range that raises real questions about how much risk you want to pay for.
See what the numbers say about this price in our valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Elkem is mixed, with both clear concerns and real bright spots. It may be helpful to move quickly and test the narrative against the underlying data yourself. To see the balance of potential upsides and red flags in one place, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Elkem?
If Elkem’s story has sharpened your thinking on carbon costs and valuation, you can broaden your watchlist with a few focused screens that highlight different angles on opportunity.
- Target potential mispricing by scanning the 192 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Strengthen your income stream by reviewing the 156 dividend fortresses that aim for higher yields without ignoring balance sheet quality.
- Protect the downside first by filtering for the list of solid balance sheet and fundamentals (205 results) so you are not the last one to notice financial strain.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com