
4DMedical (ASX:4DX) On Its Board Reset And Why The Valuation Debate Persists
Board and governance changes at 4DMedical
4DMedical (ASX:4DX) has put board and governance reform in the spotlight after proposing a higher employee share scheme cap and confirming a wide ranging refresh of its leadership group at the upcoming AGM.
The proposal includes lifting the employee share scheme issue cap to 10% under section 1100V of the Corporations Act, alongside appointing Julian Sutton as Executive Chair and adding respiratory medicine expert Professor Christine Jenkins AM to the board.
Recent trading suggests investor interest in 4DMedical is picking up, with a 24.27% 1 month share price return and a 4.17% 1 day move following the governance update, while the share price return year to date is still down 6.39% and the 3 year total shareholder return is around 8x.
Scan how 4DMedical’s governance reset compares with other health-focused small caps by reviewing the hand-picked 7 healthcare AI stocks already attracting attention.
After a sharp one-month rebound, but with a year-to-date share price that is still down, 4DMedical now forces a choice: lean into the governance reset today or wait for a cleaner entry based on the numbers.
Most Popular Narrative: 3% Undervalued
Analysts following 4DMedical see fair value at A$4.37 against a last close of A$4.25, which leaves a slim discount and puts the focus on whether its growth plans can justify that gap.
The acquisition and integration of Imbio and partnerships with major players like Philips, alongside a strong portfolio of technologies, are expected to enhance 4DMedical's market presence, leading to increased revenue from expanded market share and product distribution. Recent FDA approvals and Medicare reimbursements for key products like IQ-UIP are set to catalyze revenue growth by facilitating wider adoption and insurance coverage, potentially boosting net margins as more high-margin services are provided.
See why 52 investors see 4DMedical as 3% undervalued.
Those projections sit on a detailed framework. The most followed narrative assumes revenue growth of 142.4% a year over the next three years, profit margins swinging from a current loss position to 21.2%, and earnings reaching A$21.3m by around September 2029 from a reported loss of A$204.4m today.
To line up with that view, you would also need to be comfortable with 4DMedical trading on a P/E multiple of 188.7x those 2029 earnings, compared with 57.0x for the wider Australian Healthcare Services group, and with analysts modelling around 7% annual share count growth over the next three years as further capital is raised.
The A$4.37 fair value rests on discounting those future cash flows at 7.94%, so any change in growth, margins or dilution that is different to those inputs would quickly change the implied upside from the current A$4.25 share price.
Result: Fair Value of A$4.37 (UNDERVALUED)
Still, the narrative leans heavily on future funding and significant execution on new products, so any stumble on cash runway or CT:VQ rollout could quickly reshape sentiment.
Find out about the key risks to this 4DMedical narrative.
Another view on 4DMedical’s valuation
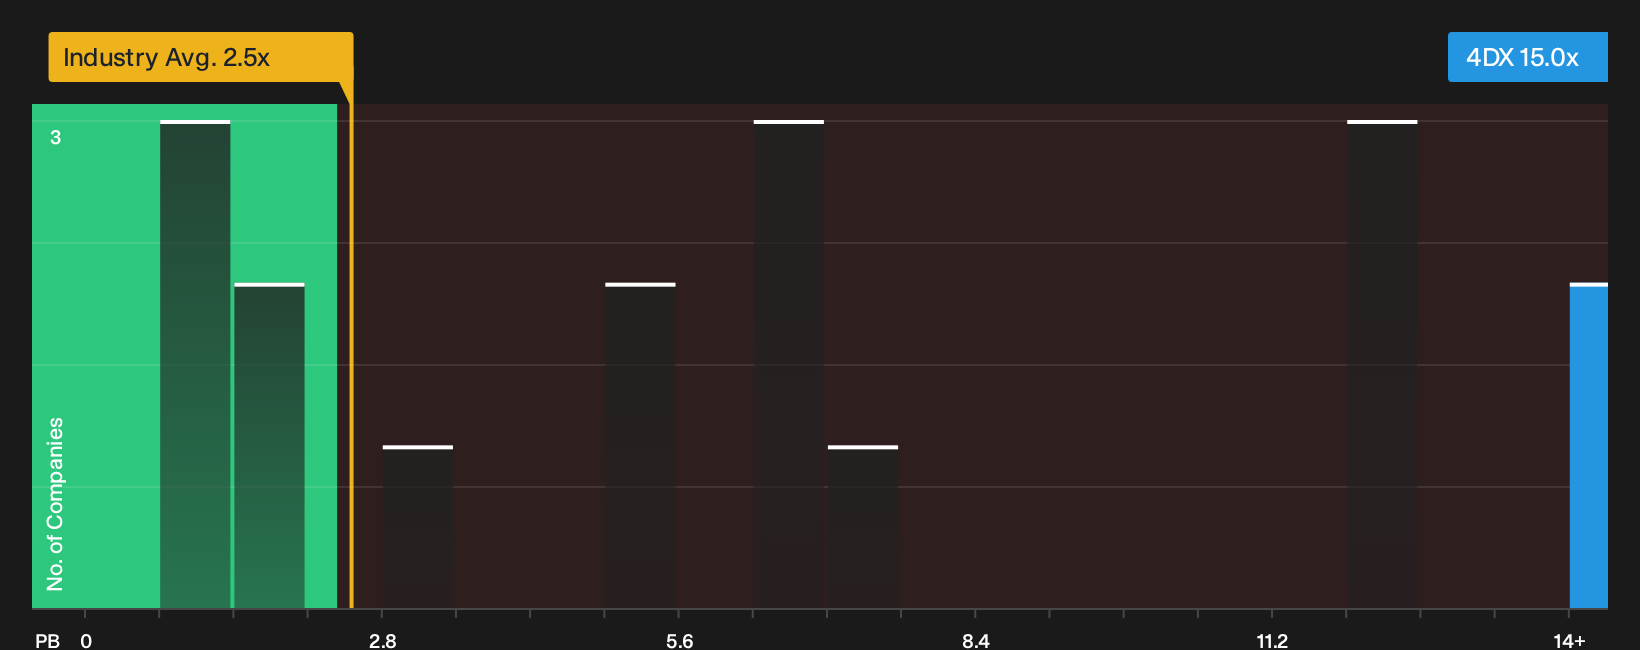
On simple price to book terms, 4DMedical screens as expensive, trading on a P/B of 15x against 13.5x for local peers and 2.5x across the global Healthcare Services group. That is a steep premium for a business that is still loss making and carries valuation risk if expectations reset.
For a fuller sense of how that premium could compress or persist as the story plays out over time, it helps to step through the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on 4DMedical so far. If you want to move quickly and base your stance on the numbers rather than the story, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond 4DMedical?
If 4DMedical has sharpened your focus on opportunity and risk, do not stop here. Use Simply Wall Street’s screeners to help identify your next potential candidate for further research.
- Target income first and scan dependable payers using the 3 dividend fortresses with yields that could matter for your portfolio.
- Search for quality at a discount by sorting through the 15 high quality undiscovered gems that combine solid fundamentals with limited market attention.
- Prioritise resilience and aim to reduce portfolio stress by filtering for the 7 resilient stocks with low risk scores that score well on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com