
What You Can Learn From WEBTOON Entertainment's 39% Drop
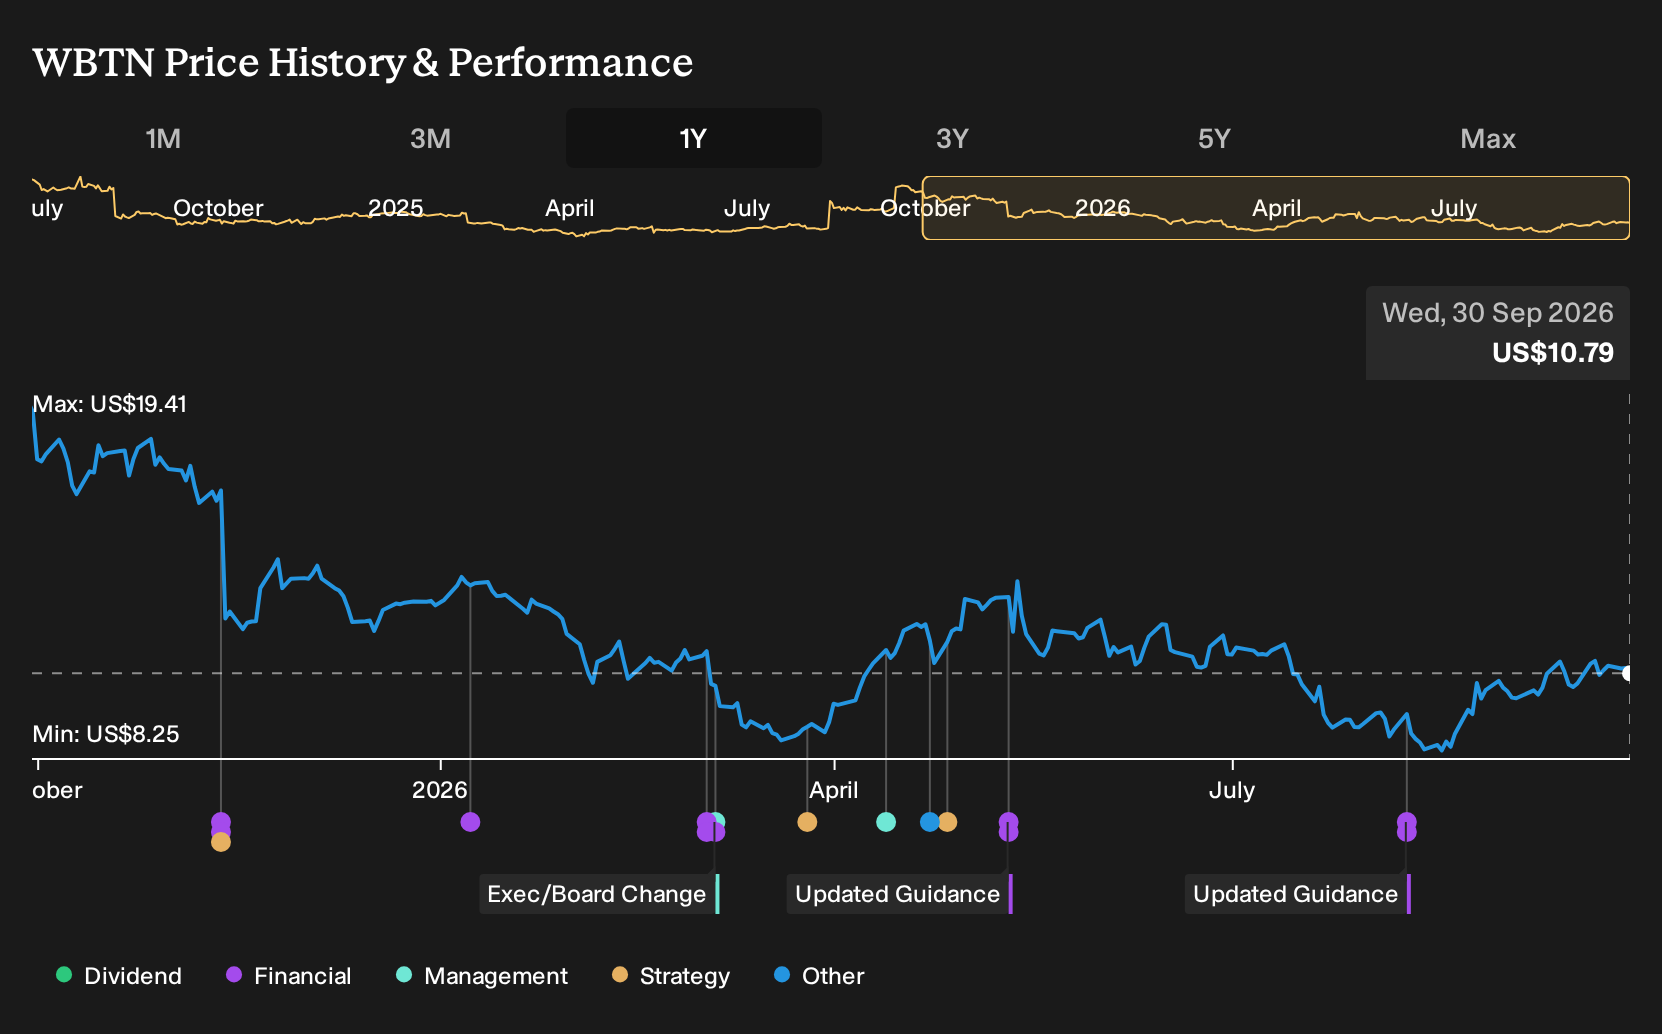
WEBTOON Entertainment’s Q1 2026 report looked mixed on the surface, with revenue slightly weaker than expected but earnings per share comfortably ahead of forecasts. Investors who held WEBTOON Entertainment over the past year are down 39.3%, including dividends. If you had invested just after analysts set out sharply different fair values and earnings paths in late 2025, how should you now interpret that decline in light of WEBTOON’s push into Disney-backed content, AI tools, and a growing IP and gaming pipeline?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
WEBTOON Entertainment has already moved. See which of 31 high quality undervalued stocks still trade below our estimates.
The Argument WEBTOON Investors Were Weighing Up
The shares cost US$19.41 at the start of the period, and investors in WEBTOON Entertainment were effectively choosing between two very different stories about what that price implied.
The bullish narrative pointed to a fair value of US$22.25, built on the idea that revenue could climb 17.3% a year and that margins might shift from a loss into a 5.4% profit, helped by Disney-backed content and a richer IP pipeline.
The more cautious view put fair value at US$17, assuming 14.0% annual revenue growth but only a 1.7% profit margin and raising concerns that slowing MAUs, regulatory bans, and rising content costs could keep pressure on profitability.
What The Results Changed For WEBTOON Entertainment
WEBTOON Entertainment’s Q1 2026 update showed adjusted EPS of US$0.07 ahead of expectations and stronger adjusted EBITDA, which leaned toward the bullish case that assumed improving profitability. At the same time, Q2 2026 revenue slipped to US$338.5m from US$348.3m and the net loss deepened, with net margin falling from 1.3% to 4.5%. Overall, the evidence cut both ways.
The key assumption investors can test elsewhere is the path to better margins. Track whether rising spending on content, creator tools, AI features, and IP or gaming deals is followed by a smaller loss or a clear move into profit, not just higher sales.
What WEBTOON’s Fall Asks You To Believe Today
WEBTOON Entertainment now trades at US$10.79, after a 39.3% loss over the past year, while this Narrative’s Fair Value sits above the current price based on its own assumptions.
The Narrative leans on Disney-backed series, a mobile-first format, and cross-media IP deals. A buyer today would need to believe those levers can offset rising costs, regulation, and digital fatigue.
"Exclusive Disney partnership and product innovation position WEBTOON for accelerated global user growth, compounding revenue, and superior industry validation. Unique mobile-first, creator-driven ecosystem and cross-media IP adaptation provide structural advantages for monetization and long-term margin expansion over traditional publishers."
The price and this Narrative do not agree. → Uncover what this Narrative says WEBTOON Entertainment is actually worth
Another Route Into Streaming Economics
WEBTOON Entertainment asks you to think about content first. One step away, another platform treats streaming mainly as a cash machine.
This other business leans on pricing, ads and buybacks instead of raw subscriber momentum. It chases steady surplus cash, not just audience records or buzz.
That focus turns minor product tweaks into serious tests of staying power. Each adjustment in pricing or ad load must support long run cash production.
If that model keeps deepening, the stock question evolves. You stop asking whether streaming works and start asking what you really pay for that cash engine.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com