
WuXi XDC Shares In Focus After Singapore Plant Approval
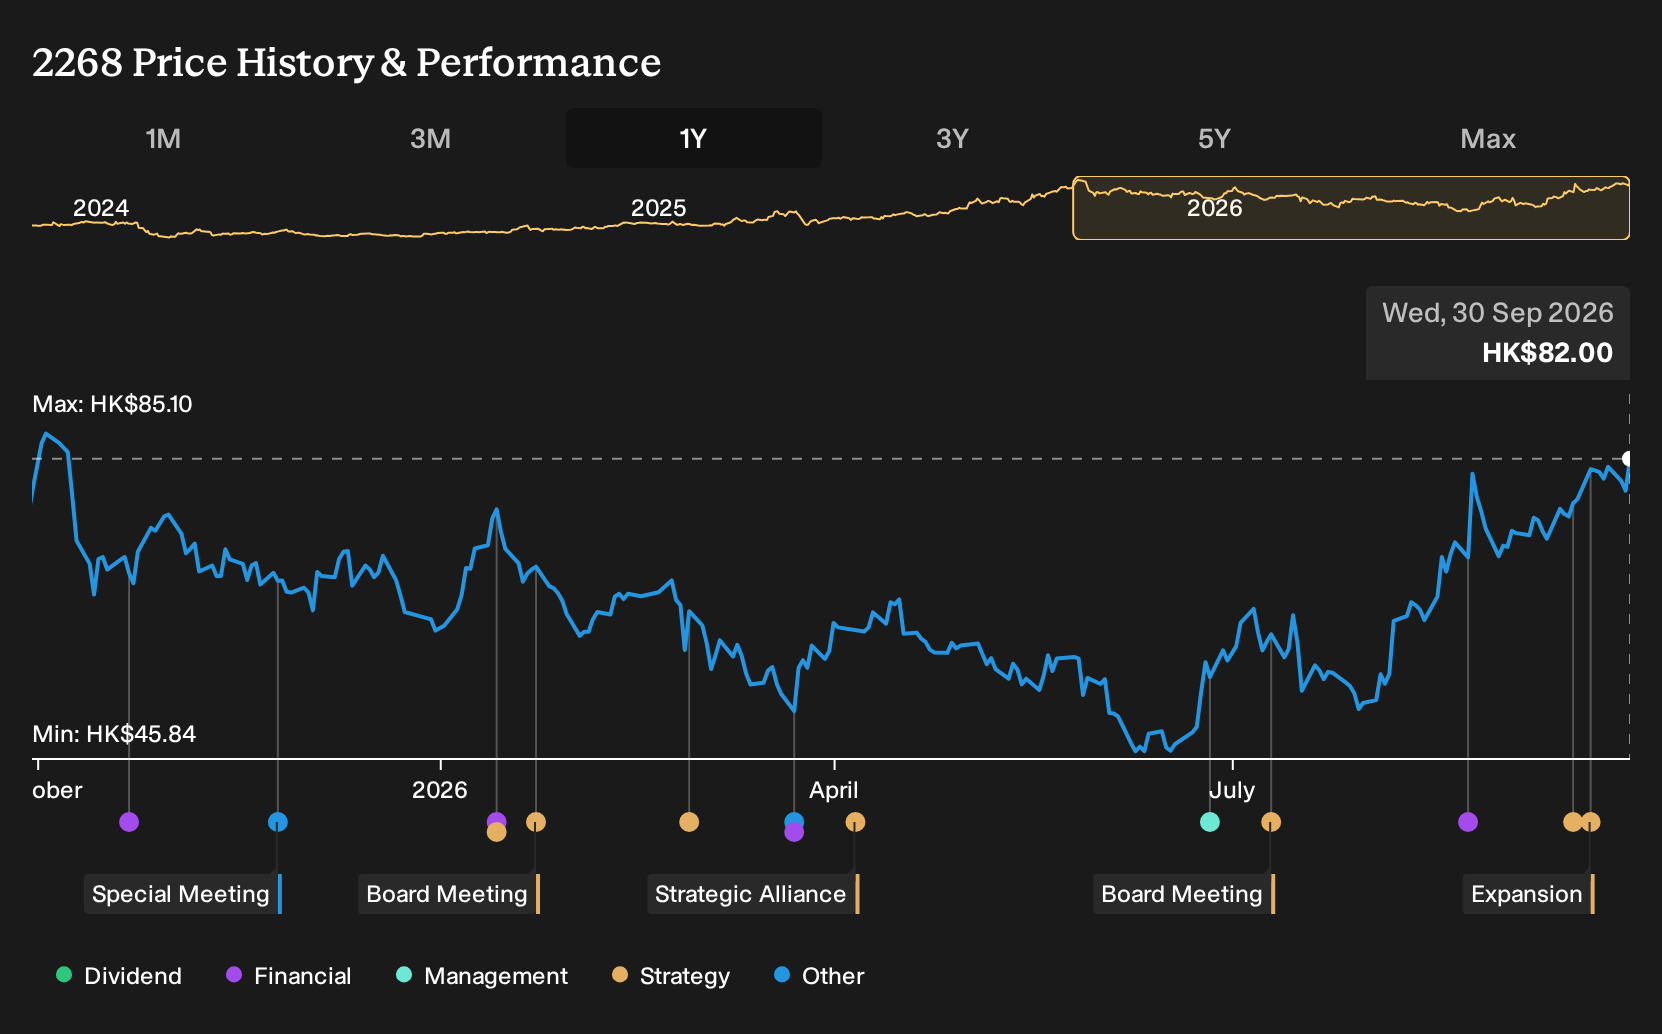
- WuXi XDC Cayman recently secured GMP release for its 25,000 square meter Singapore site, activating dual function BCM3 and DP4 lines that support end to end commercial manufacturing of antibody intermediates, conjugated drug substances, and bioconjugate drug products under FDA, EMA, NMPA, and HSA standards.
- Ona Therapeutics announced a second out licensing deal for WuXi XDC Cayman's WuXiTecan 2 payload linker platform, reinforcing demand for the firm's proprietary ADC technology and integrated CMC support as clients look for external partners to handle increasingly complex bioconjugate programs.
- We now examine how WuXi XDC Cayman's investment narrative evolves as the Singapore GMP release expands commercial bioconjugate capacity.
Scan WuXi XDC Cayman's peers by reviewing list of solid balance sheet and fundamentals (205 results) that could support large scale bioconjugate or ADC programs with similar end to end manufacturing depth.
WuXi XDC Cayman Investment Narrative Recap
For a shareholder in WuXi XDC Cayman, the core belief is that complex antibody drug conjugate and bioconjugate work will keep filling a broad, high value CRDMO platform. The Singapore GMP release fits that story because it adds commercial scale capacity and links into existing Chinese facilities, which matters if clients want global networks and late stage support.
In the near term, the key swing factor is how quickly new production lines move from qualified to meaningfully utilized. The same Singapore build out also sharpens the biggest risk. If ADC and XDC demand or project conversions lag existing backlog expectations, those extra square meters can weigh on margins instead of helping them.
The recent WuXiTecan 2 out licensing with Ona Therapeutics is the announcement that connects cleanly to this capacity story. Platform uptake from an external biotech helps show that WuXi XDC Cayman is not only selling space but also proprietary payload linker technology tied to recurring CMC work across the project life cycle.
For catalysts, that kind of deal points toward a pipeline of fee streams linked to a larger reported backlog of US$2.2b, while still carrying operational risk if client programs stall or shift focus. Execution on these licensed ADC projects, plus timely PPQ runs through Singapore, will do more for earnings quality than any near term share price move.
WuXi XDC Cayman's narrative links analyst expectations of CN¥15.6b in revenue and CN¥3.9b in earnings by 2029 to a 30.9% yearly revenue growth rate. This implies that earnings today of about CN¥1.6b would need to rise by roughly CN¥2.3b over that period.
Uncover why WuXi XDC Cayman's fair value indicates a 12% potential upside to its current price before that discount to fair value closes.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster in a tight band between 92.10 and 102.42, so opinions already span a meaningful gap around WuXi XDC Cayman. You now need to weigh those views against capacity ramp risks in Singapore and the ADC deal pipeline, then compare several alternative viewpoints before deciding.
Explore 2 other WuXi XDC Cayman fair value estimates, including one that suggests it could be worth just HK$92.10.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your WuXi XDC Cayman research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for WuXi XDC Cayman. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WuXi XDC Cayman's overall financial health at a glance.
Looking For More Investment Ideas Beyond WuXi XDC Cayman?
If you want to balance your view on WuXi XDC Cayman with fresh ideas, use the Simply Wall St Screener to sift for other businesses that match your risk, income, and quality preferences in a structured way.
- If capital preservation is high on your list, scan a 224 resilient stocks with low risk scores that may offer steadier profiles to anchor your portfolio.
- If income is your priority, review a 156 dividend fortresses that focus on higher yield payouts that still clear basic quality checks.
- If you are hunting for underappreciated opportunities, sort through a 617 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com