
Two Stories Ran On RH. The Harder One Was About Cash Not Growth
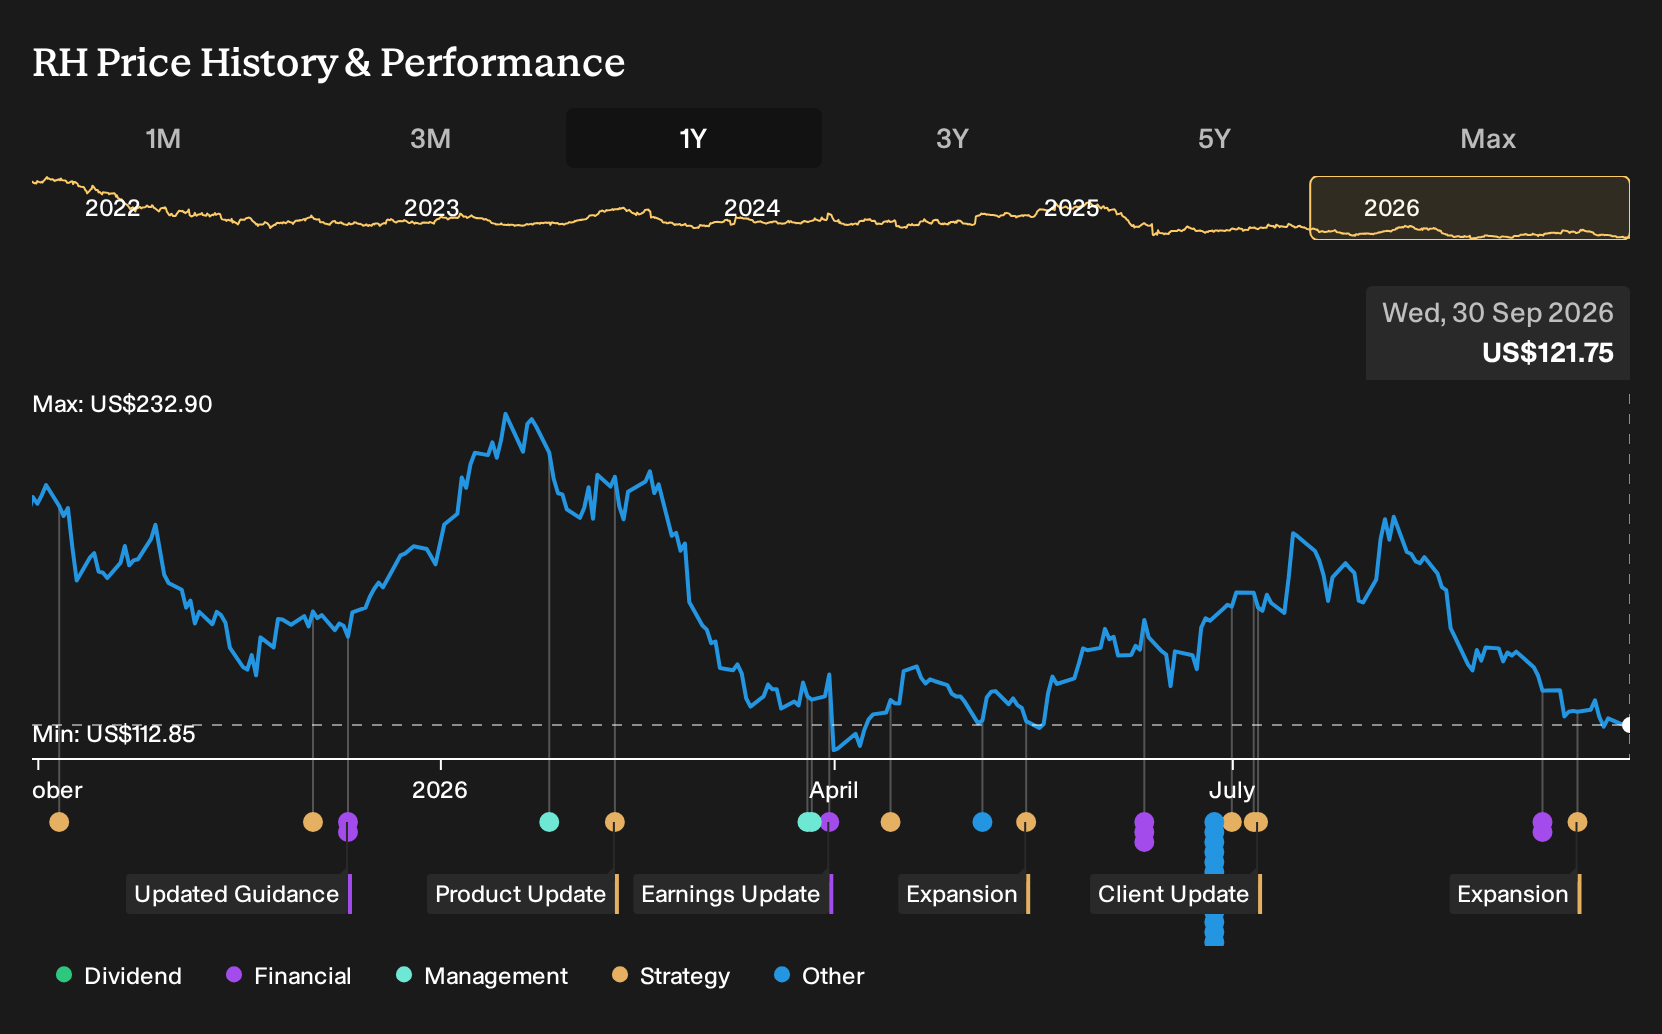
If you backed RH for its push into European galleries, new Sourcebooks and asset sales, the past year has been rough. Investors who held RH over the past year are down 39.4%, including dividends. If that decision sat on a belief that new Design Galleries, tariff management and real estate monetization would steadily lift earnings and margins, which of those specific expectations looks most at odds with what actually played out?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind RH. Zero in on 31 high quality undervalued stocks for companies trading below our estimates.
The Argument RH Investors Were Really Weighing
The shares cost US$203 at the start of the period, and anyone buying RH then had to decide which story felt more realistic.
The bullish narrative saw a fair value of US$257, built on RH opening 7 Design Galleries and 2 Outdoor Galleries in 2025 and rolling out new Sourcebooks to support revenue and margin ambitions.
The bearish view put fair value at US$179 and focused on the strain from US$2.2b of stock repurchase debt, along with international expansion costs expected to cut operating margins by 160 to 200 basis points.
What The Results Changed For RH
RH launched its ultra luxury RH Estates brand and continued expanding galleries, which supported the bullish case for platform and product expansion. Over the same period, revenue rose from US$899.2m in Q2 2026 to US$922.2m in Q2 2027 and net income increased, with net margin moving from 5.8% to 6.5%. The evidence was mixed on timing but consistent in direction.
The key lesson is simple. When an investment thesis depends on higher margins rather than just opening more stores, track the reported net margin and not only the top line or new concept launches.
What RH's New Price Is Really Asking You To Believe
RH trades at US$122 today, after the stock fell 39.4% over the past year. The selected Narrative sees Fair Value above the current price, based on a case built around higher end galleries, new sourcebooks and monetizing real estate and inventory.
At this lower level, any buyer is effectively judging whether RH can turn those expansion and asset sales plans into steadier cash flow and healthier margins, despite housing and tariff pressure.
"Asset monetization, including real estate and inventory, aims to boost cash flow, reduce debt, and strengthen net margins. Tariff uncertainties, housing market risks, and significant debt from stock repurchases may strain RH's margins and slow revenue growth amid volatile conditions."
One Narrative disagrees with today's price. → See where this Narrative says RH should trade
Where Could You Get There Earlier?
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 37% below our estimate - turns industrial reshoring and data center demand into higher-value modular projects.
- Company 2 - 48% below our estimate - advises when complex products fail under stricter testing and safety enforcement pressures.
- Company 3 - 41% below our estimate - wins large-scale work constructing data-centric infrastructure for major building programs.
Three companies from the same screener. Open all 25 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com