
Murphy Oil (MUR) Tracks Higher Oil Prices, Is It Still Below Fair Value?
Elevated oil prices linked to geopolitical risks in the Middle East have pushed investors back toward producers with leverage to crude. Murphy Oil (MUR) offers that exposure across North America and international offshore projects.
Recent trading has been supportive for Murphy Oil, with the share price at US$37.02 and a 90 day share price return of 16.12%, which feeds into a 1 year total shareholder return of 30.22%, even though the 3 year total shareholder return is mildly negative.
Scan for other oil and gas producers with similar crude exposure and balance sheet strength using our curated list of list of solid balance sheet and fundamentals (25 results) as you assess Murphy Oil's position.
Murphy Oil now trades at a discount to both analyst targets and one estimate of intrinsic value after a strong recent run. Is that a sensible margin of safety, or a warning that the market sees risks you should not ignore?
Most Popular Narrative: 7.3% Undervalued
With Murphy Oil last closing at $37.02 against a narrative fair value of $39.93, the current pricing gap puts the focus squarely on whether its offshore and North American projects can justify that difference under a 7.24% discount rate.
Significant exploration and appraisal activity across the Gulf of Mexico, Vietnam, and Côte d'Ivoire is poised to potentially add substantial new reserves and long-lived, high-margin production. This may support long-term revenue growth and future cash flows as global energy demand rises. Production outperformance and improved well productivity in core onshore assets (Eagle Ford and Tupper Montney), driven by optimized completion designs and operational efficiency, suggest higher sustainable production rates and lower costs, with a positive impact on net margins and earnings resilience.
See why 14 investors see Murphy Oil as 7% undervalued.
Result: Fair Value of $39.93 (UNDERVALUED)
Still, heavy offshore exposure and high capital spending needs mean that any drilling setback or weaker cash generation could quickly challenge this Murphy Oil valuation story.
Find out about the key risks to this Murphy Oil narrative.
Another View: What Multiples Say About Murphy Oil
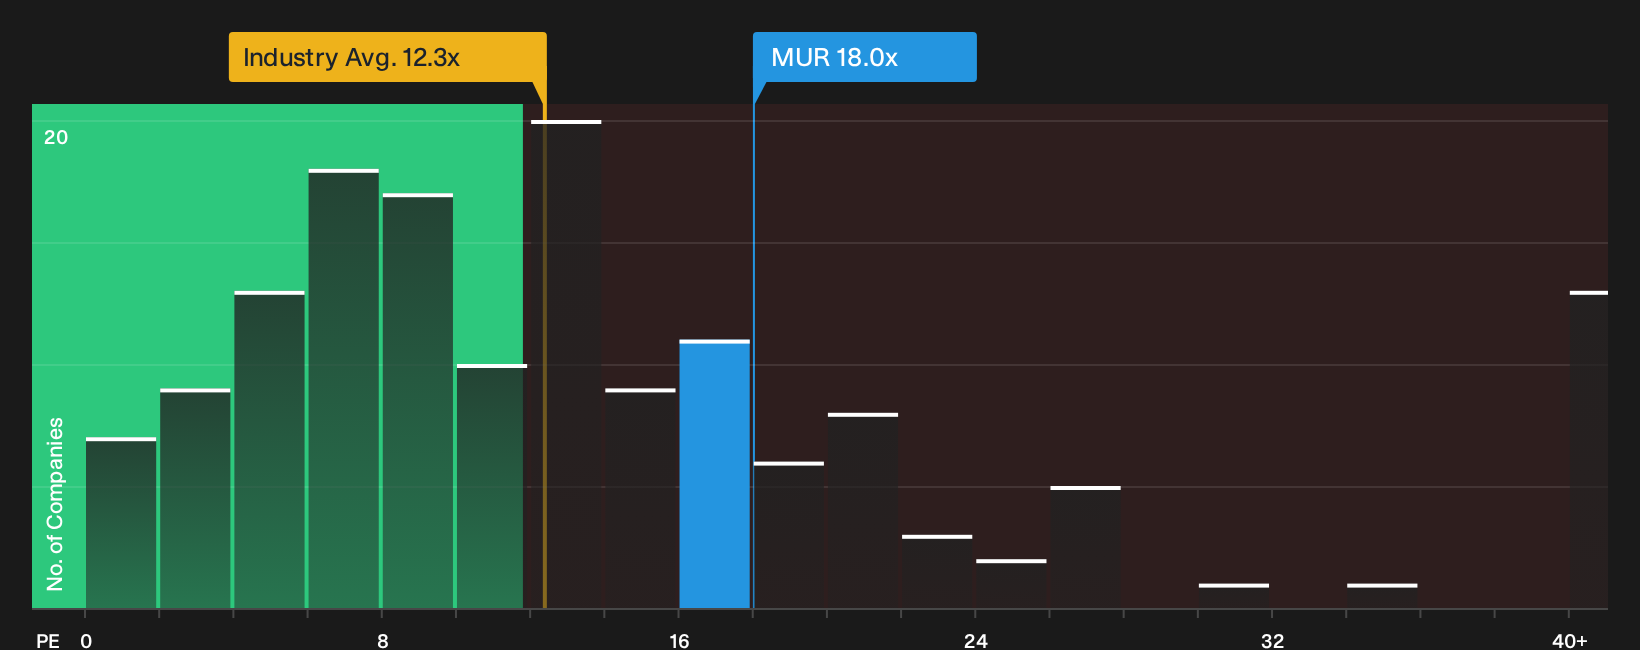
The narrative fair value suggests Murphy Oil is undervalued, yet the current P/E of 18x tells a more cautious story. That level sits above the US Oil and Gas industry on 12.5x and almost double peers on 9.3x. The fair ratio sits slightly higher at 19.1x.
So the stock screens cheap against one fair value model but looks full against sector and peer benchmarks based on earnings. Which signal do you trust when you size your exposure to Murphy Oil?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Murphy Oil so far. If you see both the upside potential and the pressure points, move quickly and test that view against the data using our breakdown of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Murphy Oil?
Do not stop your research with Murphy Oil. Broaden your watchlist now so you are not chasing opportunities after they already move.
- Target potential mispricings by scanning a focused set of companies that screen as attractively priced through the 31 high quality undervalued stocks.
- Build a steadier income stream by hunting for reliable payers using the 7 dividend fortresses.
- Dial down risk while staying invested by filtering for resilient businesses with the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com