
Bloom Energy (BE) Stock Looks Reasonable Despite A Very Large Run
Bloom Energy has been on a remarkable multi‑year run, and with the stock now around US$276.98, the real question is whether that share price is backed by the cash the business can generate over time. After a stretch of strong momentum and headline driven swings, investors are increasingly focused on what the company’s cash flows imply about its intrinsic value.
- Over the past 3 years the stock has delivered a very large gain of about 23x. That puts a lot of weight on whether the underlying cash generation can support such a move.
- Recent news around delays at Oracle’s Project Jupiter and policy support for on site power at data centers both affect when Bloom Energy may receive cash and how predictable those inflows could be.
- Prefer to judge Bloom Energy on sales? See why Bloom Energy's 26.2x P/S tells a different valuation story.
The issue now is whether Bloom Energy’s current market value is justified by its cash flows when assessed against a Discounted Cash Flow (DCF) view of its intrinsic value.
For context on this theme of on site power and cash flow backed valuations, it helps to compare Bloom Energy with other power grid and infrastructure stocks screened using 39 power grid technology and infrastructure stocks.
Does Bloom Energy Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on the cash Bloom Energy can return to shareholders over time. Latest twelve month free cash flow sits at about $619.3 million, and the model assumes that this figure grows meaningfully over the next decade as projects already in the pipeline move closer to operation.
Those projections climb into the multi billion dollar range by the early 2030s, which is a big swing in absolute dollars relative to where Bloom Energy is today. The DCF outcome suggests that these cash flows imply an intrinsic value meaningfully above the current share price of $276.98, even after discounting them back. News around Oracle’s Project Jupiter delays, and the risk of pushed out payments, helps explain why the market may still be pricing the stock below what those long term cash flows support. Find out what Bloom Energy could be worth using our Discounted Cash Flow (DCF) estimate.
The Bloom Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Bloom Energy pick up where the DCF puzzle leaves off and spell out which paths for Bloom Energy's future growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price on the Community page. Instead of leaving you with a single valuation output, they unpack the assumptions behind that figure so you can track over time whether the real business is moving in line with those expectations.
Community views on Bloom Energy pull in opposite directions, with one cohort focusing on untapped demand and the other on competitive and capital risks.
Bull case: 28% undervalued
"The Bloom Energy story is still early days, Wall Street cannot seem to comprehend that so many areas for their growth are largely untapped..."
Discover why this Narrative puts Bloom Energy at 28% undervalued.
Bear case: 113% overvalued
"Bloom's business remains capital intensive, with continued need for large-scale manufacturing expansion funded through convertible debt or future equity..."
Explore why this Narrative puts Bloom Energy at 113% overvalued.
One more Bloom Energy signal that deserves a closer look
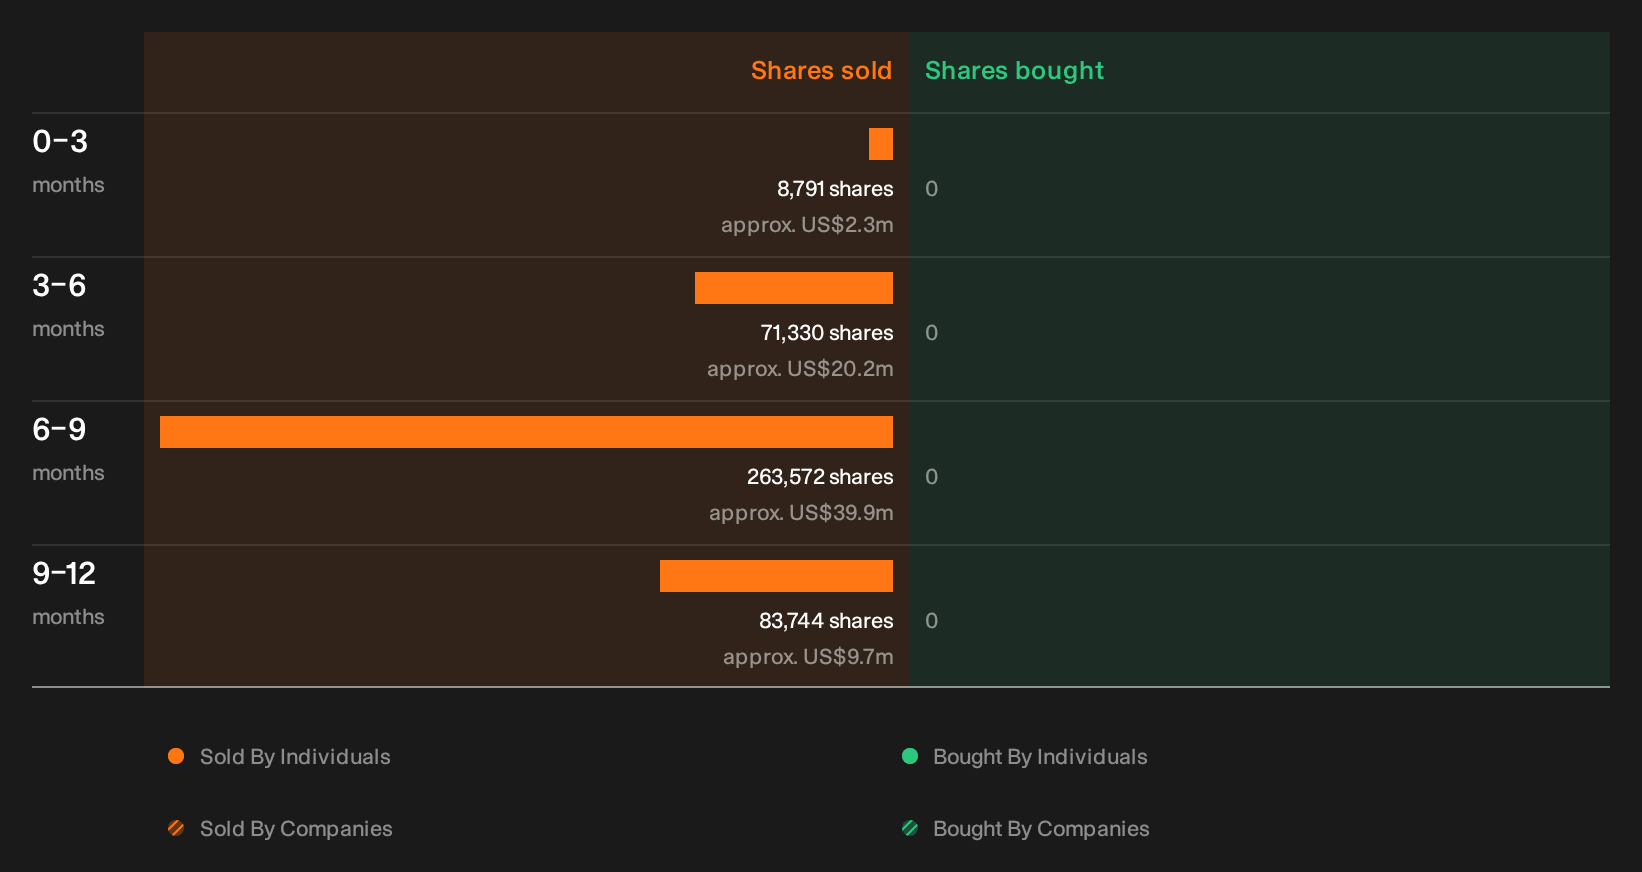
There is one last piece of the Bloom Energy story that is easy to miss: recent share sales by people inside the business, and the identities, sizes and possible messages in those trades are worth checking. See the recent insider selling flagged for Bloom Energy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com