
We're Keeping An Eye On Rafael Holdings' (NYSE:RFL) Cash Burn Rate
We can readily understand why investors are attracted to unprofitable companies. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
Given this risk, we thought we'd take a look at whether Rafael Holdings (NYSE:RFL) shareholders should be worried about its cash burn. For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. We'll start by comparing its cash burn with its cash reserves in order to calculate its cash runway.
When Might Rafael Holdings Run Out Of Money?
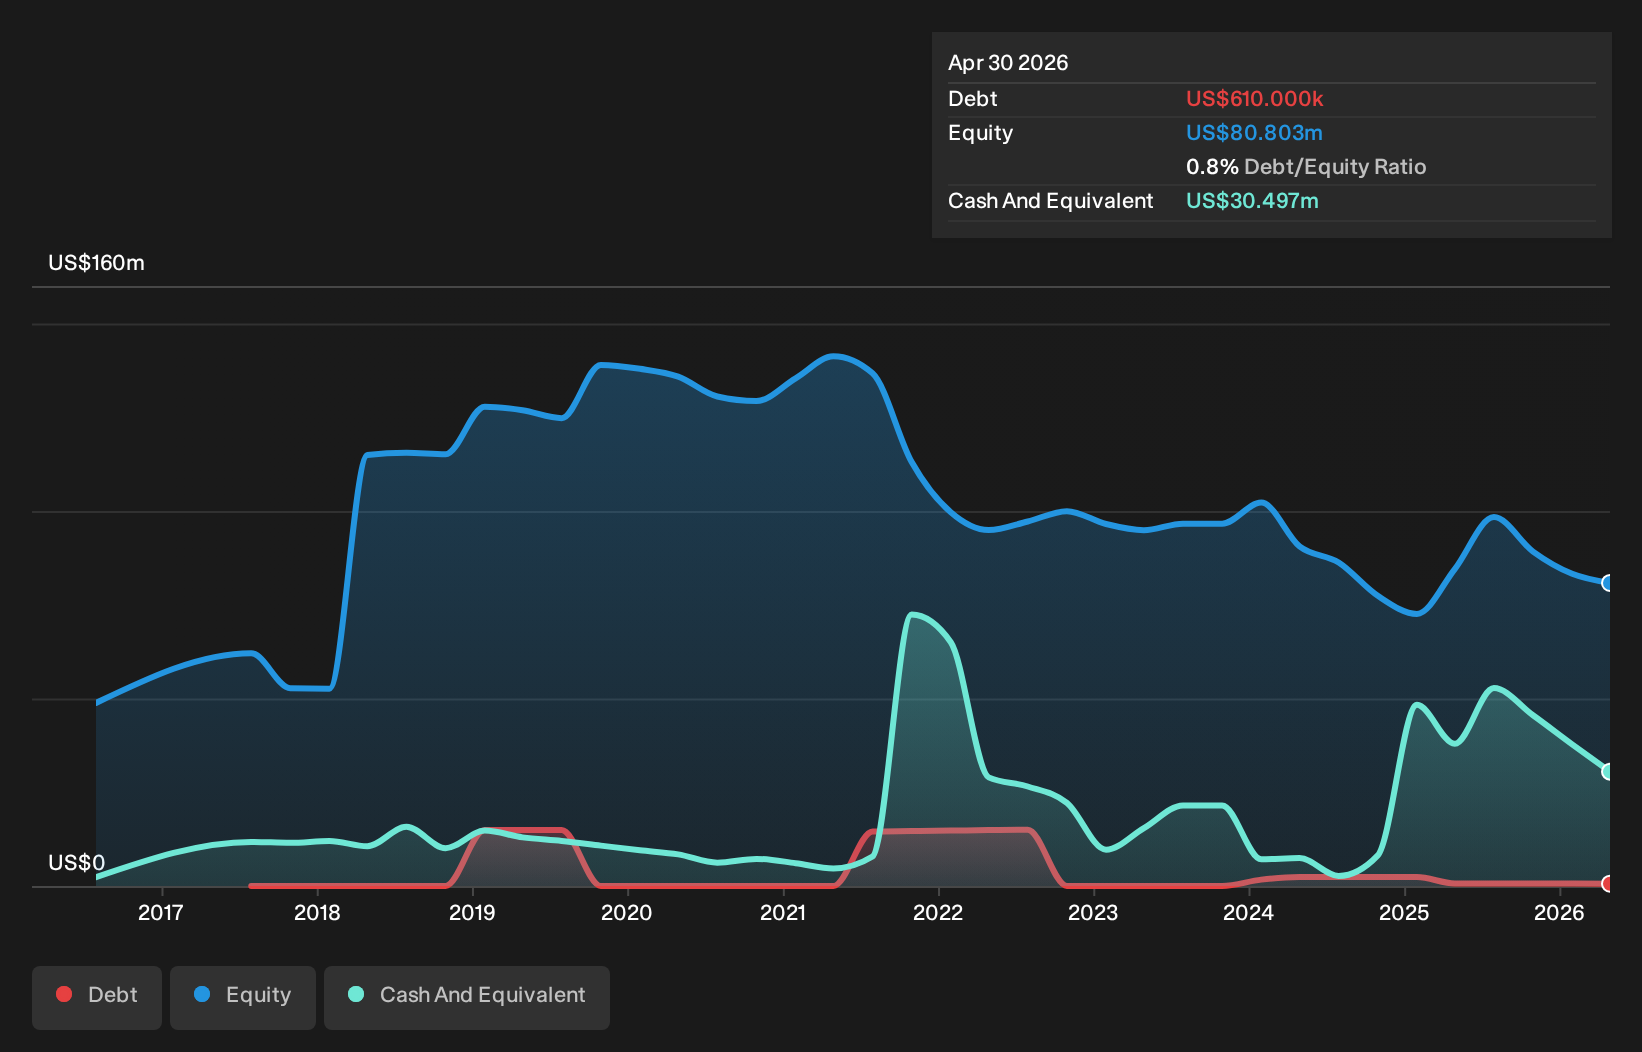
A company's cash runway is calculated by dividing its cash hoard by its cash burn. As at April 2026, Rafael Holdings had cash of US$30m and such minimal debt that we can ignore it for the purposes of this analysis. In the last year, its cash burn was US$32m. So it had a cash runway of approximately 11 months from April 2026. To be frank, this kind of short runway puts us on edge, as it indicates the company must reduce its cash burn significantly, or else raise cash imminently. You can see how its cash balance has changed over time in the image below.
Check out our latest analysis for Rafael Holdings
How Is Rafael Holdings' Cash Burn Changing Over Time?
Whilst it's great to see that Rafael Holdings has already begun generating revenue from operations, last year it only produced US$980k, so we don't think it is generating significant revenue, at this point. As a result, we think it's a bit early to focus on the revenue growth, so we'll limit ourselves to looking at how the cash burn is changing over time. The skyrocketing cash burn up 181% year on year certainly tests our nerves. That sort of spending growth rate can't continue for very long before it causes balance sheet weakness, generally speaking. Rafael Holdings makes us a little nervous due to its lack of substantial operating revenue. So we'd generally prefer stocks from this list of stocks that have analysts forecasting growth.
Can Rafael Holdings Raise More Cash Easily?
Given its cash burn trajectory, Rafael Holdings shareholders should already be thinking about how easy it might be for it to raise further cash in the future. Companies can raise capital through either debt or equity. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
Since it has a market capitalisation of US$106m, Rafael Holdings' US$32m in cash burn equates to about 30% of its market value. That's not insignificant, and if the company had to sell enough shares to fund another year's growth at the current share price, you'd likely witness fairly costly dilution.
So, Should We Worry About Rafael Holdings' Cash Burn?
Rafael Holdings is not in a great position when it comes to its cash burn situation. While its cash runway wasn't too bad, its increasing cash burn does leave us rather nervous. After looking at that range of measures, we think shareholders should be extremely attentive to how the company is using its cash, as the cash burn makes us uncomfortable. Its important for readers to be cognizant of the risks that can affect the company's operations, and we've picked out 4 warning signs for Rafael Holdings that investors should know when investing in the stock.
Of course Rafael Holdings may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.