
CSPC Pharmaceutical Group (SEHK:1093) Could Be 26% Undervalued Following Three Phase III Updates
CSPC Pharmaceutical Group (SEHK:1093) has just packed three late stage pipeline updates into one week, covering diabetes, lung cancer and breast cancer therapies and giving investors fresh clinical data to weigh.
The TG103, JMT101 and HB1801 updates have landed against a backdrop of building momentum in CSPC Pharmaceutical Group’s shares, with a 1-day share price return of 6.28%, a 90-day share price return of 33.38% and a 3-year total shareholder return of 109.87%. This suggests traders are reassessing both growth potential and risk around the pipeline.
Scan how CSPC Pharmaceutical Group’s trial momentum compares with other healthcare developers by reviewing our curated list of 133 healthcare AI stocks
CSPC Pharmaceutical Group now trades at roughly a 26% discount to both analyst targets and intrinsic estimates after a sharp move higher. Is that gap a valuation opportunity, or a sign that caution on the pipeline is still warranted?
Price-to-Earnings of 13.2x: Is it justified for CSPC Pharmaceutical Group?
CSPC Pharmaceutical Group is trading on a P/E of 13.2x, which appears inexpensive versus both peers and its own implied fair level based on recent data.
The P/E ratio compares what you pay for each HK$1 of current earnings. For a pharma developer with a broad mix of finished drugs, bulk products and functional foods, this measure gives a quick read on how the market is pricing today’s profitability against the rest of the sector.
Recent checks show CSPC Pharmaceutical Group at 13.2x earnings, while the peer average is around 21x and the Hong Kong pharmaceuticals group is closer to 13.5x. That is a sizeable gap. Regression-based analysis also suggests a fair P/E of 16.9x, which is a level the share price could move towards if sentiment around earnings and cash generation aligns more closely with that benchmark.
Explore the SWS fair ratio for CSPC Pharmaceutical Group.
Result: Price-to-Earnings of 13.2x (UNDERVALUED)
Still, the recent decline in net income and the heavy reliance on finished drugs in Mainland China leave the CSPC Pharmaceutical Group story exposed if there are changes in pricing or policy.
Find out about the key risks to this CSPC Pharmaceutical Group narrative.
Another View on CSPC Pharmaceutical Group’s Value
The SWS DCF model points to an estimated fair value of HK$14.12 per share for CSPC Pharmaceutical Group, compared with the current HK$10.07 price. That gap suggests the stock screens as undervalued on future cash flows. The question is whether those long term assumptions prove reliable.
Look into how the SWS DCF model arrives at its fair value.
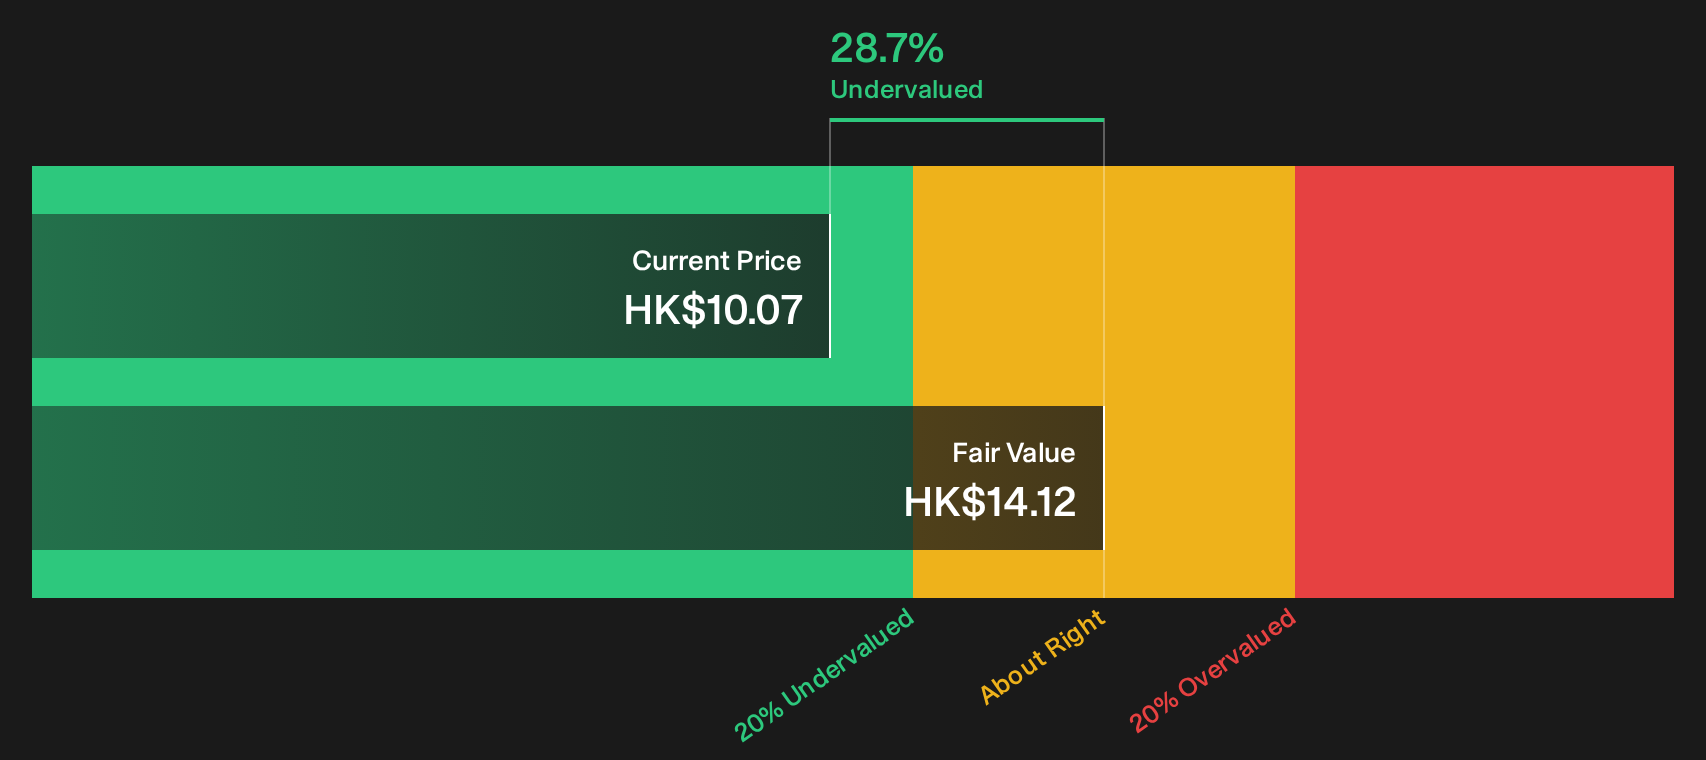
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CSPC Pharmaceutical Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment clearly split on CSPC Pharmaceutical Group, you do not need to wait for the next headline to form an opinion. Dig into the numbers, weigh the late stage pipeline against the risks, and pressure test the bullish and cautious cases by reviewing the 3 key rewards and 2 important warning signs
Looking for more CSPC Pharmaceutical Group sized opportunities?
If CSPC Pharmaceutical Group has sharpened your focus on pricing and risk, you can use that mindset to look for other ideas that may help you refine your watchlist.
- Target potential bargains by reviewing our screen of 191 high quality undervalued stocks, where pricing and fundamentals are more closely aligned.
- Strengthen portfolio resilience by scanning the 224 resilient stocks with low risk scores that score well on balance sheet and risk metrics.
- Explore opportunities by working through a curated set of 617 high quality undiscovered gems before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com