
Did New Obesity Data Just Shift Novo Nordisk Stock's Investment Narrative?
- Recent announcements from Novo Nordisk highlighted fresh clinical and real-world data across obesity and diabetes, including CagriSema brain and metabolic findings, COMPETE SWITCH cardiovascular outcomes with higher-dose semaglutide, and new Wegovy oral pill data, alongside a sizeable licensing deal for Hengrui’s once-weekly oral GLP-1/GIP dual agonist.
- Together, these updates point to Novo Nordisk pushing hard to expand its GLP-1 and cardiometabolic portfolio beyond injectable semaglutide. New modes of delivery, combination therapies, and external partnerships are reshaping how the business allocates R&D capital and defends its obesity and diabetes leadership.
- Next, the focus shifts to how Novo Nordisk's long-term investment narrative is influenced by CagriSema’s brain and organ-level obesity data.
Scan how Novo Nordisk’s obesity and diabetes push compares with other cardiometabolic opportunities by reviewing the hand-picked 191 high quality undervalued stocks that may be positioned for the next leg of demand.
Novo Nordisk Investment Narrative Recap
To own Novo Nordisk, you need to believe the obesity and diabetes engine can keep generating new therapies that keep patients on branded drugs despite pricing pressure, compounding and looming semaglutide competition. The most important short term catalyst is the late 2026 FDA decision on CagriSema for weight management. That decision could reshape how investors think about the next wave after Wegovy.
The biggest near term risk still sits in margin pressure from price erosion and rising manufacturing and distribution costs. This week’s CagriSema brain and organ level data does not change that directly, but it supports the case that Novo Nordisk’s R&D spend is going into differentiated mechanisms rather than copycat GLP 1s.
Among the recent updates, the detailed fMRI and organ fat data on CagriSema look most relevant. They tie the product narrative to concrete biology, from reduced food noise and cravings to lower abdominal and liver fat in early type 2 diabetes. That matters for how payers and regulators may view cardiometabolic benefit beyond the scale.
For you as an investor, that evidence links directly back to the CagriSema NDA and the wider REDEFINE and REIMAGINE phase 3 programmes. If regulators are comfortable with both efficacy and bone and organ safety signals, CagriSema could become a key tool for Novo Nordisk to offset future Wegovy and Ozempic pricing pressure and generic headwinds.
Novo Nordisk's current analyst framework points to DKK 337.5b in revenue and DKK 107.3b in earnings by 2029, with revenue projected to stay broadly flat and profit expected to decline by about DKK 9.1b from DKK 116.4b today.
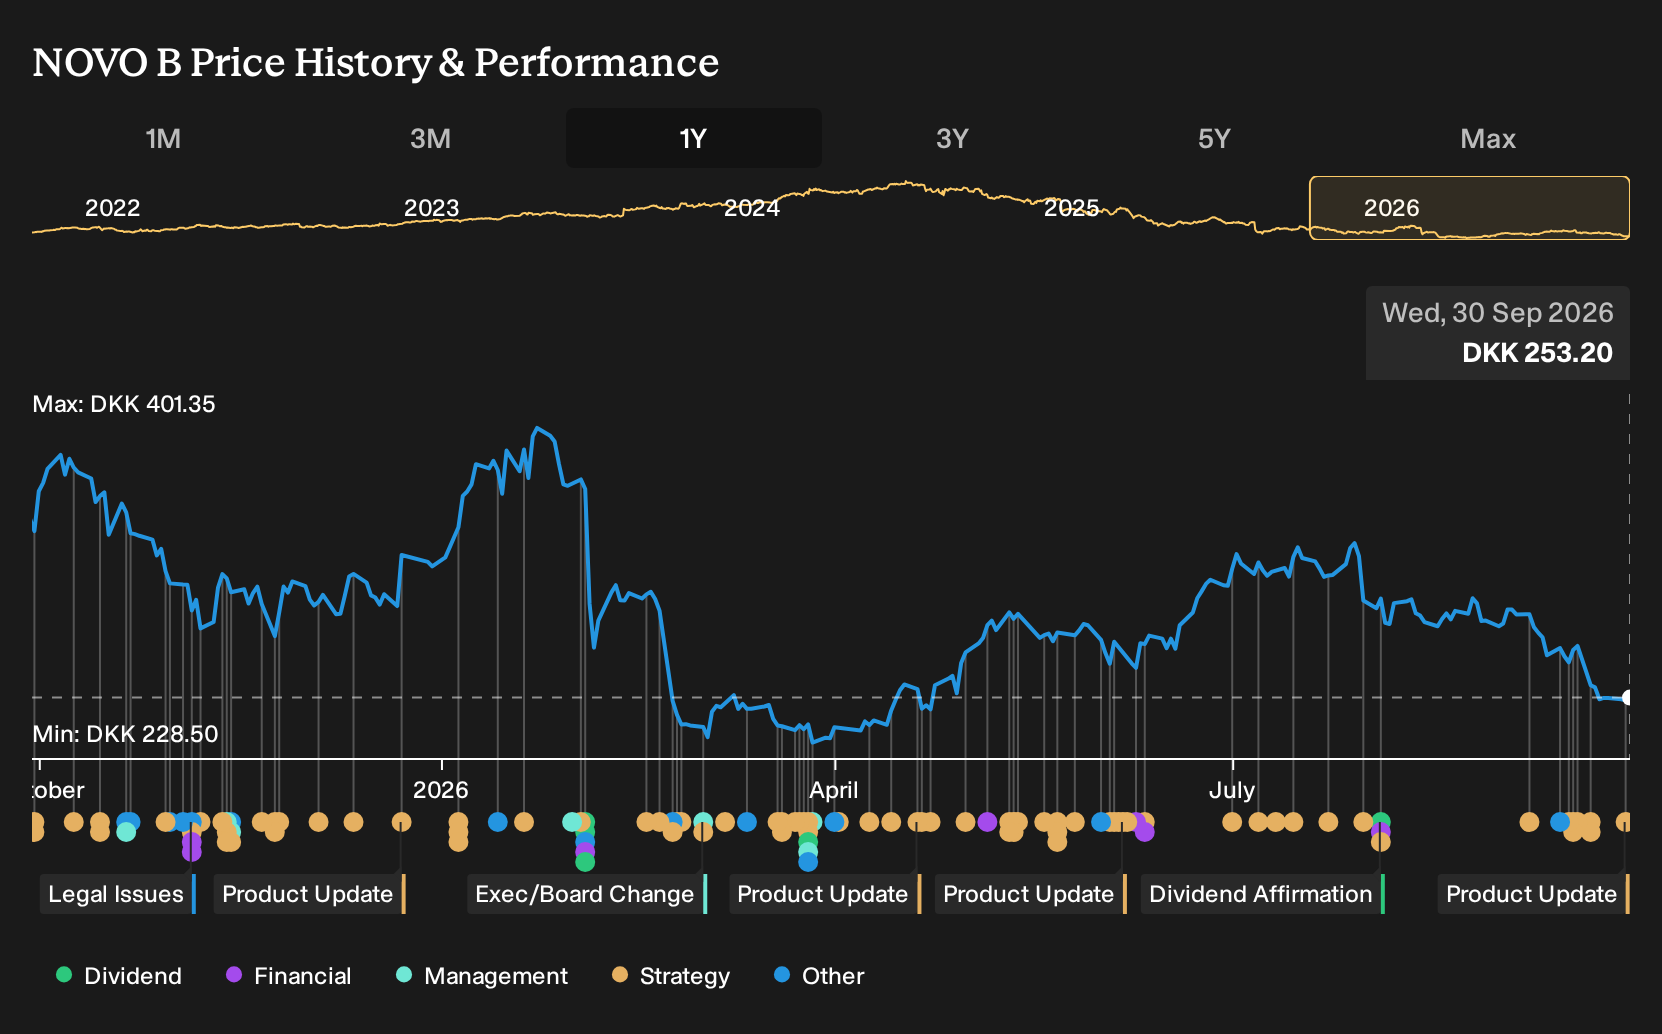
Uncover how Novo Nordisk's fair value indicates a 22% potential upside to its current price before investors fully price in Novo Nordisk’s obesity pipeline story.
Exploring Other Perspectives
You might see the CagriSema data as a fresh upside catalyst, yet the most optimistic Novo Nordisk analysts were already sketching a very different story before this news. They were working off revenue assumptions of DKK 395.1b and earnings of DKK 137.3b by 2029, versus the more cautious DKK 337.5b and DKK 107.3b. That gap shows how far opinions can stretch. Use these competing views as a starting point to test your own expectations and decide which version of the future feels closer to your reality.
Explore 19 other Novo Nordisk fair value estimates, including one that suggests as much as 241% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Novo Nordisk research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Novo Nordisk. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novo Nordisk's overall financial health at a glance.
Looking For More Investment Ideas Beyond Novo Nordisk?
Once you have a view on Novo Nordisk, it can help to line that up against other opportunities that fit your risk, income, and quality preferences using the Simply Wall St Screener.
- If capital preservation and steadier journeys matter most to you, scan a 224 resilient stocks with low risk scores that aim to keep drawdowns more controlled while still participating in market returns.
- If you prefer durable balance sheets that can absorb shocks, check out a list of solid balance sheet and fundamentals (205 results) that pair financial strength with consistent fundamentals.
- If you are hunting for underfollowed potential, review a 617 high quality undiscovered gems that combine quality metrics with less crowded ownership.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com