
3 Payment Stocks to Watch as Tighter Money Tests Transaction Banking
Central banks are hinting at tighter money, growth forecasts are being cut, and supply chains are feeling the strain. That mix is quietly reshaping how global custody and transaction-banking platforms matter to investors who do not want surprises when the cycle turns. This article unpacks that story and walks through 3 stocks exposed to the current news backdrop, all drawn from our screener and each responding in a different way to the same macro shock.
The stocks covered below are only a starter pack from this theme, and the full screen surfaced 12 more global custody and transaction-banking platforms with similarly detailed stories that are not covered here. To size up that broader opportunity set directly, head into the Global Custody and Transaction-Banking Platforms screener to identify, compare, and analyze the highest-conviction ideas in one place.
EVERTEC (EVTC)
Overview: EVERTEC runs payment processing rails and cash-management technology across Latin America and the Caribbean, connecting banks, merchants, and governments into the region’s day-to-day transaction plumbing.
Operations: EVERTEC generates about $441 million from Latin America Payments and Solutions, $238 million from Business Solutions, $231 million from Payment Services Puerto Rico and Caribbean, and $196 million from Merchant Acquiring, partly offset by $110 million of intersegment eliminations.
Market Cap: US$1.6b
EVERTEC matters for this screener because it is not just a fintech stock; it is one of the companies running the underlying payment and settlement pipes that regional banks and corporates rely on when credit tightens and transaction-banking efficiency suddenly becomes critical.
"Accelerated digital payment adoption and regulatory support in Latin America and the Caribbean are fueling strong revenue growth and expanding Evertec's market reach."
The real question for investors is how Evertec’s heavy technology investment and contract repricing ripple through margins if a single key assumption breaks.
If that margin puzzle has you curious, the full narrative for EVERTEC shows where Evertec could be accelerating, stalling, or quietly masking risk under those payment rails.

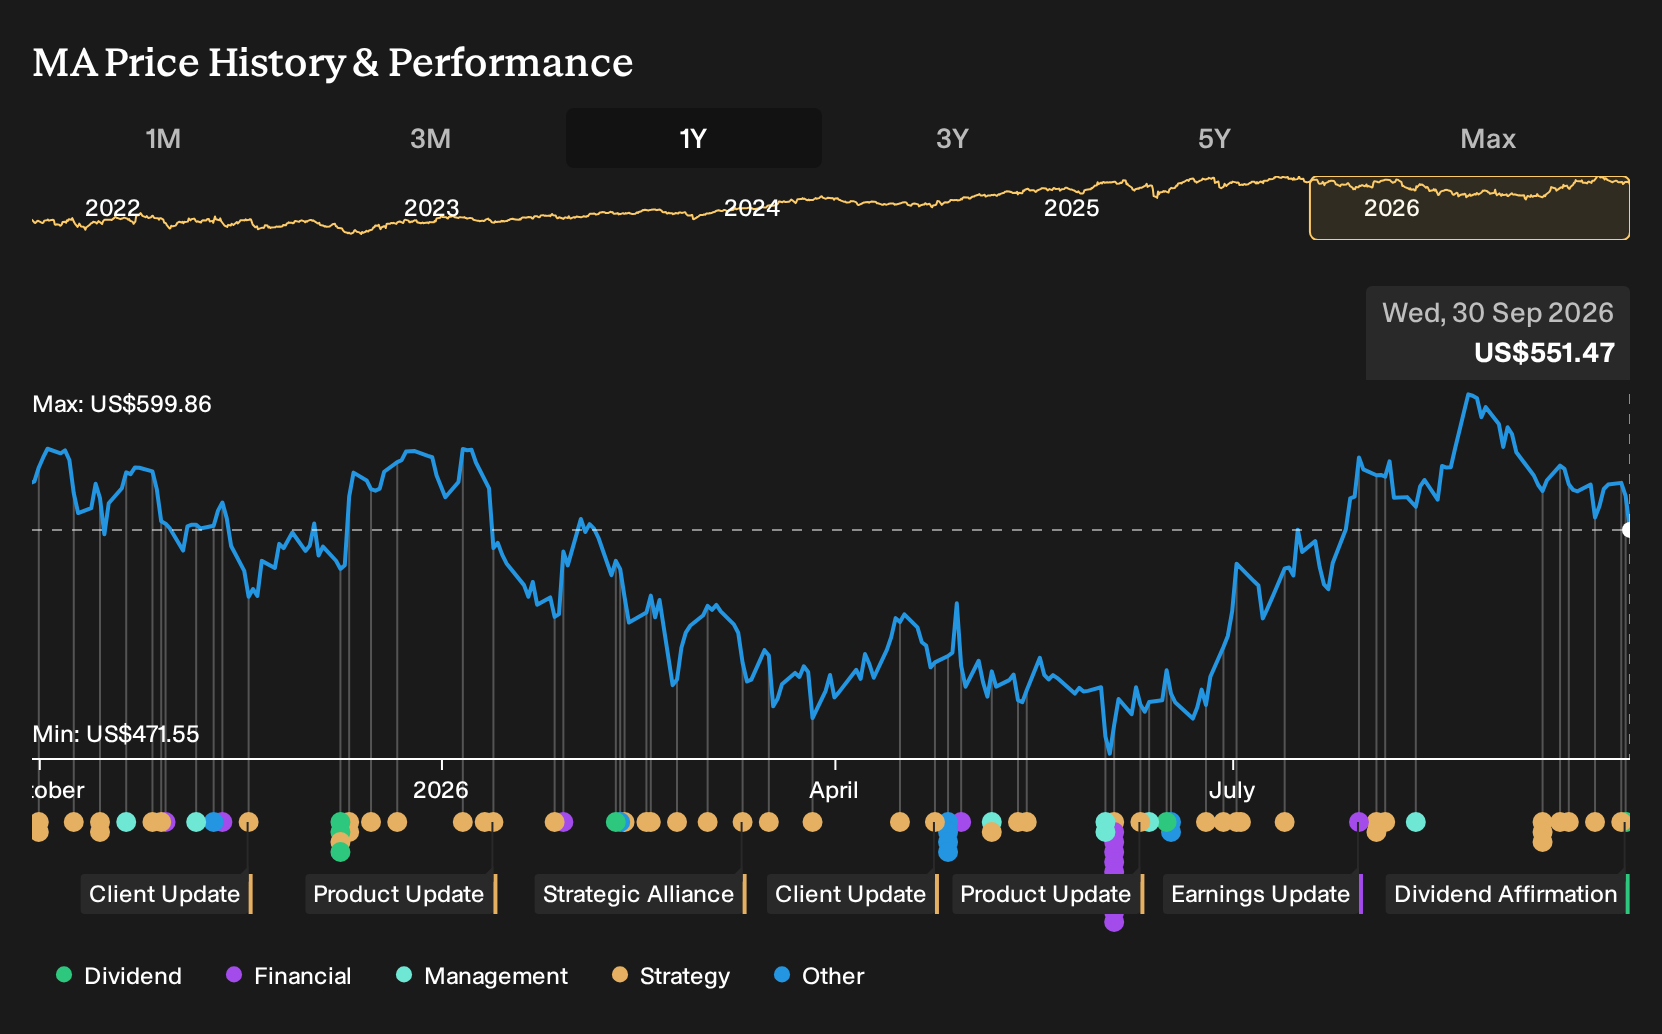
Mastercard (MA)
Overview: Mastercard runs a global payments network that processes card and digital transactions for banks, merchants, governments, and platforms across borders.
Operations: Mastercard generates about $35.1b from Payment Solutions, with $15.1b from the Americas and $20.0b from Asia Pacific, Europe, Middle East and Africa.
Market Cap: US$493.7b
In a world where tighter money and geopolitical shocks keep putting pressure on how cash moves, Mastercard gives this screener a pure view on the plumbing of global transaction flows, from consumer swipe fees to bank-to-business settlement rails.
"Because the company never takes on credit risk, it does not need to set aside capital for loan losses the way a bank does. This keeps the model asset-light and the margins unusually high even in a downturn."
What really matters next is how one underappreciated shift in cross-border payment behavior affects pricing power and long-term earnings quality.
That shift in cross-border behavior is the real hinge. The full narrative for Mastercard shows where Mastercard’s asset-light model could be accelerating and decoupling risk from long-term earnings quality.
Jack Henry & Associates (JKHY)
Overview: Jack Henry & Associates provides core banking software, payment processing, and digital banking tools that help U.S. banks run transaction and cash-management services.
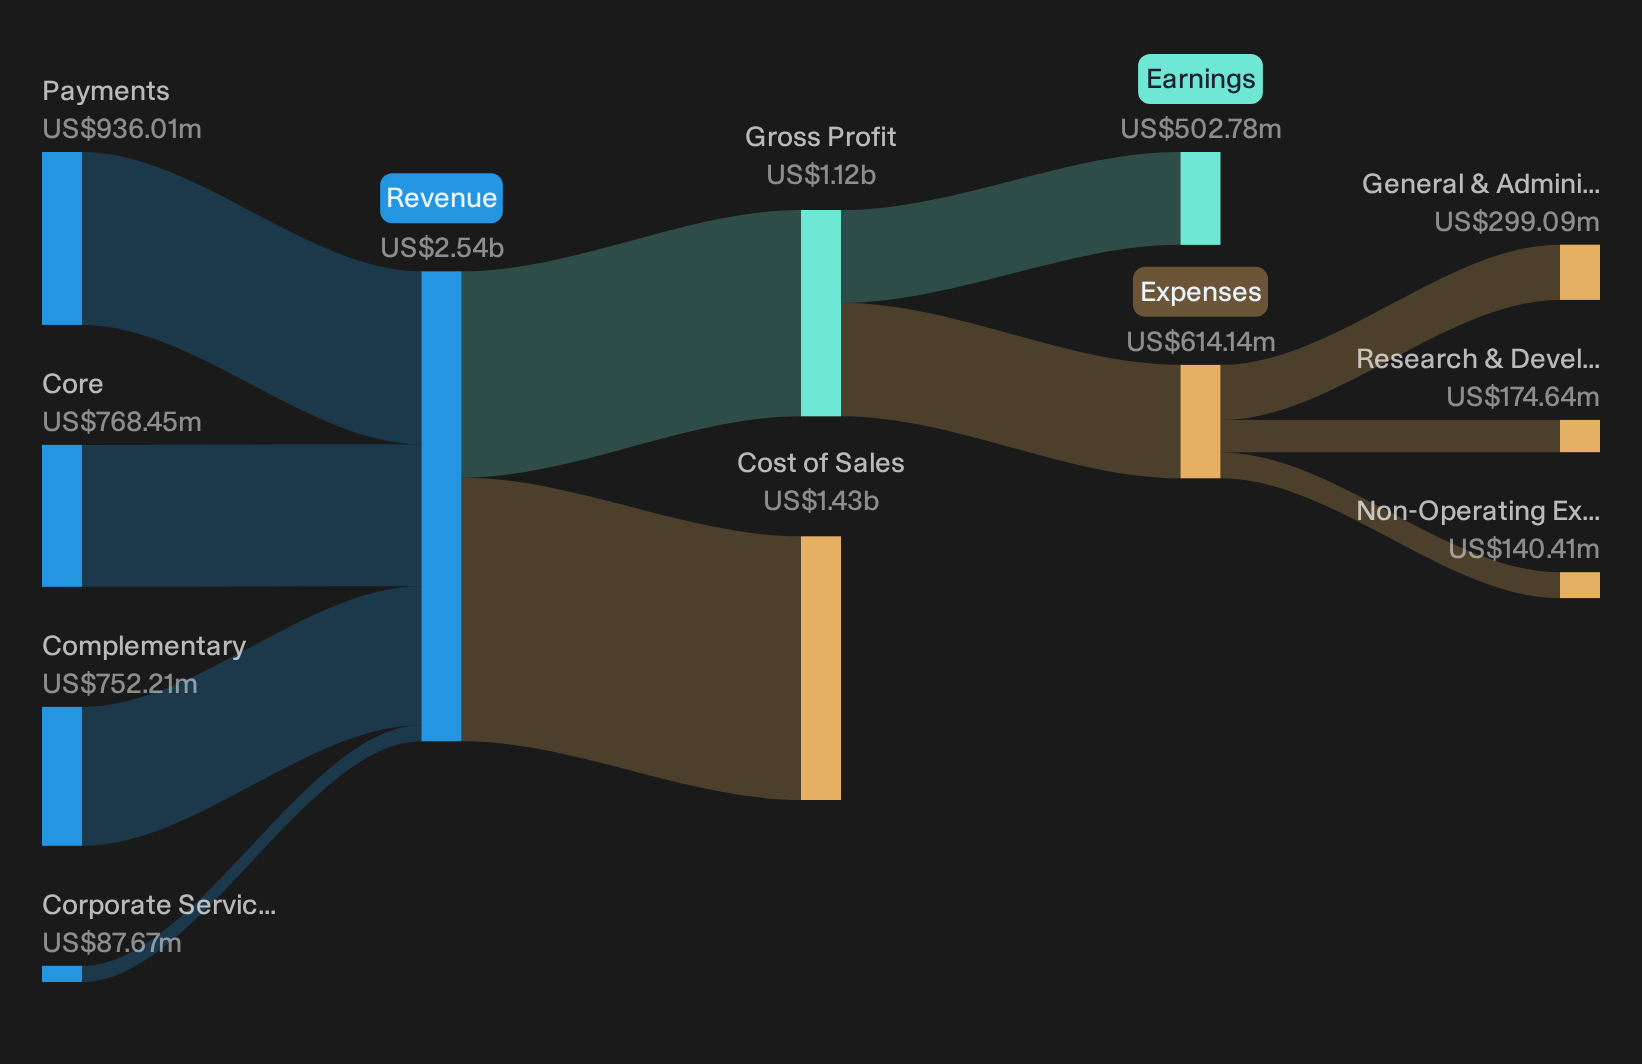
Operations: Jack Henry & Associates generates about $768 million from Core, $936 million from Payments, $752 million from Complementary, and $88 million from Corporate Services, all within the United States.
Market Cap: US$10.0b
Jack Henry & Associates matters for this theme because it supplies the underlying systems community and regional banks depend on when they upgrade their custody, treasury, and transaction-banking infrastructure under tighter money conditions.
"The August call presented it as one of 15 competitive core wins in the quarter, one of 14 over $1 billion for the year, the anchor of a 58 win fiscal year that broke a two decade record."
The real swing factor for investors is what happens to those core wins and cross-sold services if one quiet cost pressure intensifies.
If that quiet cost pressure has your attention, the full narrative for Jack Henry & Associates shows where Jack Henry & Associates could be accelerating, stalling, or masking risk in those core wins.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities often move from quiet to crowded quickly. Look for the next breakout momentum while it is still under the radar for now. Avoid entering positions too late and consider acting while conditions still appear favorable.
- Track income-focused opportunities that aim to keep payouts resilient and sizable through the 7 dividend fortresses. This can help you review yield-focused setups before they potentially become widely followed.
- Spot early leaders in automation and next-gen hardware via the curated 92 robotics and automation stocks, at a stage when the market may still be treating them as secondary priorities.
- Zero in on potential early candidates in uranium, reactors, and supporting infrastructure using the hand-picked 18 nuclear energy infrastructure stocks, while broader sentiment is still developing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com