
What to Expect From J.B. Hunt Transport’s Next Quarterly Earnings Report
J.B. Hunt Transport Services, Inc. (JBHT) is a transportation and logistics company that provides intermodal, dedicated contract, truckload, final-mile delivery and freight brokerage services. It combines trucking, rail partnerships, company-owned equipment and technology-enabled logistics solutions to move goods across North America. The company is headquartered in Lowell, Arkansas and has a market capitalization of $21.04 billion.
The company is expected to report its third-quarter results for fiscal 2026 soon. Ahead of the release, Wall Street analysts are optimistic about the company’s bottom-line trajectory.
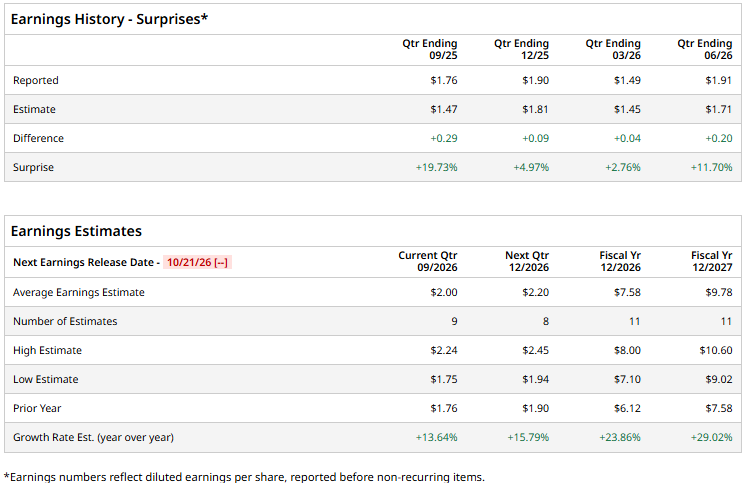
Analysts expect J.B. Hunt to report diluted earnings of $2 per share for Q3, up 13.6% year-over-year (YOY). The company has a strong history of beating consensus estimates, topping them in each of the trailing four quarters. For full fiscal year 2026, Wall Street analysts expect J.B. Hunt’s diluted EPS to grow 23.9% to $7.58, followed by a 29% improvement to $9.78 in fiscal 2027.
Over the past 52 weeks, the stock has gained 67%, while it is up 15.3% year-to-date (YTD), driven largely by stronger freight volumes, better-than-expected earnings, and improved operating performance. Meanwhile, the broader S&P 500 Index ($SPX) has increased by 14% and 11.8% over the same periods, respectively. Therefore, the stock has outperformed the broader market.
We now compare J.B. Hunt’s performance with that of its sector. The State Street Industrial Select Sector SPDR ETF (XLI) has increased 8.3% over the past 52 weeks and 7.7% YTD. As a result, the stock has outperformed its sector over these periods.
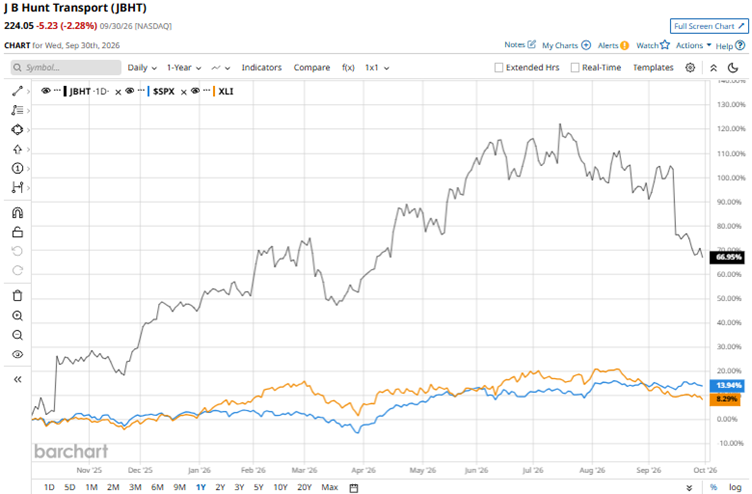
J.B. Hunt’s stock came under pressure on Sept. 16, dropping 13.3% intraday, as the company highlighted operational headwinds that could lead to a 10% sequential decline in its Q3 EPS due to severe cost pressures and market volatility. J.B. Hunt is projected to incur a sequential $10 million headwind from fuel costs due to rapid fluctuations in diesel prices.
This contrasts sharply with the operational leeways J.B. Hunt made in the second quarter of fiscal 2026, when it reported better-than-expected results. The company’s total operating revenues increased by 19.4% YOY to $3.50 billion. Excluding the impact of fuel surcharge, the revenue increase was driven primarily by higher load volumes and higher revenue per load. J.B. Hunt’s EPS increased 45.8% YOY to $1.91, as operating income improved on improved productivity and continued progress in reducing structural costs, medical claims, facility rental expenses and equipment storage costs.
Wall Street analysts remain bullish on J.B. Hunt’s future. Among the 25 analysts covering the stock, the consensus rating is “Moderate Buy.” The rating configuration is more bullish than it was three months ago, with 14 “Strong Buy” ratings now, up from 12. The ratings are rounded off by one “Moderate Buy,” eight “Holds,” one “Moderate Sell,” and one “Strong Sell.” The mean price target of $304.79 implies a 36% upside from current levels, while the Street-high price target of $370 implies 65.1% upside.
On the date of publication, Anushka Dutta did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.