
Murata Manufacturing (TSE:6981) Starts Mass Production Of Tiny Capacitors, Is The Stock Already Above Fair Value?
Murata Manufacturing (TSE:6981) just moved its LLD series of three-terminal multilayer ceramic capacitors into mass production, shrinking component size for smartphones and wearables and sharpening investor focus on how this technology fits into the stock’s story.
The recent capacitor launch lands after a flurry of interest in Murata Manufacturing, with the share price at ¥8,471 and a sharp short-term rebound in focus. The stock has a 1-day share price return of 7.9% and a 30-day share price return of 16.2%, even though the 90-day share price return declined 23.6%. Over a longer stretch, the picture looks different. The year to date share price return of 154.4% and a 1-year total shareholder return of 210.1% point to strong momentum that has built over time rather than a one week spike.
Capitalize on Murata Manufacturing's momentum in miniaturized electronics by scanning a hand picked set of 90 AI infrastructure stocks that support the same surge in data hungry devices and power hungry chips.Bulls see Murata Manufacturing’s tiny capacitors and rebound as proof the rerating has room to run. Bears see overexcited momentum. Which story do the current valuation and fundamentals lean toward?
Price-to-Earnings of 58.1x: Is it justified?
Murata Manufacturing trades on a P/E of 58.1x, well above many peers, which puts a clear premium on the ¥8,471 share price relative to earnings.
The P/E ratio compares what investors pay for each unit of current profit. For a components supplier like Murata Manufacturing, that metric often reflects how much the market is willing to pay for expected earnings growth in smartphones, wearables, data centers, and other electronics where its parts are used.
Forecast data shows earnings expected to grow 25.6% per year, with revenue projected to rise 14.4% per year and Return on Equity seen at 20.3% in three years. That kind of earnings profile can help explain why investors accept a P/E that is far above many domestic stocks. At the same time, the current 58.1x multiple is materially above the estimated fair P/E of 38.5x. This is a level the market could move towards if growth or sentiment cools. Against the JP Electronic industry average of 16.6x and a peer average of 56.4x, the current valuation looks rich rather than cheap.
Explore the SWS fair ratio for Murata Manufacturing.
Result: Price-to-Earnings of 58.1x (OVERVALUED)
Still, Murata Manufacturing’s rich 58.1x P/E, alongside a sharp 210.1% 1-year total return, leaves little cushion if smartphone or data center demand disappoints.
Find out about the key risks to this Murata Manufacturing narrative.
Another view on Murata Manufacturing’s valuation
The story shifts once the SWS DCF model is brought in. While the P/E of 58.1x looks stretched, the DCF output points to a fair value of ¥11,599.16 per share versus today’s ¥8,471, which implies Murata Manufacturing trades about 27% below that estimate. Is this a genuine margin of safety or just model optimism?
Look into how the SWS DCF model arrives at its fair value.
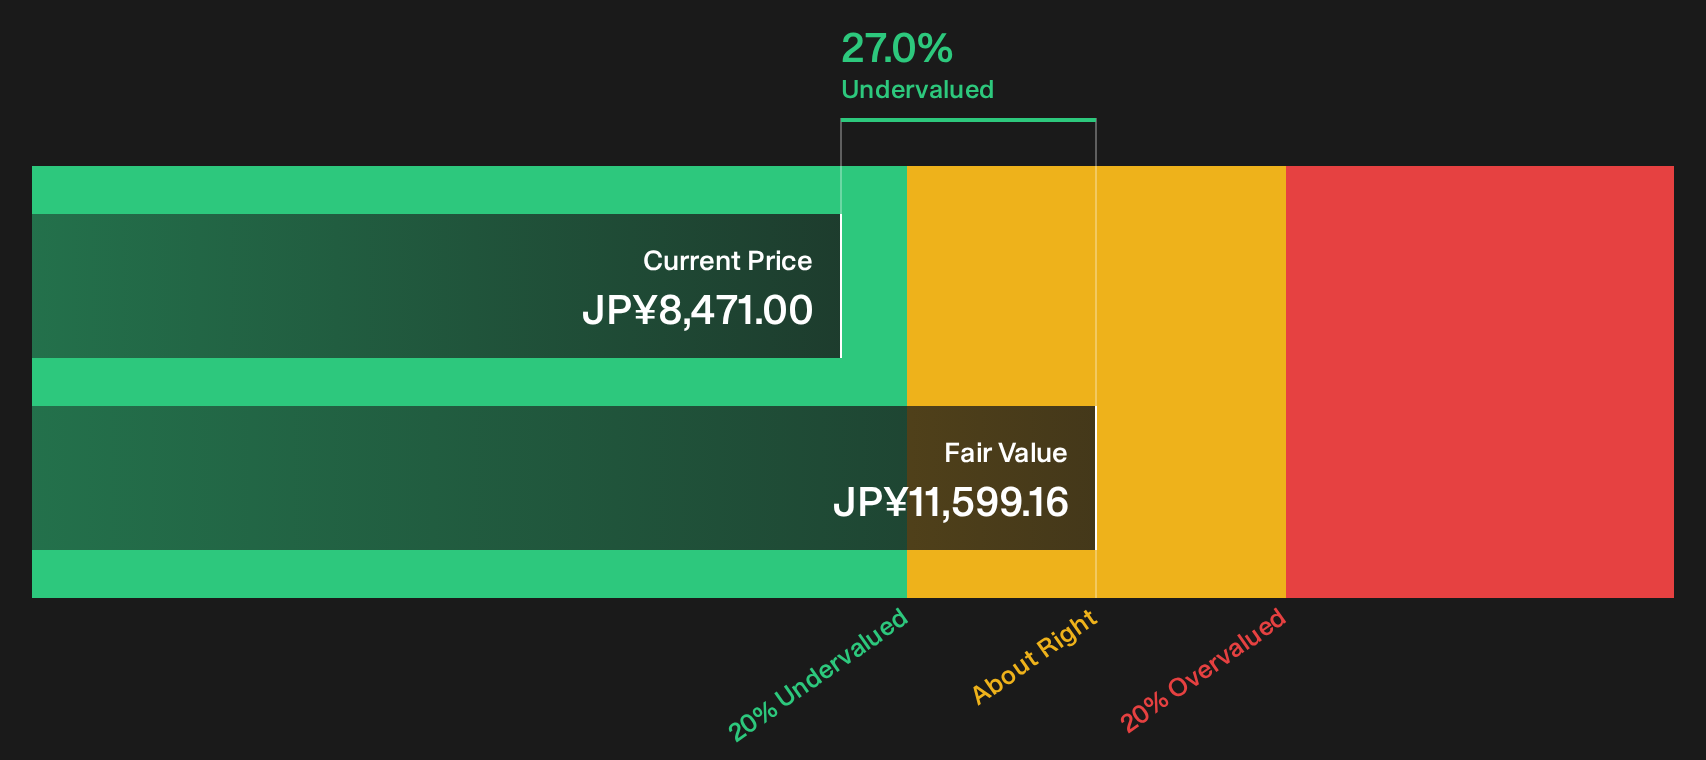
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murata Manufacturing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Murata Manufacturing is clearly split, and this is where your own homework matters most. Be sure to weigh the upside and downside using the 2 key rewards and 1 important warning sign.
Looking for more Murata Manufacturing style investment ideas?
If Murata Manufacturing has sharpened your focus on quality opportunities, do not stop here. Use structured screeners to quickly surface other potential candidates before the crowd does.
- Target strong pricing power and quality by scanning a curated group of 17 high quality undervalued stocks that combine robust fundamentals with room for sentiment to catch up.
- Prioritise resilience by checking a list of solid balance sheet and fundamentals (23 results) so you can focus on businesses with the financial strength to handle tougher conditions.
- Get ahead of the herd by reviewing 76 high quality undiscovered gems that the market has not fully focused on yet but already show solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com