
Top Growth Companies With Strong Insider Ownership In October 2026
In the last week, the United States market has been flat, yet it has shown a robust 11% increase over the past year with earnings projected to grow by 18% annually in the coming years. In such an environment, growth companies with high insider ownership can be particularly appealing as they often reflect strong confidence from those who know the business best.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Precigen (PGEN) | 11.7% | 54% |
| Nu Holdings (NU) | 22.8% | 22.3% |
| Karman Holdings (KRMN) | 14.4% | 56.4% |
| Himax Technologies (HIMX) | 29.2% | 70.2% |
| Figure Technology Solutions (FIGR) | 21.4% | 32.2% |
| Dave (DAVE) | 16.7% | 23.6% |
| Carlyle Group (CG) | 27.4% | 22% |
| Almonty Industries (ALM) | 10.8% | 57.0% |
Let's take a closer look at a couple of our picks from the screened companies.
GBank Financial Holdings (GBFH)
Simply Wall St Growth Rating: ★★★★★☆
Overview: GBank Financial Holdings Inc., with a market cap of $270.73 million, operates as a bank holding company for GBank, offering banking services to commercial and consumer customers in Nevada.
Operations: The company generates revenue of $75.31 million from its banking services provided to both commercial and consumer clients in Nevada.
Insider Ownership: 32.5%
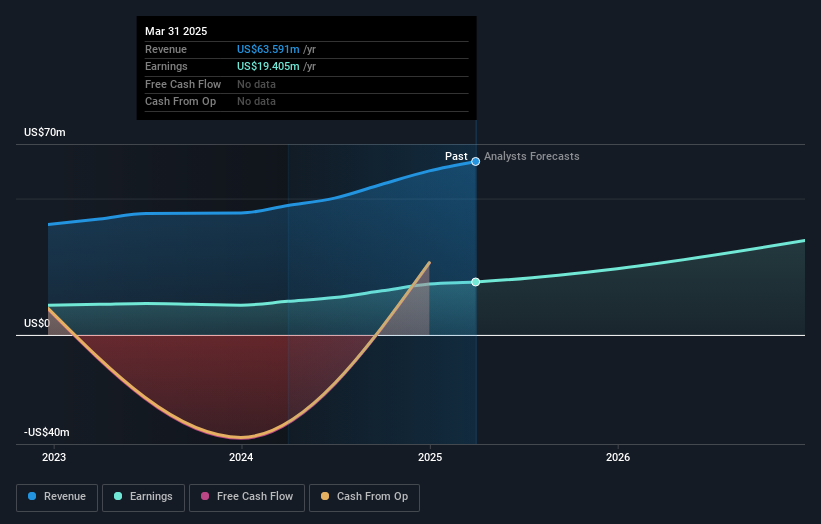
GBank Financial Holdings shows promising growth potential with earnings expected to grow significantly over the next three years, outpacing the US market. The company trades at nearly half its estimated fair value, with analysts predicting a 76% price increase. Although insider buying has been substantial recently, GBank faces challenges such as high bad loan levels and executive turnover. Recent earnings reflect modest growth in net interest income and net income compared to last year.
- Navigate through the intricacies of GBank Financial Holdings with our comprehensive analyst estimates report here.
- The analysis detailed in our GBank Financial Holdings valuation report hints at an deflated share price compared to its estimated value.
EHang Holdings (EH)
Simply Wall St Growth Rating: ★★★★★☆
Overview: EHang Holdings Limited is an urban air mobility technology platform company operating across several regions including China, Asia, the Americas, Africa, and Europe with a market cap of approximately $329.93 million.
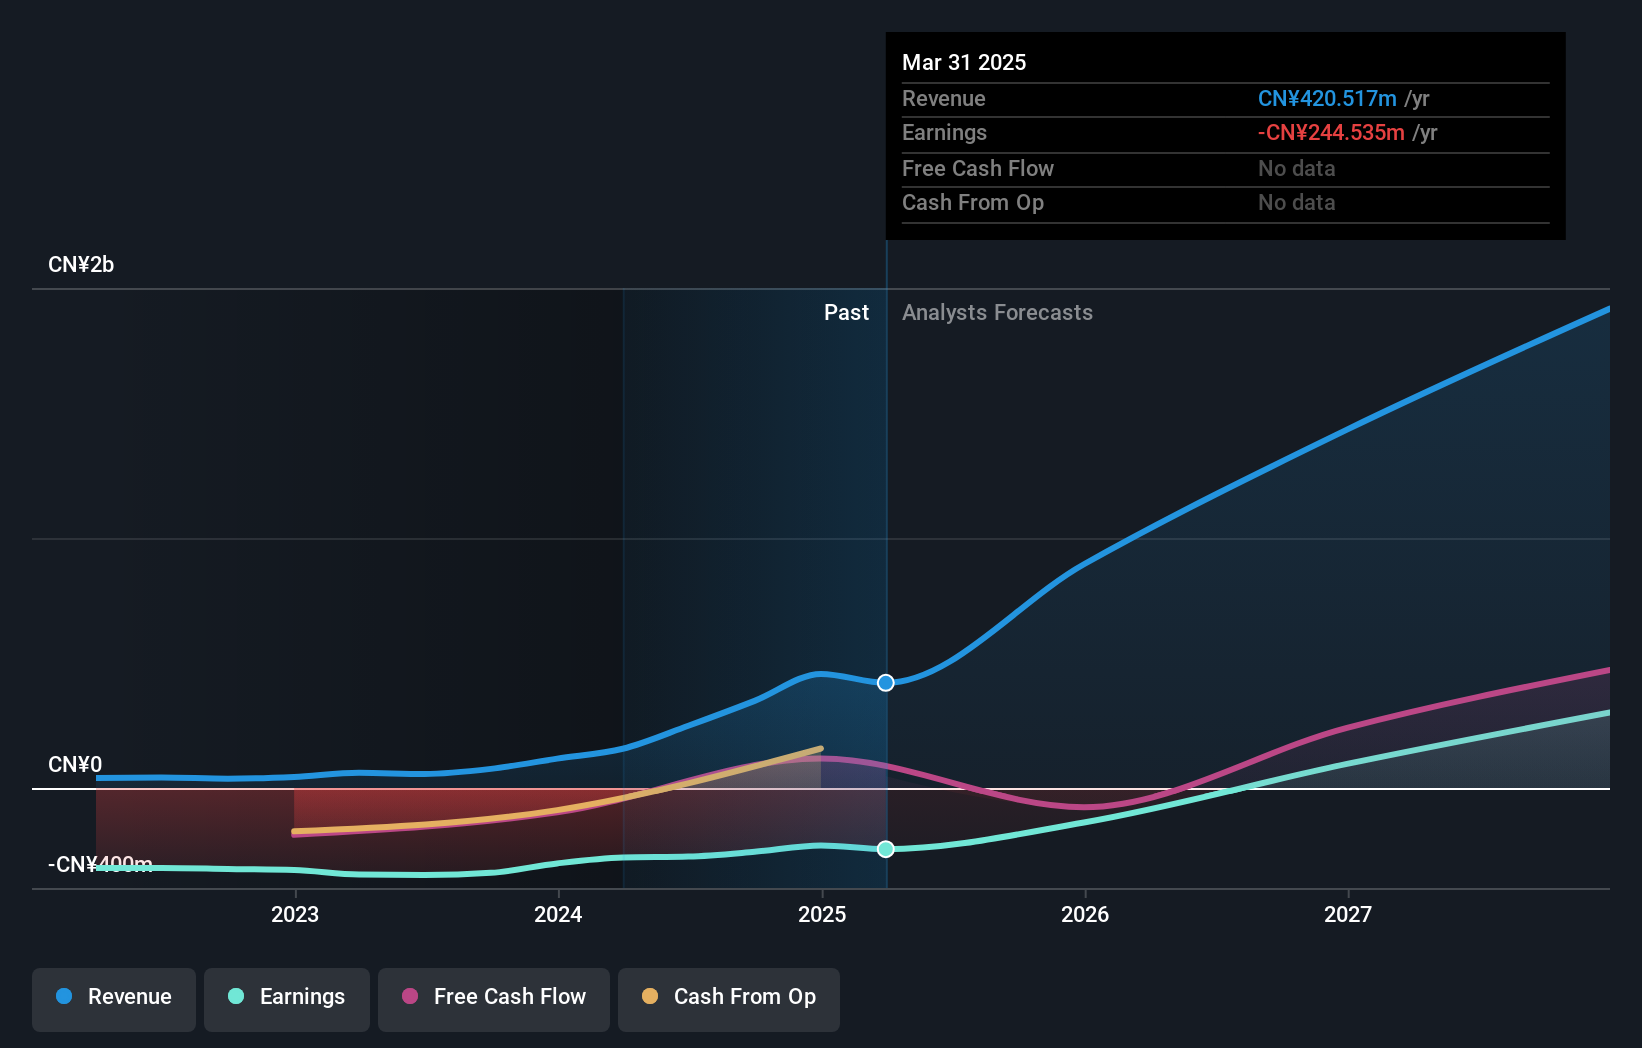
Operations: The company generates its revenue primarily from the Aerospace & Defense segment, which amounts to CN¥382.12 million.
Insider Ownership: 28.1%
EHang Holdings is projected to achieve profitability in three years, with revenue growth forecasted at 34.8% annually, surpassing market averages. Despite trading significantly below estimated fair value, the company faces challenges due to recent financial losses and withdrawn revenue guidance amid regulatory uncertainties. Recent milestones include a successful public demonstration of its EH216-S eVTOL aircraft in Hong Kong and strategic partnerships aimed at expanding drone light shows in Japan and developing low-altitude infrastructure in China.
- Click here to discover the nuances of EHang Holdings with our detailed analytical future growth report.
- Our valuation report here indicates EHang Holdings may be undervalued.
Reformation (REF)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Reformation Inc. manufactures and sells sustainable women's clothing and accessories both in the United States and internationally, with a market cap of $724.90 million.
Operations: The company's revenue is primarily derived from its apparel segment, totaling $563.47 million.
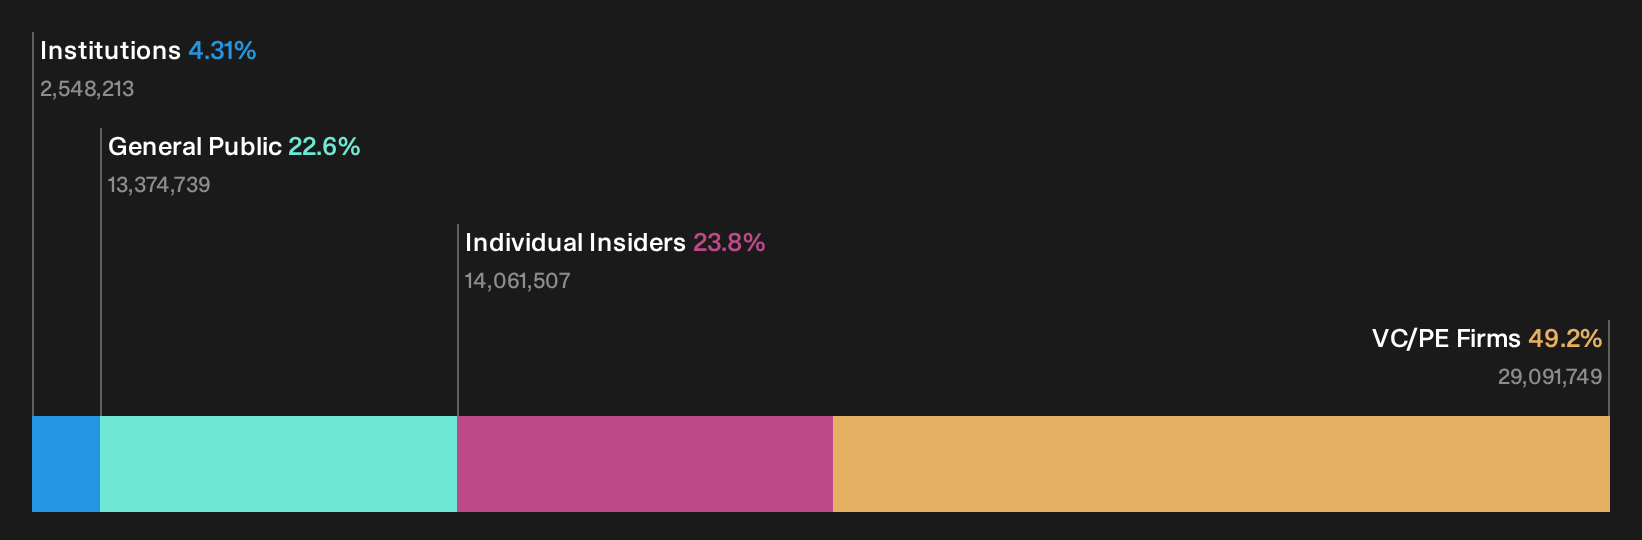
Insider Ownership: 23.7%
Reformation Inc. has recently been added to multiple Russell indices, signaling increased visibility among investors. The company reported a significant revenue increase of US$155.23 million for Q2 2026, up from US$125.07 million the previous year, and earnings growth is forecast at 68.61% annually, outpacing market averages. Despite insider selling and lower profit margins compared to last year, Reformation's projected revenue growth remains robust at 14.9% per year with strong analyst support for future price appreciation.
- Dive into the specifics of Reformation here with our thorough growth forecast report.
- Upon reviewing our latest valuation report, Reformation's share price might be too pessimistic.
Seize The Opportunity
- Click here to access our complete index of 183 Fast Growing US Companies With High Insider Ownership.
- Interested In Other Possibilities? Trump's oil boom is here — pipelines are primed to profit. Discover the 80 US stocks riding the wave.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com