
Not Cars. Not Energy Storage. Tesla's Robotics and Robotaxi Ambitions Are the Real Reason the Stock Is Priced Like a Tech Company.
Key Points
Tesla shares are priced shockingly high, even by technology stock standards.
Given the potential profit centers the company is currently developing, however, this premium valuation makes sense.
It could take far longer than most investors might expect for the business to justify the stock's current valuation.
Most investors understand that you typically have to pay a premium price to buy good growth stocks. But shares of electric vehicle (EV) maker Tesla (NASDAQ: TSLA) are taking the premise to an extreme. The stock's currently priced at 200 times this year's projected earnings of $1.75 per share, and over 160 times next year's expected earnings of $2.16 per share. That's expensive by any standard, including in the technology sector.
The valuation (sort of) makes sense, though, when you understand what Tesla is in the process of becoming. Soon, it will no longer be an EV company that also makes and markets solar panels and energy-storage batteries. Instead, the plan is for it to be a robotics and robotaxi outfit that also manufactures electric vehicles. Investors are pricing the stock based on this hoped-for future rather than what the business is doing in the present. Here's what they need to know.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Comparing and contrasting
Although the company is winding down its solar roof tile business, it still makes and markets its own solar panels, as well as the energy storage equipment that makes these panels practical power sources. Moreover, EVs remain Tesla's biggest business -- accounting for $20.5 billion of its $28.2 billion in Q2 revenue -- and Tesla is still the second-biggest name in the global EV market, right behind China's BYD. Moreover, last quarter's year-over-year top-line growth of 26% suggests the company still has a little bit of magic left.
Its stock's price, however, has left the organization's fiscal results in the rear-view mirror.
Shares aren't expensive simply because Tesla is struggling to turn its revenues into profits, to be clear. The stock's also expensive by revenue standards, trading at 13 times trailing-12-month sales versus the S&P 500's trailing price-to-sales ratio of 3.7. For further comparison, the S&P 500 is currently trading at a trailing price-to-earnings ratio of 23.5 and a forward P/E of just under 20. Based on these numbers, Tesla trades at valuations between 4 and 10 times those of the average publicly traded company.
It's not like we've never seen something like this before, though. Sometimes, a company eventually grows into such steep valuations. Think Amazon, for example.
The market's pricing in growth that hasn't even started yet
Getting straight to the point, investors are pricing in a large amount of the future growth they expect from Tesla, as opposed to pricing the stock based on the business's current results. And there are two key components to this highly anticipated future. One of them is robotaxis.
Tesla's robotaxi ride-hailing venture, which at this early stage still relies largely on its Model Y vehicles, is up and running in a handful of markets. Its purpose-built Cybercab, however, represents the next generation of this venture's tech. Although the company has only rolled out a small fleet of Cybercabs in one market so far-- Austin, Texas -- it's reportedly planning to launch Cybercab-supported robotaxi services in a dozen states before the end of this year.
Although the development of these autonomous taxis has been agonizingly slow, once they're ready for wider-spread commercialization, the deployment is apt to happen fast. This will plug Tesla into a robotaxi market that Goldman Sachs expects to grow from nearly nothing now to $415 billion globally by 2035, with $48 billion of that being generated within the United States alone.
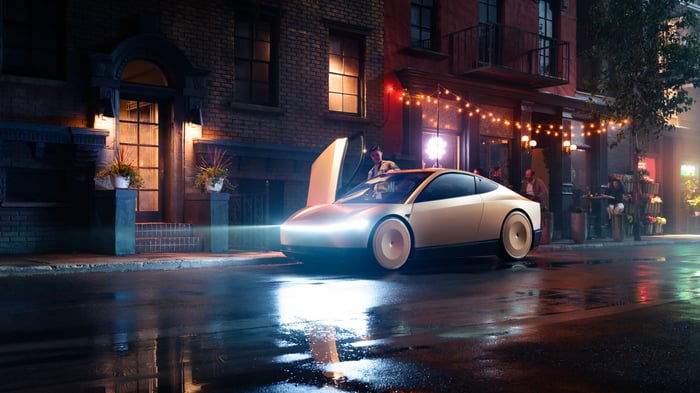
Image source: Tesla.
The other factor pumping up Tesla stock's premium valuation is arguably even more exciting. That's Tesla's entry into the AI-enabled humanoid robotics space. CEO Elon Musk suggested early this year that the company would be commercially selling its humanoid Optimus robots at scale by the end of 2027, and he hasn't said anything since to suggest that the timeline will have to be pushed back.
The commercial debut of these robots could be game-changing for the company -- not to mention the world -- in light of Musk's assessment that "Optimus will be not just Tesla's biggest product ever, but probably the biggest product ever." Although that remains to be seen, Barclays believes the market for humanoid work robots will grow to $200 billion annually by 2035. While even Musk concedes his company is facing stiff robotics competition from China, just capturing a healthy fraction of this potential business could be a boon for Tesla and its shareholders.
The growth Tesla needs from robots and robotaxis
So how much optimism about the robotics and robotaxi businesses are investors pricing in here? It's difficult to say for sure. But we can come up with a rough idea.
As it stands right now, Tesla is on pace to do on the order of $106 billion worth of EV, solar panel, and battery-storage business this year, en route to a top line of over $120 billion next year. How much more revenue would the company need to generate with robotaxis and Optimus to make its current $1.4 trillion market cap make sense? Even allowing for the type of premium valuation that many technology stocks achieve, Tesla would need a top line on the order of $300 billion to $400 billion for its current stock price to reflect a valuation in line with its peers. That's about 3 times its current sales, and most of that growth will need to come from robots and robotaxis rather than EVs and solar, as both of those businesses are now running into competitive headwinds.
Or if you want to look at the matter through the lens of earnings, Tesla's earnings per share would arguably need to quintuple -- at a minimum -- to justify the stock's current price. That would put its annual bottom line in the ballpark of $10 per share (or hopefully more) to bring the stock to a valuation that's closer to that of a typical technology company. It's likely that to deliver that type of earnings growth will take improving contributions from all of the businesses it's going to be in for the foreseeable future.
And that's just to justify the stock's price today. For Tesla shares to validly grow in value, the company will need even more top- and bottom-line growth than that.
The thing is, if the outlooks for the worldwide robotaxi and humanoid AI robot businesses are anywhere near on target, Tesla may well reach these lofty sales and earnings numbers -- eventually.
The difficult part for current shareholders and interested investors will be the waiting and the volatility stemming from the uncertainty. While Cybercab is reportedly almost ready for widespread commercialization and Tesla's Optimus robots are supposed to go into scaled-up commercial production before the end of 2027, don't forget that Musk has something of a penchant for underestimating time frames. That could leave things very unpredictable for this stock in the meantime.
James Brumley has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Amazon, Goldman Sachs Group, and Tesla. The Motley Fool recommends BYD Company and Barclays Plc. The Motley Fool has a disclosure policy.