
High-Volume, Unusual Options Activity Is Taking Nvidia and These 2 Other Hot Stocks by Storm
Wednesday’s options trading was tame. The volume was more than seven million contracts below the 90-day average of 63.17 million.
Unsurprisingly, the unusual options activity was also tame, with only one option having a Vol/OI (volume-to-open-interest) ratio over 100: ZTO Express (ZTO), at 138.88. The second highest was EQT (EQT) at 67.84.
However, just because the Vol/OI ratios weren’t jumping off the charts doesn’t mean interesting trades weren't happening.
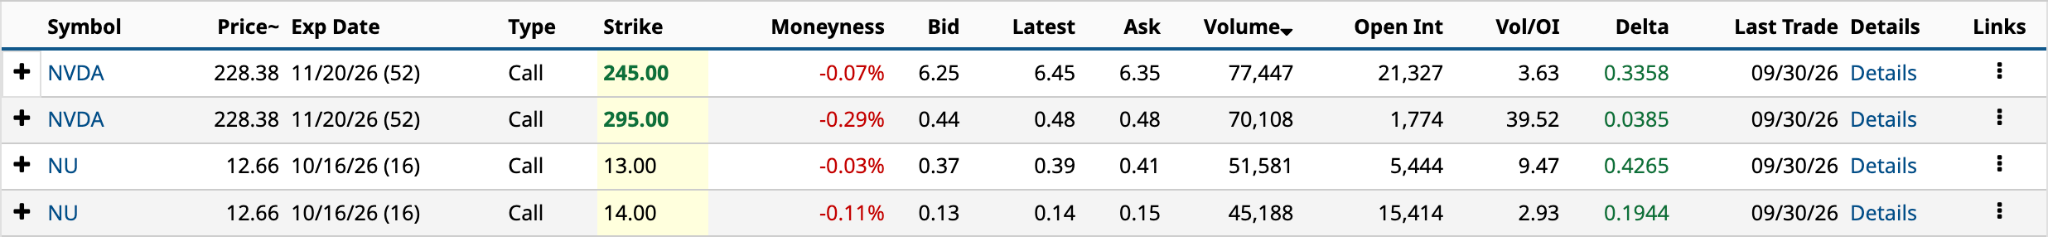
Of the options with volumes greater than 500 contracts, open interest over 100, and expiring in six days or more, 22 had volumes of 10,000 or more on the day, with the top four spots held by Nvidia (NVDA) and Nu Holdings (NU).
TeraWulf (WULF) also had unusually active, high-volume options trades yesterday. In today’s commentary, I’ll unpack the options strategies institutions may have used to make these trades.
Nvidia (NVDA)

Nvidia’s Nov. 20 $295 call was the eighth-highest Vol/OI ratio yesterday at 39.52. It accounted for 2.4% of Nvidia’s total options volume of 2.96 million, about 74,000 higher than its 30-day average.
When you dive into the options flow, you see four trades for 70,000 contracts, all at 3:20:39 p.m. ET. At first glance, you might conclude that these are two Bull Call Spreads. However, you’ll notice that the code for the $245 call and $295 call are both “O”, which indicates the trades open new positions.
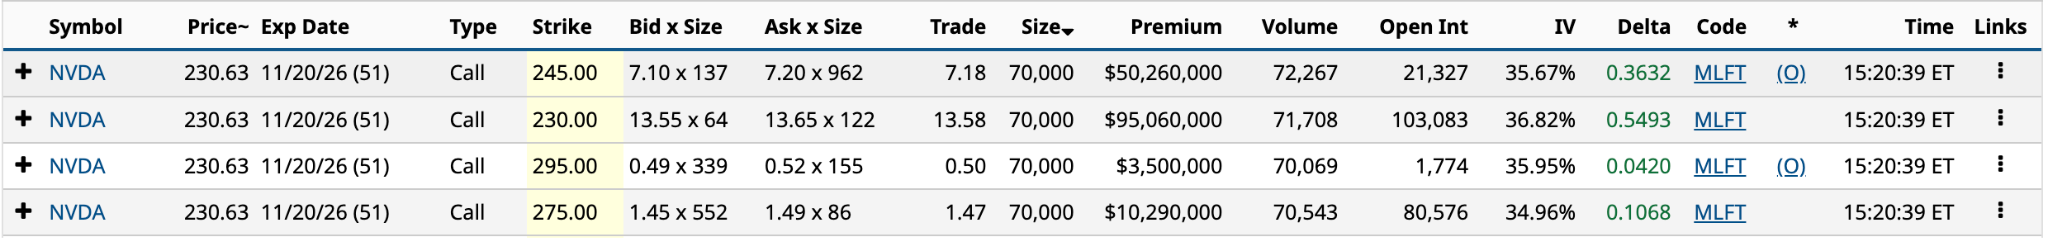
So, rather than two new bull call spreads, we likely have an institution rolling a $230/$275 call into a new $245/$295 bull call spread. If you check today's open interest, you’ll see that the OI for the $230 and $275 calls has fallen by 70,000 or more, while the OI for the $245 and $295 calls has risen by 70,000 or more. Those changes confirm the roll.
Nu Holdings (NU)

Nu Holdings’ Oct. 16 $13 call wasn’t one of the highest Vol/OI ratios yesterday at 9.47. However, it accounted for 27% of the total options volume (193,356), about 68% higher than its 30-day average. Add the volume from the Oct. 16 $14 call, and the two shown above accounted for half the day’s volume.
The two trades for 44,050 contracts shown below took place at 1:51:17 p.m. ET on Wednesday. They accounted for 91% of the contracts traded for the Oct. 16 $13 and $14 calls.

This is a vertical spread. The only question is whether it is a bull call spread or a bear call spread. If the institution were bullish, the net debit would be $0.21 [$13 call $0.30 cost - $14 call $0.09 premium]. If the institution were bearish, the net credit would be $0.21 [$13 call $0.30 premium - $14 call $0.09 cost].
What tips the scale is the “B” code for the $14 call, which indicates a “buy to open. Therefore, the institution bought 44,050 contracts of the Oct. 16 $14 call for $396,400 and sold 44,050 contracts of the Oct. 16 $13 call for $1.32 million in premium, and net credit of $925,100 [44,050 contracts * $0.21 * 100].
Here’s how the bear call spread looks as I write this late Thursday morning. Below that is the bull call spread.


While the net credit is eight cents higher than yesterday’s trade at $0.29, and the net debit is $0.34, up 13 cents, the key point is that the likelihood of making money from the bear call spread is about 20 percentage points higher, at 59.8%.
So, despite the bull call spread's higher maximum profit percentage and lower risk/reward ratio, the institution is betting NU’s share price will likely be below $13 in two weeks rather than above $14.
Nu’s shares are down nearly 12% in the past month.
TeraWulf (WULF)

TeraWulf’s Dec. 18 $24 call wasn’t one of the highest Vol/OI ratios yesterday at 9.27, but like Nu Holdings, it accounted for 24% of its total options volume of 171,597, up 33% from its 30-day average. Add the volume from the Dec. 18 $24 call, and the two shown above accounted for 35% of the day’s volume.
Digging into the options flow for the $16 and $24 call options, you’ll see two trades for the latter. The combined volume of 40,000 is 98.9% of the $24 call’s total volume. Meanwhile, the 20,000-contract trade for the $16 call is half that amount, accounting for 99.4 of the total.

All three trades happened at 3:54:33 p.m. ET, which indicates they’re part of one multi-leg trade. The only question is whether the options strategy used is a Call Ratio Spread or a Call Backspread. The former is expecting a moderate move in the share price; it is neutral to slightly bullish. The latter expects a significant move higher; it is very bullish.
The call ratio spread involves buying one Dec. 18 $16 call at $1.81 and selling two Dec. 18 $24 calls at $0.375 [$1,500,700 premium / 40,000 contracts / 100] for a net debit of $1.06 [$1.81 - 2 * 0.375], or $2.12 million [20,000 contracts * 1.06 net debit * 100].
Your maximum profit is $6.94 per contract [$24 strike price - $16 strike price - $1.06 net debit], or $13.88 million [20,000 contracts * $6.94 * 100]. It is right at the $24 strike price. You make money up to the $30.94 breakeven. Above that, losses begin to accumulate for your 20,000 uncovered $24 calls.
The call backspread involves selling one Dec. 18 $16 call at $1.81 and buying two Dec. 18 $24 calls at $0.375 [$1,500,700 premium / 40,000 contracts / 100] for a net credit of $1.06 [$1.81 - 2 * 0.375], or $2.12 million [20,000 contracts * 1.06 net credit * 100].
In this case, the maximum loss of $6.94 is right at the $24 strike price [$24 strike price - $16 strike price - $1.06 net credit]. That’s $13.88 million [20,000 * $6.94 * 100].
You have a lower breakeven price and an upper breakeven price. The former is $17.06 [$16 strike price + $1.06 net credit], while the latter is $30.94 [$24 strike price + $6.94 maximum loss]. Above $30.94, the gains are unlimited.
If the share price is $40 at expiration, the institution would make $18.12 million [($40 share price - $24 strike price * 40,000 contracts * 100) - ($40 share price - $16 strike price * 20,000 contracts * 100) + $2.12 million net credit].
This is definitely the most complicated of the three to get straight in your mind.
On the date of publication, Will Ashworth did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.