
East West Bancorp (EWBC) Stock Looks About Right Despite Its 33% Dividend Raise
East West Bancorp has delivered a powerful multiyear share price run. This raises a simple but important question for you as an investor: is the current valuation supported by the bank’s earnings profile?
- Over the past 3 years, East West Bancorp has returned 162.6%, which puts real pressure on today’s earnings multiple to justify that kind of wealth creation.
- The company lifted its quarterly dividend by 33% this year and kept its payout ratio low, which can signal confidence that current profitability and capital levels are strong enough to support both growth investment and rising cash returns to shareholders.
- There is a second opinion on East West Bancorp worth weighing. See what analysts think East West Bancorp's shares could be worth.
The issue now is whether East West Bancorp’s recent share price level is appropriately anchored to the earnings power it is currently generating.
If you are considering whether East West Bancorp’s strong three-year performance is supported by its earnings, it may be useful to compare it with 31 high quality undervalued stocks.
Does East West Bancorp Look Fairly Valued on Earnings?
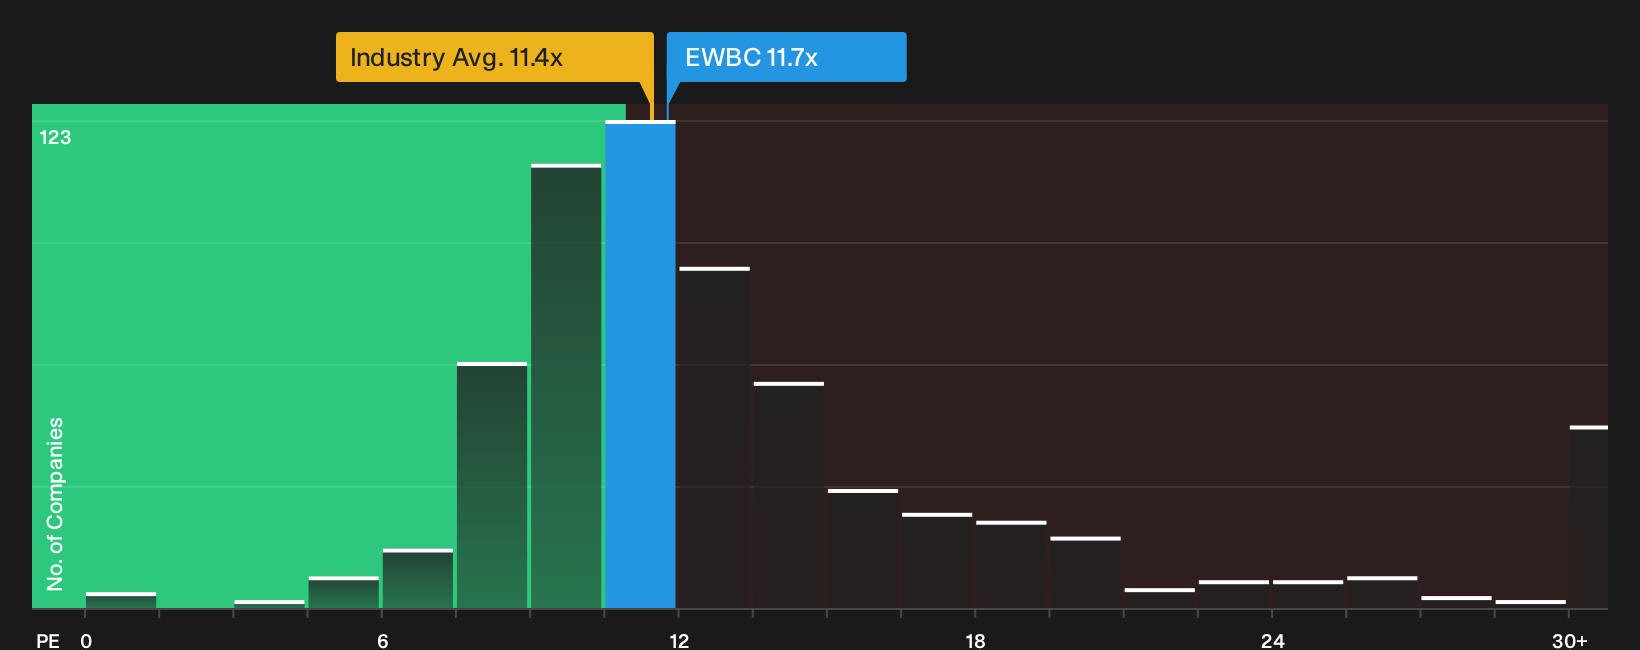
A P/E lens suits East West Bancorp because earnings remain the key driver of value for a regulated lender. The stock trades on a P/E of 11.7x, which is slightly above the broader Banks industry average of 11.4x and a touch below the 13.2x peer group level. That places East West Bancorp in a middle ground where investors are paying more than the sector at large, but not as much as for some directly comparable institutions.
The fair P/E that falls out of the valuation model sits close to the current ratio, so the market price looks about right against the earnings profile implied by analyst expectations. Because East West Bancorp recently lifted its dividend sharply on the back of strong returns on assets and equity, the stock effectively asks you to pay a near fair multiple for a bank that already backs up that payout with solid profitability metrics. For a holder, the key question is whether that balance of price and earnings quality still feels attractive at today’s level. Explore the numbers behind East West Bancorp's P/E valuation.
The East West Bancorp Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for East West Bancorp leaves off. Narratives spell out which future paths for earnings, growth and profitability would need to occur for the stock to be worth materially more or less than today's price. Each one presents fair value as a thesis about the business that can be tracked over time rather than a single frozen snapshot.
One of the top community narratives on East West Bancorp: 17% undervalued
"The main thing that has to go right is that East West Bancorp continues to grow its relationship-driven, small-business-focused noninterest-bearing deposits…"
Discover why this Narrative puts East West Bancorp at 17% undervalued.
East West Bancorp’s valuation is only one piece of your decision
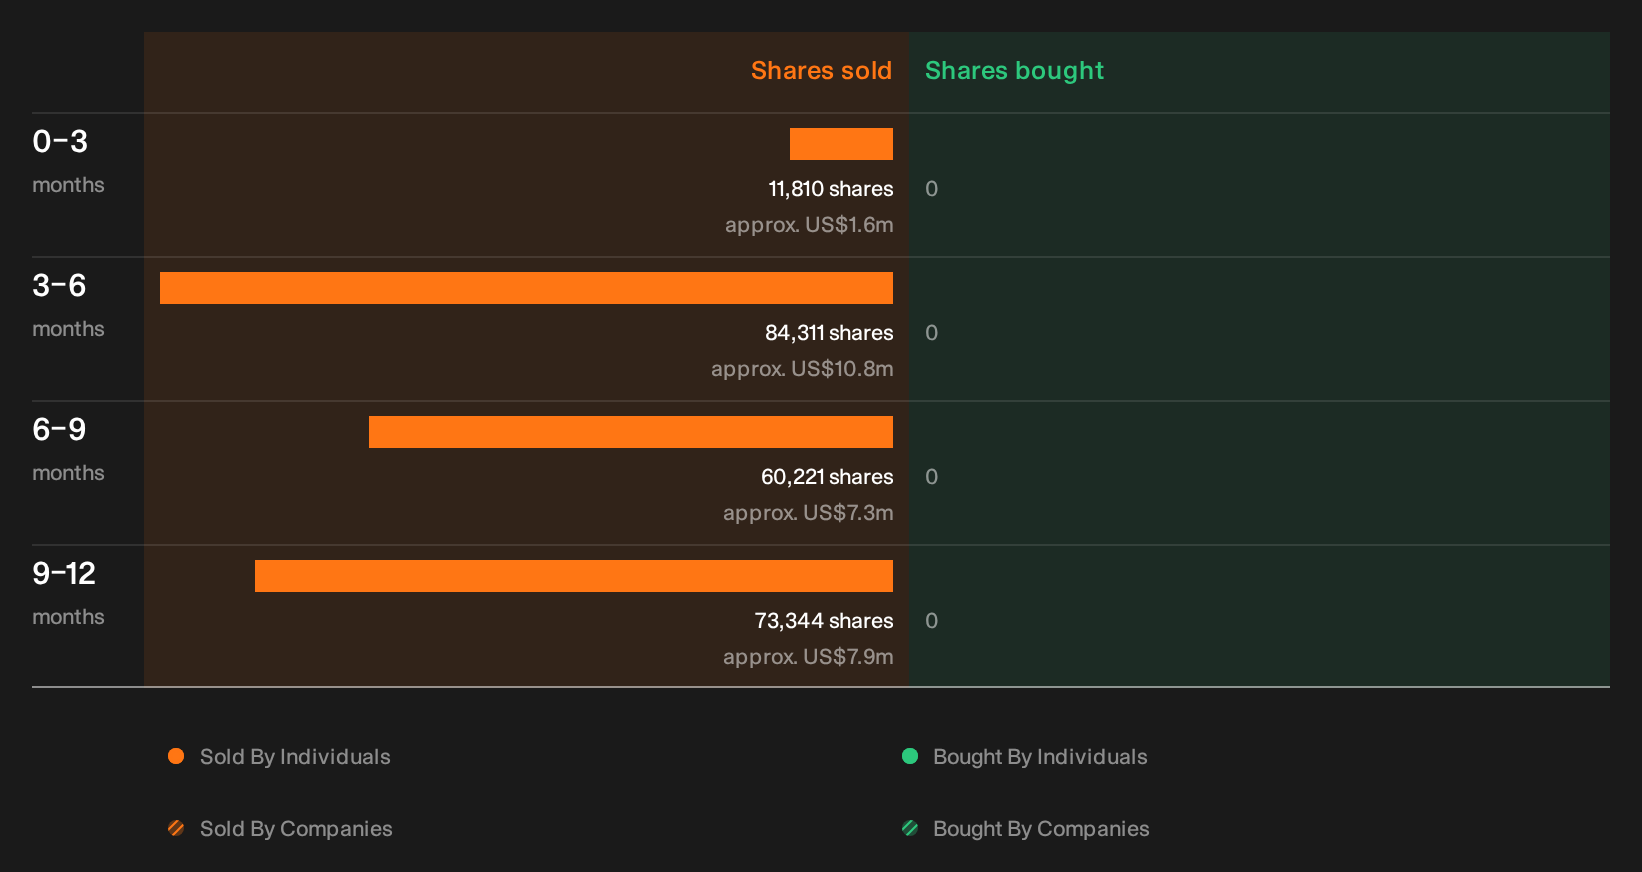
Price and earnings tell part of the story, but your next step is to examine what recent moves by key insiders might signal about how those closest to East West Bancorp view the road ahead. See the recent insider selling flagged for East West Bancorp.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com