
EQ Resources (ASX:EQR) Could Be 44% Below Fair Value After Profit Turnaround
EQ Resources earnings jump puts profitability in focus
EQ Resources (ASX:EQR) has swung from a full year loss to a profit on the back of higher sales and revenue, after reporting results for the 12 months to 30 June 2026.
EQ Resources has also been on a sharp run in the market, with the share price at A$0.445 after a 48.33% 90 day share price return and a very large 1 year total shareholder return. This suggests that investors are reassessing both its growth potential and risk profile in light of recent earnings and project execution.
Scan how EQ Resources compares to other miners pulling in fresh interest by running your filters across our hand picked 33 best rare earth metal stocks.
The share price move has already been sharp, yet EQ Resources still trades below some estimates of fair value. Is most of the rerating already in the rear view mirror, or is there meaningful upside left on the table, as the valuation section explores next?
Most Popular Narrative: 78% Overvalued
EQ Resources last closed at A$0.445, while the most followed narrative pegs fair value at A$0.25. This places the current price well above that estimate and leans heavily on a tight tungsten supply story to justify it.
I think that with the global production being roughly 84,000 to 98,000 tonnes annually, the market faces a severe deficit in 2026, with Chinese export volumes of intermediate products like Ammonium Paratungstate (APT) falling significantly. And with China controlling the majority of supply, and new Western mining projects in Australia, Spain, and North America attempting to reduce reliance, supply still remains constrained. This is why I think revenue will continue to grow and be much higher in 5 years time
See why 6 investors see EQ Resources as 78% overvalued.
Result: Fair Value of A$0.25 (OVERVALUED)
Still, EQ Resources faces real swing factors if tungsten prices ease faster than expected or if new projects add supply sooner than the market assumes.
Find out about the key risks to this EQ Resources narrative.
Another view on EQ Resources valuation
The user narrative calls EQ Resources overvalued at A$0.25 per share, yet our DCF model suggests something different. On those cash flow assumptions, the stock at A$0.45 trades below an estimated value of A$0.65, which points to a possible valuation gap rather than excess. Which story do you lean toward?
Look into how the SWS DCF model arrives at its fair value.
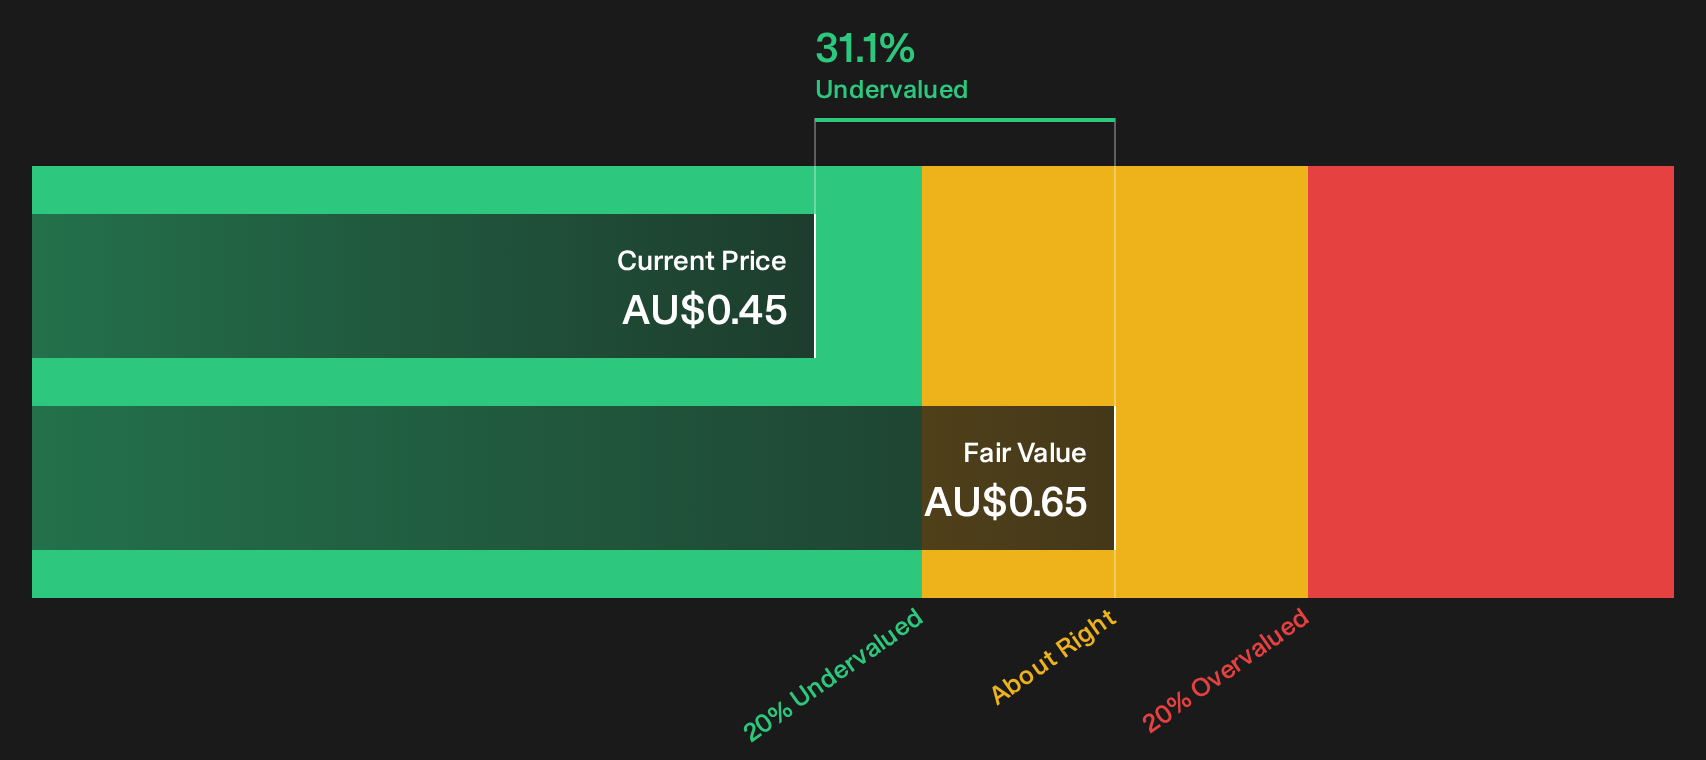
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out EQ Resources for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 4 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around EQ Resources valuation and risk can create urgency, so review the data, pressure test your thesis, and then weigh up the 3 key rewards and 3 important warning signs.
Looking for more EQ Resources style investment ideas?
If EQ Resources has sharpened your focus, do not stop here. Broader opportunities often sit just outside the obvious, and missing them can cost you real upside.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (12 results) that fit tighter risk controls.
- Hunt for mispriced quality by reviewing the 4 high quality undervalued stocks that combine strong financial profiles with compressed valuations.
- Spot future leaders early by combing through the 15 high quality undiscovered gems that most investors are not watching yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com