
3 Asset Manager Stocks Investors Are Watching As Treasury Yields Lift Cash ETF Demand
Bond yields near 5.34% on the US 10‑year Treasury have flipped the script on cash. Suddenly, short-duration fixed-income and money-market ETF sponsors sit right in the crosshairs of this rate shock, with some exposed to fresh demand for cash-like products and others facing tougher funding math. This article walks through 3 stocks from the screener most directly tied to that story and explains why their exposure matters to you now.
The three stocks below are only a starting sample, since the full Short-Duration Fixed-Income and Money-Market ETF Sponsors screen surfaced 14 more asset managers and ETF providers with equally compelling stories that are not covered here.
If you want to identify and analyze the highest conviction plays in this theme, head straight into the Short-Duration Fixed-Income and Money-Market ETF Sponsors screener.
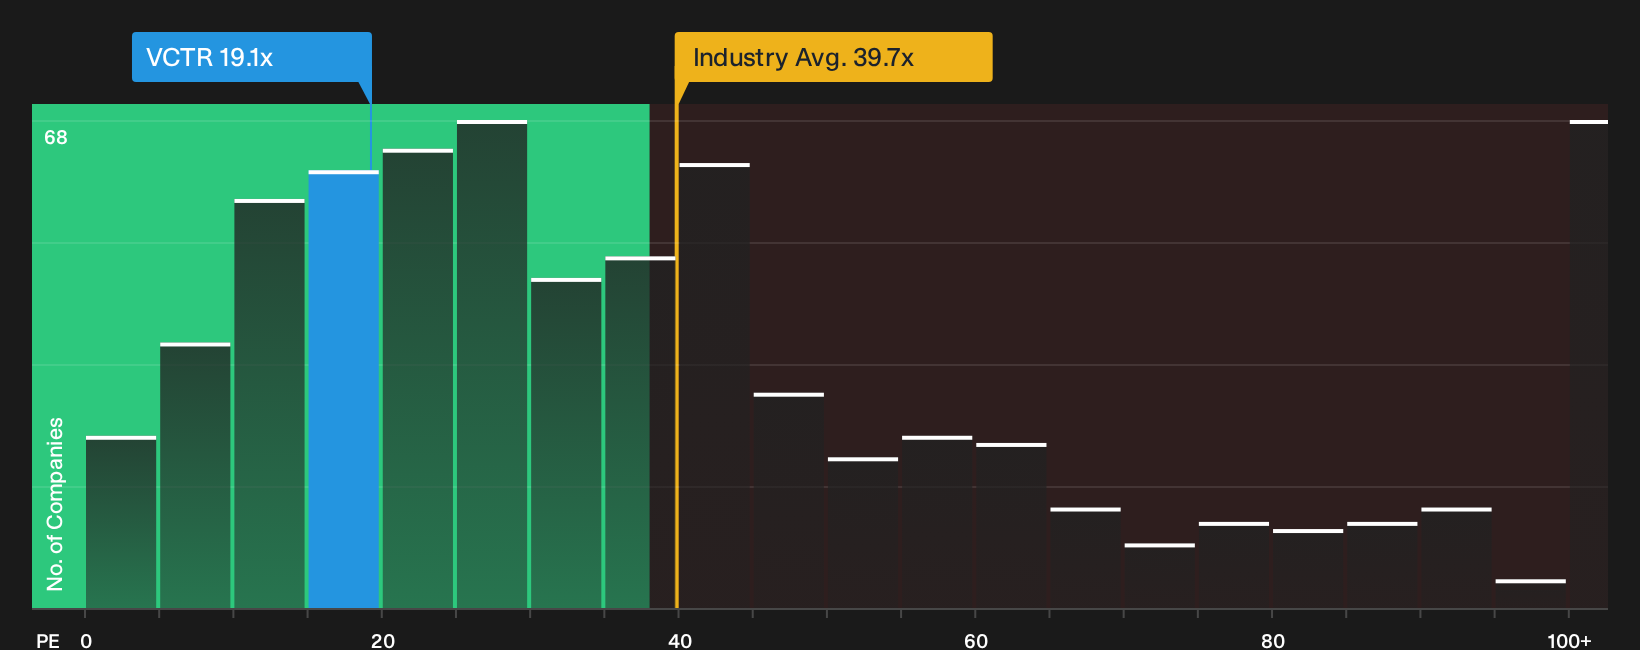
Victory Capital Holdings (VCTR)
Victory Capital Holdings is a pure-play asset manager with a growing ETF toolkit, which gives it a direct link to the surge in interest for short-duration, cash-like strategies as investors reassess where to park their money in a higher-yield world.
Victory Capital Holdings generates about US$1.6b from providing investment management services and products across mutual funds, ETFs, separate accounts, alternatives, and pooled vehicles, and with a market cap around US$6.8b it sits firmly in the larger, more established tier of asset managers.
"The continued and accelerating shift toward passive investment strategies such as ETFs and index funds threatens to erode Victory Capital's actively managed assets, putting persistent pressure on fee rates and driving reduced revenue growth in the medium and long term."
What happens if one unseen pressure on its fee mix and product lineup tightens just as demand for short-duration solutions peaks?
If that pressure on Victory Capital’s fee mix really tightens, the full narrative for Victory Capital Holdings lays out how the cash ETF rush could still accelerate the story.
Invesco (IVZ)
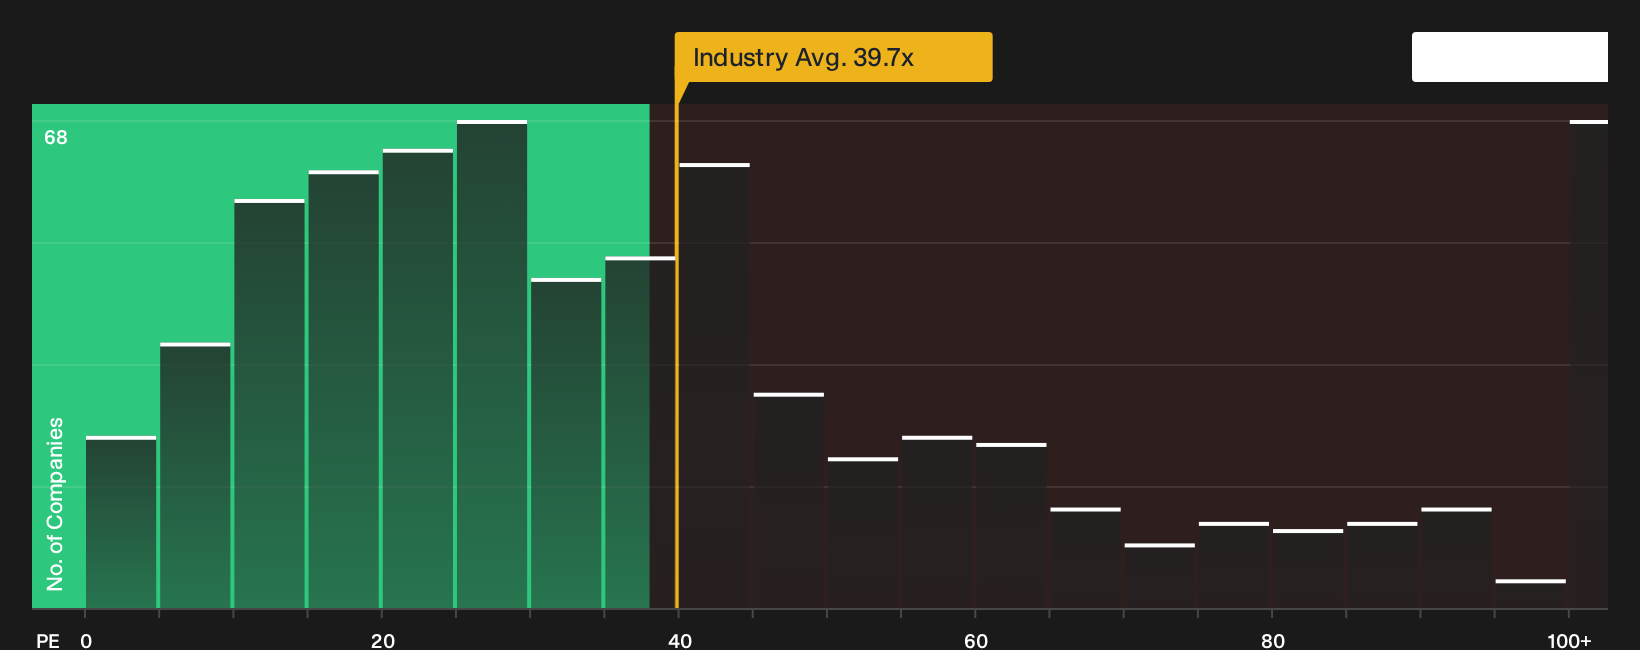
Invesco sits right in the sweet spot of this theme, running a broad ETF and money-market lineup that links directly to where investors park cash when yields on short-duration bonds and T-bills move higher.
Invesco is a global investment manager that earns about US$6.9b from investment management, mainly through funds and ETFs tied to equity, fixed income and cash-like strategies, and with a market cap near US$13.4b it ranks as a sizable asset-management platform in this short-duration ETF sponsor group.
"Invesco's strong growth in global ETF and index products (notably QQQ and QQQM) and ongoing innovation in both active and passive strategies position the firm to benefit from the continued investor shift towards low-cost, scalable investment options, supporting asset growth and potentially higher fee-based revenue and operating margins."
The real swing factor is how one quietly building pressure on its business model ultimately shapes those future margins investors are counting on.
That margin question is exactly what the full narrative for Invesco unpacks, tracing how fee pressure, ETF momentum and cash flows could be quietly reshaping Invesco’s next chapter.
ICG (LSE:ICG)
ICG is primarily a private markets and alternative credit manager, so its link to the short-duration and money-market theme comes less from running cash-like ETFs and more from how rising rates reshape demand for its floating rate debt strategies and capital solutions.
ICG plc runs private credit, secondaries and real assets strategies worldwide, earning about £897.7 million from fund management, alongside smaller contributions of £42.5 million from its investment company arm and £33.8 million from consolidated entities, and carries a market value near £5.1 billion.
"Although the tilt towards higher returning strategies in structured capital, secondaries and real assets has lifted the weighted average management fee rate to just under 1%, the move into more complex, higher barrier products increases execution risk."
What really matters now is how this pressure on those higher fee strategies eventually feeds through to margins that investors are watching closely.
That margin squeeze risk is exactly what the full narrative for ICG breaks down, showing how ICG’s higher fee engines could still be masking a longer runway for growth.
Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is flying, the best entry points are often gone. Scan these under-the-radar angles while it still matters and get in early.
- Target resilient payers using the 7 dividend fortresses and focus your watchlist on businesses built to keep distributing cash even when markets start dropping.
- Track the picks in the 90 AI infrastructure stocks and follow the companies supplying the hardware and backbone behind AI, before that demand fully shows up in headlines.
- Hunt early leaders through the 33 best rare earth metal stocks and position your research around miners tied to materials that future tech cannot easily replace.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com