
McCormick (MKC) Replaces EY With KPMG Ahead Of Foods Deal Close
- McCormick (NYSE:MKC) dismissed Ernst & Young as its independent auditor in connection with the planned Unilever foods acquisition.
- The board approved KPMG as McCormick's new external auditor to oversee financial reporting after the Unilever foods business is acquired.
- McCormick linked the auditor change to independence considerations arising from the Unilever transaction and the combined operations.
- This auditor shift tied to the Unilever foods acquisition is a fresh governance signal that investors should weigh carefully. Take a look at 2 warning signs (1 major) we have identified for McCormick.
McCormick is far from the only consumer company exposed to acquisition related shifts in oversight, so it is worth comparing it with 7 dividend fortresses.
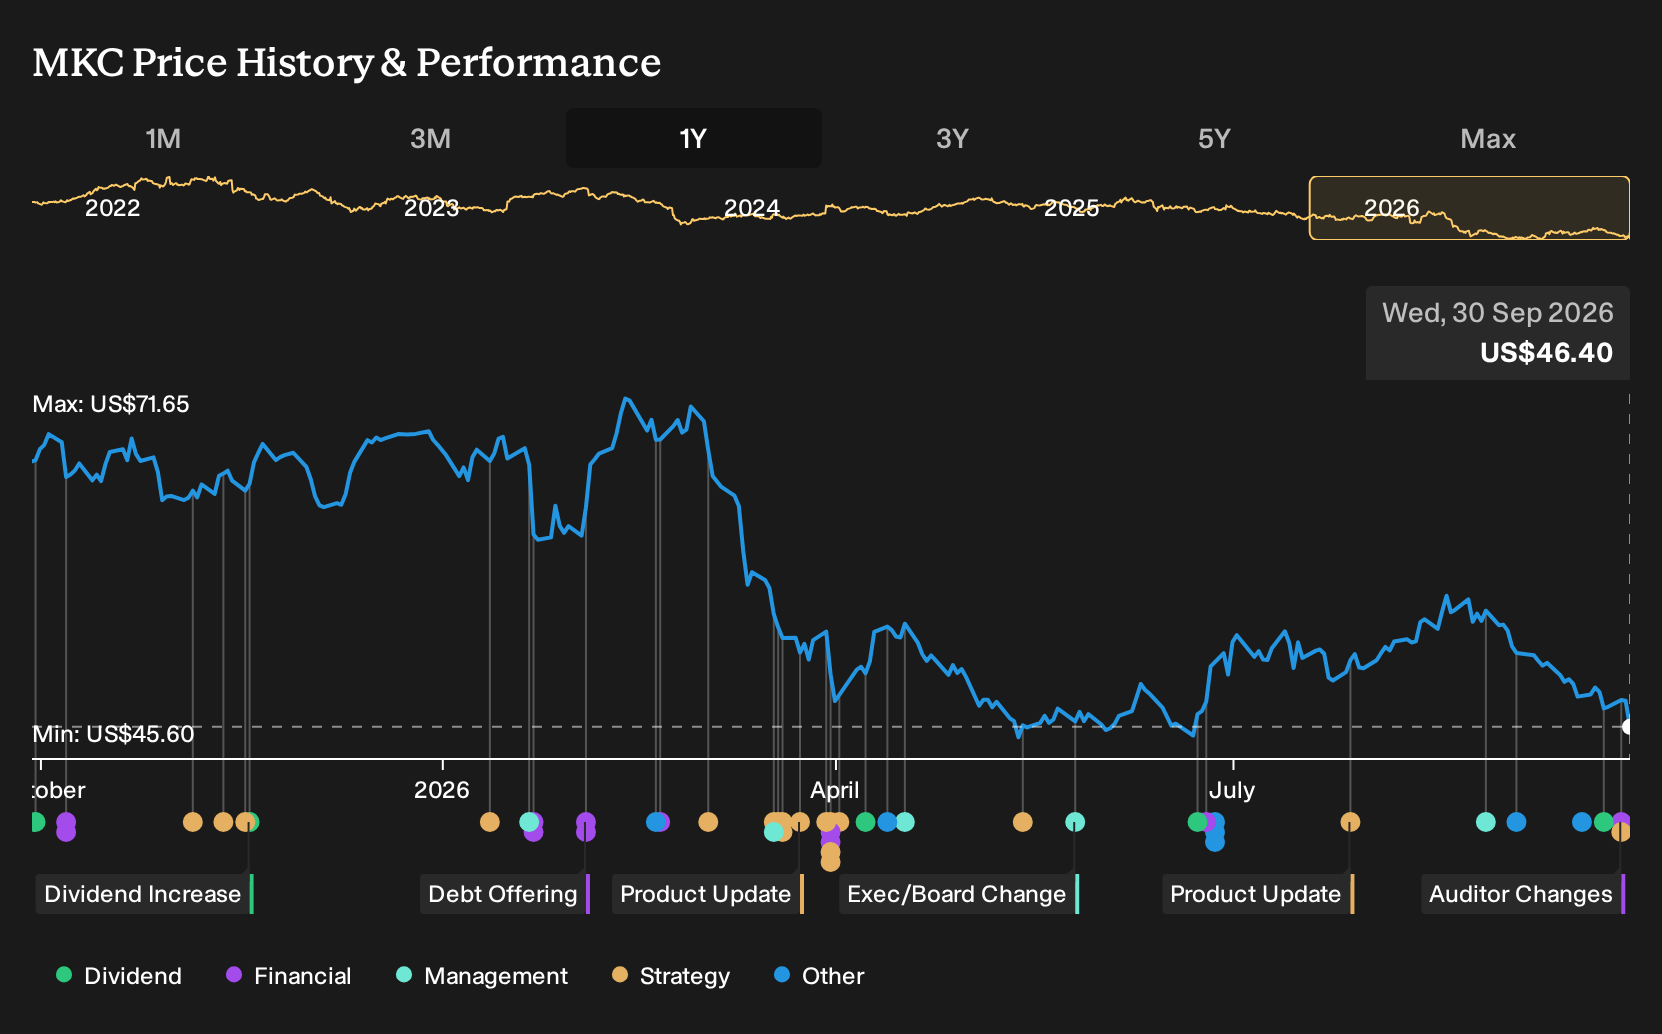
McCormick, a US-based food manufacturer with a market cap of about $13.0b, earns its influence by supplying herbs, spices, seasoning mixes, condiments, and other flavor products that sit deep in both household kitchens and the broader food industry.
See how McCormick's balance sheet measures up.
Why is McCormick changing auditors around the Unilever foods deal?
The shift from Ernst & Young to KPMG is tied to independence rules once Unilever transfers its foods business to McCormick. EY is not expected to qualify as independent under SEC standards after the combination, so the audit committee ran a proposal process and chose KPMG to sign off from the 2027 fiscal year onward.
Does this auditor change alter the McCormick Narrative?
The Narrative focuses on the Unilever Foods acquisition delivering US$600m of net cost synergies and supporting a combined operating margin ambition of 23% to 25%. Putting a new auditor in place for the post deal period aligns with that narrative, because clear independence is important for investors assessing how those synergy and margin targets are reported.
See how these catalysts shape McCormick's path to a $60.15 fair value.
What should you track next to judge the impact of this move on McCormick?
Key items to monitor include the timing and terms of the Unilever closing, the 2026 Form 10 K that ends EY’s tenure, and McCormick’s guidance updates around the November 30, 2027 year that will be KPMG’s first full audit cycle. The main test will be how clearly management and the new auditor present acquisition related costs and the targeted US$600m of synergies in those filings.
The one more check on McCormick many investors skip
Before acting on any story about McCormick, a lot of careful buyers want to know who is actually calling the shots, how they are rewarded, and what targets shape their decisions. See who is actually steering McCormick, and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com