
Hormel Foods (HRL) Buys Brakebush As Investors Ask If The Reset Makes It A Bargain
Hormel Foods (HRL) moved back into the spotlight after agreeing to buy value added chicken producer Brakebush Brothers for about $1.055b in cash, in a deal funded with cash and new debt.
Hormel Foods shares have slid over the past year despite a steady stream of company updates, with a 30 day share price return down 9.23% and a 1 year total shareholder return down 14.82%. This signals fading momentum even as the Brakebush acquisition, R&D leadership changes and a reaffirmed dividend reshape the story around the stock.
Scan how Hormel Foods compares with other consumer staples under pressure by reviewing a curated group of 27 high quality undervalued stocks that combine cash generation with more conservative balance sheets.
The sharp slide in Hormel Foods after the Brakebush deal looks less like a sudden crack in the business and more like a reset in investor mood. The price now needs to be tested against the valuation.
Most Popular Narrative: 24% Undervalued
Hormel Foods last closed at $19.96, while the most widely followed narrative pegs fair value near $26.13. This points to a sizeable gap that the recent Brakebush deal and earnings reset now sit inside.
Major supply chain automation, manufacturing footprint improvements, and the ongoing Transform and Modernize (T&M) initiatives are on track. These are expected to drive operational efficiencies and cost reductions, supporting long-run margin expansion and ultimately higher future earnings.
Hormel's diversified global platform (including China and other international markets), its expanding portfolio in snacks and plant-based protein, and a disciplined capital allocation approach position it to participate in long-term shifts toward convenience and premium food products. These factors underpin sustained revenue and mixed improvement in future periods.
See why 37 investors see Hormel Foods as 24% undervalued.
Result: Fair Value of $26.13 (UNDERVALUED)
Still, the narrative around Hormel Foods can break if commodity costs stay volatile or if margin pressure from weaker foodservice and international demand lingers longer than analysts expect.
Find out about the key risks to this Hormel Foods narrative.
Another View on Hormel Foods Valuation
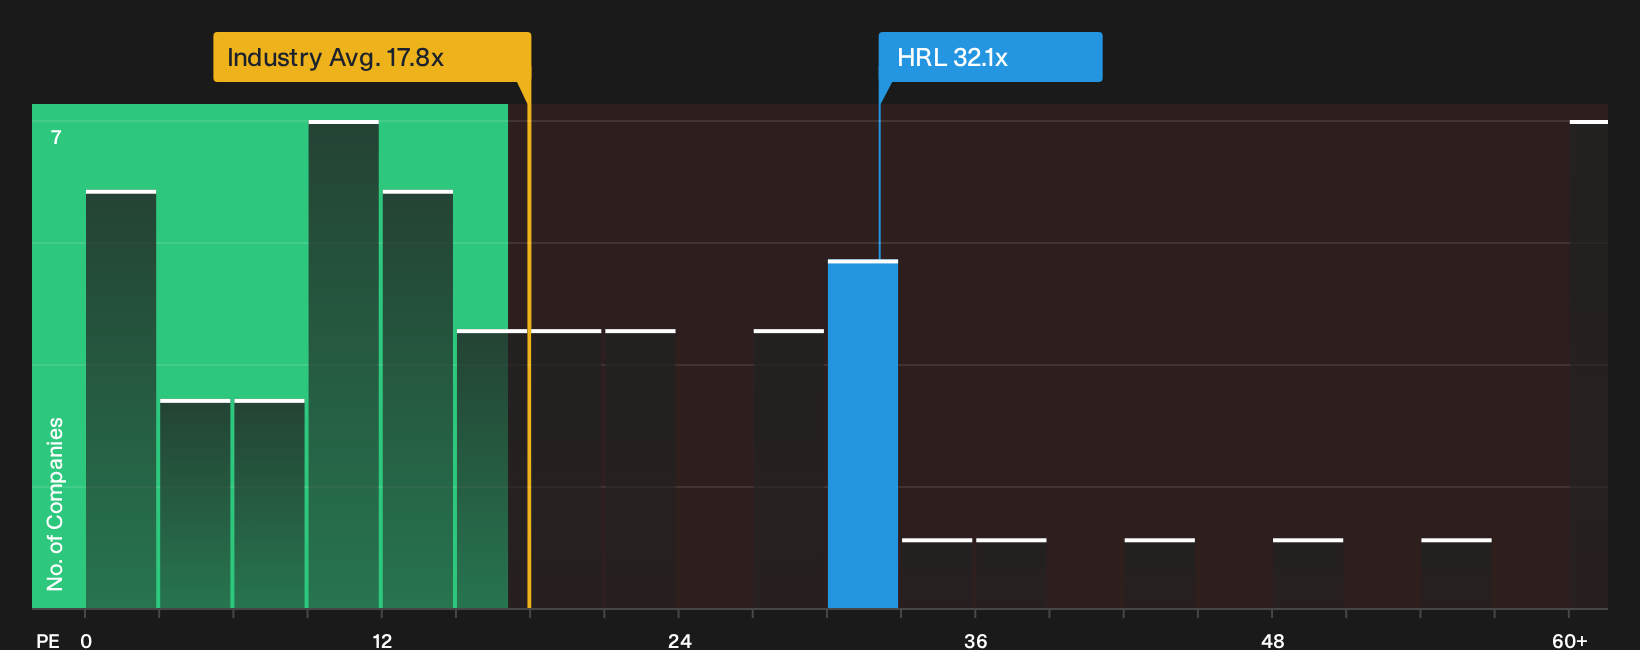
That fair value of $26.13 is built on analyst forecasts, but the market is also sending a blunt message through the current P/E. Hormel Foods trades on 32.1x earnings, compared with 17.8x for the US Food industry, 19.7x for peers and a fair ratio of 22.3x. This gap suggests investors are paying a rich price for each dollar of profit, which can amplify downside risk if earnings recovery is slower or one off items keep muddying the numbers. The question is whether you see that premium as justified or as headroom that could close.
To pressure test this richer earnings multiple against the underlying fundamentals, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Hormel Foods is clearly divided, so consider acting promptly, review the underlying data, and weigh both sides by checking the 3 key rewards and 3 important warning signs.
Looking for more Hormel Foods sized investment ideas?
If Hormel Foods has you reassessing your watchlist, do not stop here. Fresh ideas often come from looking beyond the obvious, and the next opportunity rarely waits.
- Target steadier price action by scanning 31 resilient stocks with low risk scores, focusing on ideas that score well on resilience while still offering meaningful exposure to equity returns.
- Hunt for hidden potential by reviewing 19 high quality undiscovered gems, which pair solid fundamentals with limited coverage and lower crowd attention.
- Strengthen portfolio durability by focusing on the list of solid balance sheet and fundamentals (25 results), where companies may be better able to handle shocks thanks to healthier leverage and liquidity profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com