
Palomar Holdings (PLMR) Could Be 22% Undervalued If Its Growth Narrative Holds
Palomar Holdings (PLMR) has drawn fresh attention after its recent share move, with the price closing at US$125.93. Investors are weighing that level against the insurer’s earnings profile and recent total return record.
That single day move sits against a weaker short run pattern, with the 30 day share price return down 4.5% and the 90 day share price return down 10.05%. Palomar Holdings has delivered a 12.5% one year total shareholder return and a very large 3 year total shareholder return, so recent softness looks more like fading momentum than a break in the longer run story.
Scan beyond Palomar Holdings and see how other insurers with strong multi year returns stack up by reviewing the curated 31 resilient stocks with low risk scores in the same space.
After a strong multi year run and a fresh move to US$125.93, Palomar Holdings now sits at a crossroads. Is meaningful upside still ahead, or has most of the gain already been booked into the price?
Most Popular Narrative: 22% Undervalued
Palomar Holdings is framed by the most followed narrative as worth $161.17 per share, compared with the latest close at $125.93. That gap rests on a view that the specialty insurer can convert its current underwriting profile and expansion plans into larger and more stable earnings over time.
Diversification into new specialty lines such as crop, casualty, and surety, backed by experienced new hires and recent acquisitions (e.g., Advanced AgProtection), reduces concentration risk and opens new avenues for earnings growth, as highlighted by 119% YoY casualty premium growth and the rapid scaling of the crop portfolio, supporting long-term earnings stability and growth.
See why 26 investors see Palomar Holdings as 22% undervalued.
Result: Fair Value of $161.17 (UNDERVALUED)
Still, the Palomar Holdings story can be knocked off course if catastrophe exposed lines drive heavier claims or if reinsurance terms tighten and squeeze profitability.
Find out about the key risks to this Palomar Holdings narrative.
Another View: Palomar Holdings Through Market Multiples
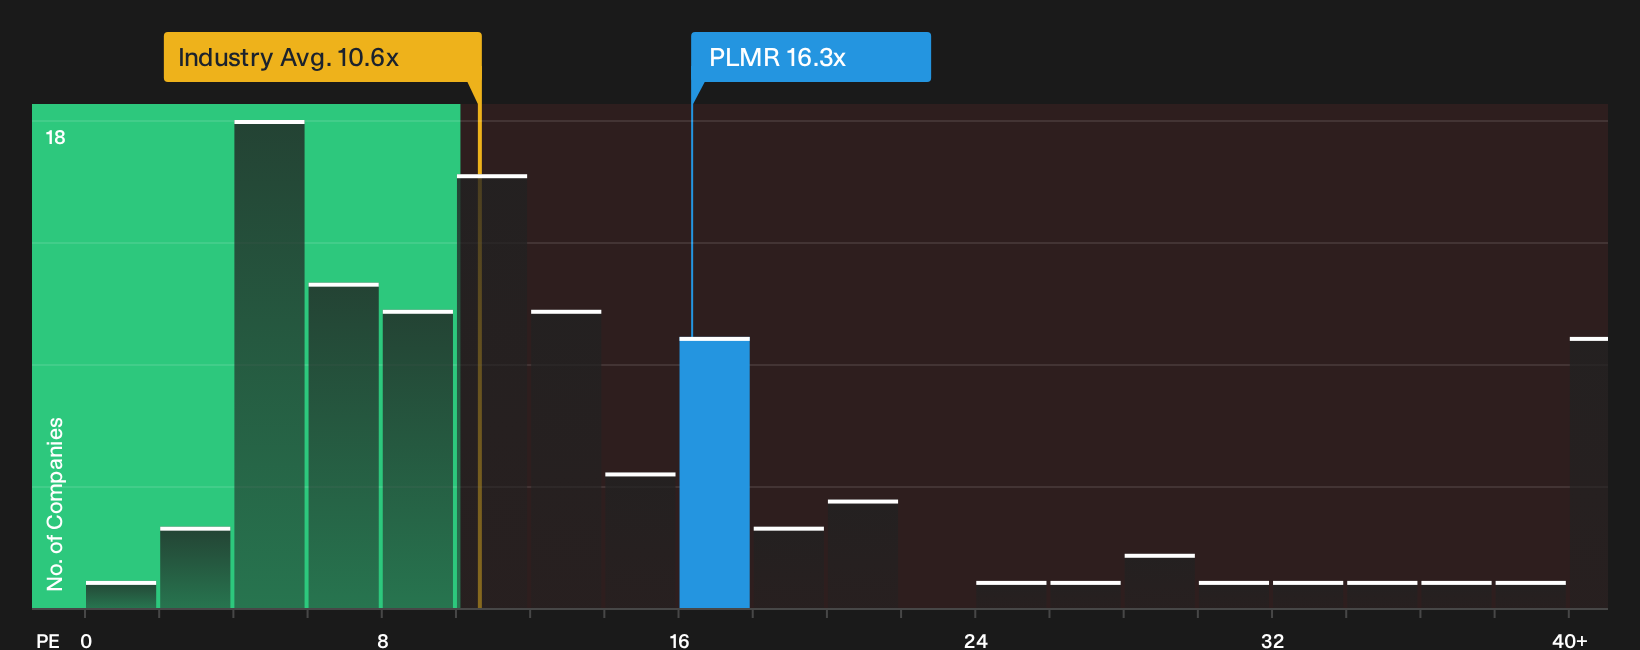
The story looks very different when Palomar Holdings is judged on its P/E ratio instead of fair value estimates. The stock trades on 16.3x earnings, which is richer than the US insurance sector at 10.6x, the peer group at 7.6x, and even its own fair ratio of 12.9x.
That gap suggests the market is already paying up for Palomar Holdings compared with both rivals and the level the fair ratio points to. This raises a simple question for investors: Is the quality of the business strong enough to justify paying materially more than sector and peer benchmarks?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Palomar Holdings so far. If you want to move quickly and own your view, weigh both sides of the story with 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Palomar Holdings?
If Palomar Holdings has you thinking about portfolio upgrades, do not stop here. Use the Simply Wall Street Screener to spot fresh, data driven opportunities with different risk and return profiles.
- Target potential mispricing across the market by reviewing companies highlighted in the 27 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses featured in the 7 dividend fortresses.
- Strengthen your downside protection by concentrating on companies within the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com