
3 Japanese Insider Owned Growth Stocks To Own In October 2026
Japanese government bond yields have climbed alongside a global bond sell off, which makes funding more expensive for highly leveraged businesses and rewards investors who can identify companies that grow from internal strength. Fast growing Japanese stocks where insiders hold a large stake can be especially interesting when capital costs are rising. This article highlights 3 such opportunities from our screener and explains what sets each one apart.
The three fast growing, high insider ownership stocks covered below are only a sample from a much broader field, as the full screen surfaced 102 more companies with similarly compelling stories that are not featured here. To hunt for your own high conviction ideas, head straight into the Fast Growing Stocks With High Insider Ownership screener to identify, filter, and analyze the combinations of growth and insider alignment that best fit your approach.
Round One (TSE:4680)
Round One runs multi entertainment centers that combine bowling, arcades, karaoke, billiards, and Spo Cha, and its push to open and franchise more venues in Japan and overseas is described as a clear growth engine. The stock is valued at about ¥335.6b.
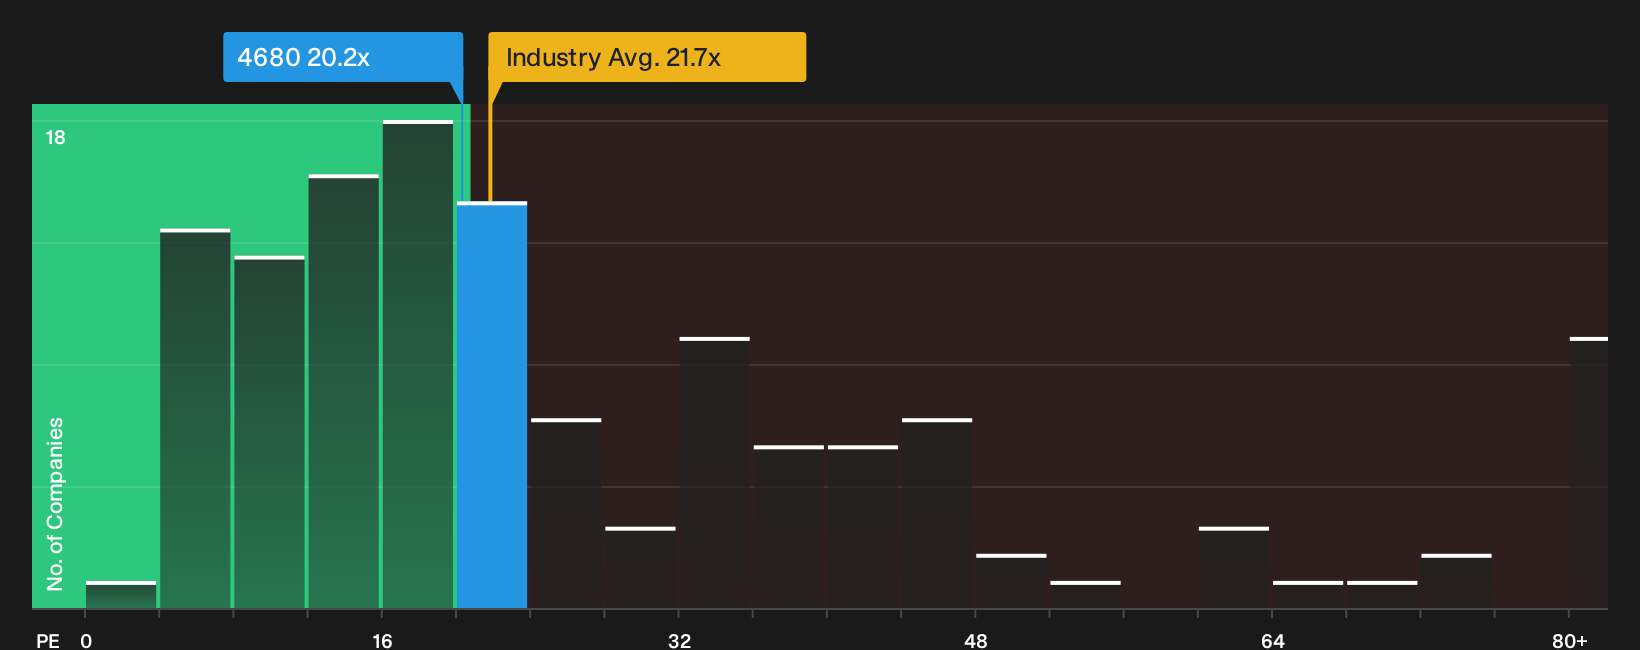
Round One fits this screener because management is leaning into expansion of its multi entertainment complexes, while earnings have grown 35.7% per year over the past 5 years and the shares trade on a P/E of 20.2x. This leaves a lot riding on how one unseen pressure shapes future profitability.
With that much riding on profitability, review the 4 key rewards and 1 important warning sign to see what might accelerate Round One or quietly cap its upside.
Micronics Japan (TSE:6871)
Micronics Japan supplies probe cards, wafer probers, and other semiconductor test gear that link it directly to fast growing chip production and inspection. The probe card segment generates about ¥84.9b versus ¥1.4b from its TE business, on a market value of roughly ¥580.8b.
Earnings growth of 89.4% over the past year and analyst forecasts for double digit gains in both profit and sales fit the “Fast Growing Stocks With High Insider Ownership” theme. Much of that story now hinges on how one critical demand trend in memory testing equipment evolves.
That hinge point in demand is exactly what you can pressure test with the analyst forecasts for Micronics Japan to see how expectations stack against the current semiconductor cycle.

JX Advanced Metals (TSE:5016)
JX Advanced Metals supplies copper and rare metal materials used across semiconductors, advanced electronics and recycling. Its Semiconductor Materials arm ties it directly into higher growth chip demand, and the group is valued at about ¥3.43t.
JX Advanced Metals connects to the screener through its semiconductor materials exposure, where earnings are forecast to rise around 13.23% a year and ROE sits near 22.9%. That mix of growth and capital efficiency is appealing, although a lot hinges on how one key demand cycle behaves.
That demand cycle is exactly what you can stress test with the 3 key rewards and 1 important major warning sign to see what might accelerate JX Advanced Metals or quietly cap its edge.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every headline catches a breakout, early entry points may already be dropping out of reach. Scan these under the radar lists while it matters and look for opportunities early.
- Track sturdy cash generators by scanning the list of solid balance sheet and fundamentals (23 results) so you can focus on businesses where financial strength backs every move.
- Target powerful income streams with the 19 dividend fortresses and see which high yield payers still pair strong payouts with resilient foundations before the crowd chases them.
- Follow long term infrastructure activity through the 39 power grid technology and infrastructure stocks and identify companies connected to grid upgrades while they are still flying under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com