
Is Improving Cash Flow Altering The Investment Case For Tutor Perini Stock?
- Tutor Perini has recently attracted attention for strong value metrics, including a P/E of 14.92 and P/B of 2.78, alongside an expanded 10.4% free cash flow margin and 18.2% annualized revenue growth over the last two years.
- The combination of a higher free cash flow margin, an improving earnings outlook and an A-rated value profile indicates that Tutor Perini is converting a healthier project mix and backlog into stronger underlying cash generation.
- We will now look at how Tutor Perini's changing free cash flow profile influences the investment narrative around backlog and earnings quality.
Tutor Perini Investment Narrative Recap
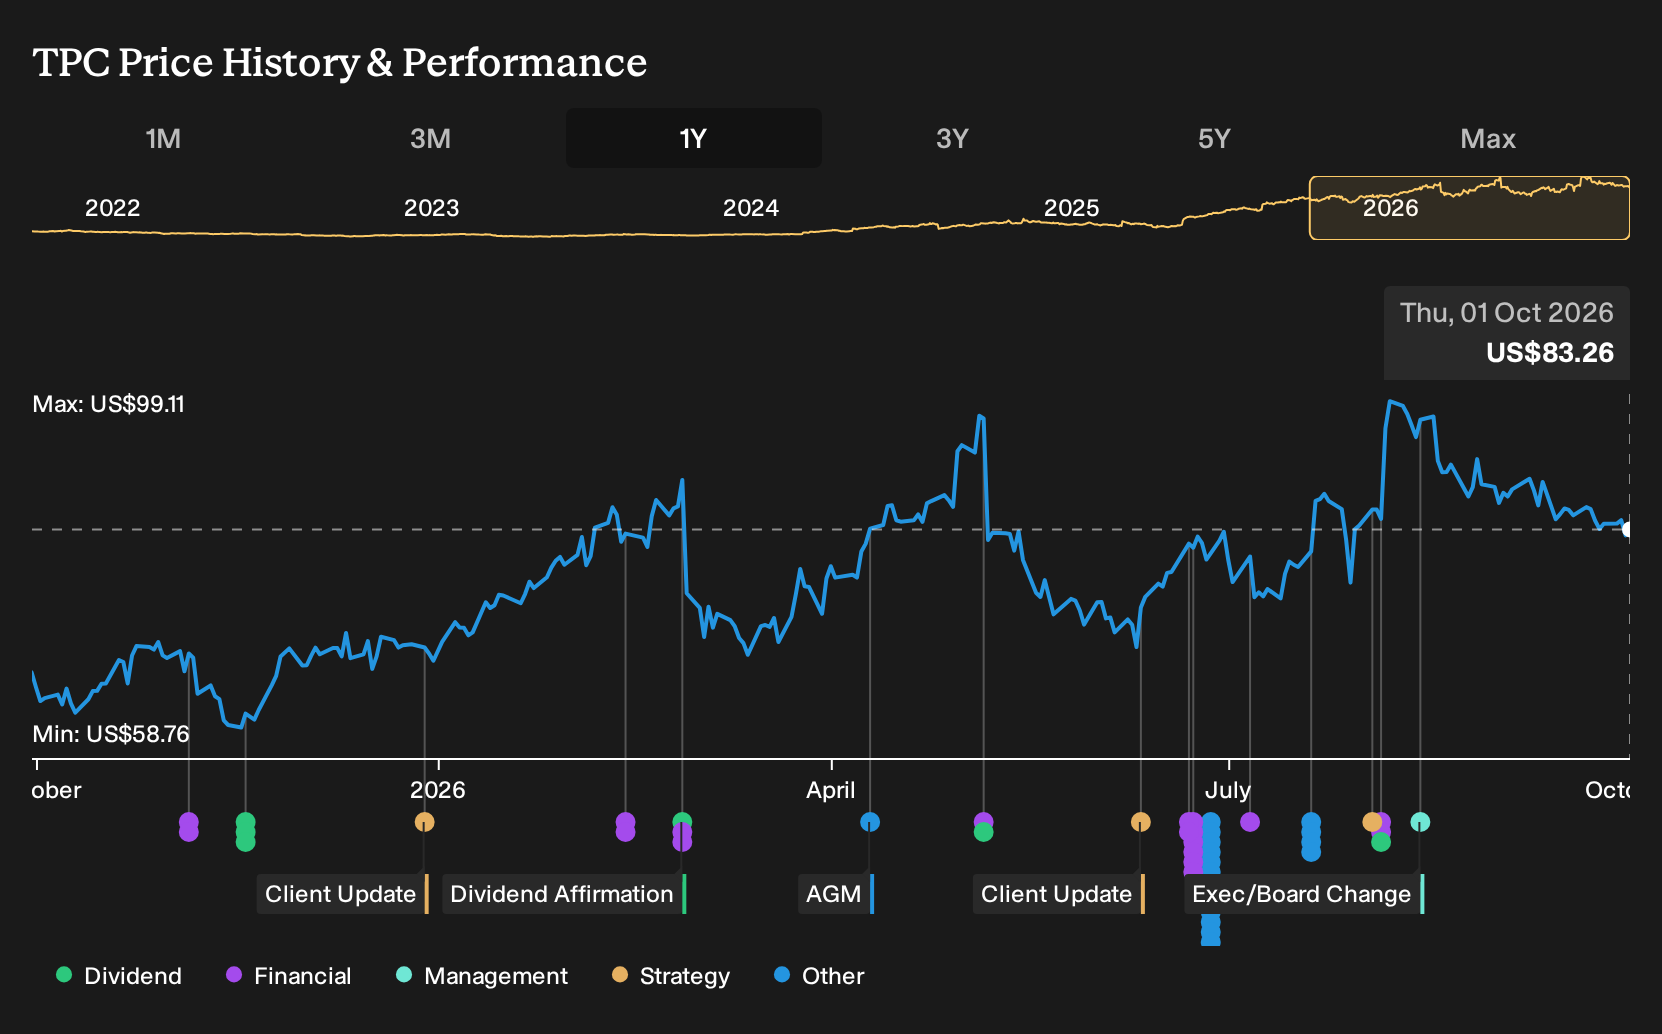
To own Tutor Perini, you need to believe the record US$21.1b backlog and healthier project mix can translate into steadier cash generation, not just headline revenue. The key short term swing factor is execution on those mega civil and building jobs. The recent share pullback and Zacks optimism do not materially change that operational focus.
The biggest risk remains old habits returning on large fixed price contracts, with cost overruns or disputes eroding the current 10.4% free cash flow margin. Earnings projections for the upcoming quarter raise expectations, which can magnify any project hiccups or litigation surprises if delivery falls short.
The most relevant recent data point is the projected 16.52% year on year earnings per share increase for the upcoming quarter. That expectation sits on top of 18.2% annualized revenue growth and a thicker free cash flow margin; as a result, the market is watching whether Tutor Perini can convert backlog into cleaner, less volatile profits.
If that earnings step up materializes, it would support the idea that better risk screening and project selection are taking hold. If it disappoints, investors may refocus on known issues such as dependence on a few very large public projects, execution risk on mega jobs and the drag from ongoing share based compensation volatility through 2026.
Tutor Perini's narrative points to revenue of US$7.6b and earnings of US$483.9 million by 2029, based on analysts assuming 10.2% yearly revenue growth and earnings rising by about US$405.8 million from US$78.1 million today.
Uncover how Tutor Perini's fair value indicates a 36% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
You are seeing one version of Tutor Perini. The lowest analysts focus on workforce and tech costs as the swing factor. They were already modeling revenue of about US$8.2b and earnings near US$567.6 million by 2029, yet still only saw a US$105 price target. Their more cautious stance could shift again once this latest news is absorbed.
Explore 4 other Tutor Perini fair value estimates, including one that suggests it could be worth just $105.00!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tutor Perini research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Tutor Perini. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tutor Perini's overall financial health at a glance.
Looking For More Ideas Beyond Tutor Perini?
If Tutor Perini has sharpened your focus on value, cash generation and balance sheet strength, it can be useful to widen the lens and compare it with other listed businesses showing similar traits using the Simply Wall St Screener.
- For investors who want potential upside with stronger fundamentals on their side, scan through a curated set of resilient opportunities using the 27 high quality undervalued stocks.
- If dependable balance sheets matter most to you, filter for companies that pair financial stability with solid fundamentals via this focused list of solid balance sheet and fundamentals (25 results).
- When you are looking for under the radar ideas rather than widely followed large caps, expand your watchlist with a hand picked pool of 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com